Budgeting Apps vs Spreadsheets: When Each One Wins
Budgeting Apps vs Spreadsheets: When Each One Wins
Which one should you choose?
Choose a budgeting app if you manage your money across several accounts and manual expense tracking has not stuck for you before. Choose a spreadsheet if your accounts are few, you want full control over the structure, or you would rather not connect a bank to a third party. Both work. Neither fixes a shortfall.
Choose a budget app based on your situation, not on a product name. Here is the short version.
| Your situation | Usually wins | Why |
|---|---|---|
| You track spending across five or more accounts and cards | App | Automatic import removes the step people skip |
| One checking account, predictable bills | Spreadsheet | Setup is minutes, upkeep is small |
| Manual expense tracking hasn't stuck for you before | App | The friction that stopped you is the data entry |
| You want custom logic (payoff models, projections) | Spreadsheet | You control every formula and column |
| You will not connect a bank to an outside service | Spreadsheet | Nothing leaves your device |
| Two people need the same numbers daily | App | Built for two logins, not one shared file |
| Irregular or seasonal income | Spreadsheet | Easier to model months that differ |
| You track spending on a phone, standing up | App | A wide grid is hard to read on a small screen |
| Your spending sits above your income | Neither | See the section near the end |
If the budget itself is not set yet, the tool is the second decision - start with how to build a family budget, then come back.
Why we do not publish prices or ratings
Deliberate choice. Prices change, free tiers shrink, features move between plans, and products get discontinued - one of the most widely used free budgeting tools shut down in 2024 and stranded millions of users. Any ranking of the best budgeting apps goes stale within a quarter, and a stale list is worse than none.
So instead of naming the best budgeting apps, this page gives you criteria and a method. Criteria do not expire.
How do you check current prices yourself in ten minutes?
Open the tool's own pricing page, then its app store listing, then search its name plus "pricing change." Three sources, ten minutes, current as of today. That beats any comparison table written months ago.
What to look for while you are there:
- What the free tier actually includes today, not what a review said last year
- Whether the monthly and yearly plans differ in features, not only in cost
- Whether the feature you care about sits in the top plan
- The refund window, and whether yearly plans are covered by it
- Recent reviews mentioning a price increase or a removed feature
Write the answer down. You will want it when the renewal lands.
What categories of tool are you choosing between?
Four, broadly: phone-first trackers built for brief checks, web dashboards that lean on charts and reports, spreadsheet templates you fill in yourself, and bridge tools that pull bank data into a spreadsheet. Named products - the well-known trackers, the big spreadsheet platforms - are examples of these categories, not recommendations.
The category decides the shape of your week. The product inside it decides less than the marketing suggests.
Does a free option go far enough?
For simple finances, often yes. A free app or a free template handles one income and a short list of expenses without complaint. Free tiers inside paid trackers are a different thing: they are a sample of the paid product, and the limits sit exactly where the useful features are.
The honest test is one of the checks in the next section: decide now what you would do if the free tier were trimmed tomorrow.
How do you handle cash spending?
By hand, in either system. No automatic feed sees cash expenses, so cash is the one part of the budget that stays manual regardless of what you choose. If a meaningful share of your spending is cash, the automation advantage shrinks and the gap between the two formats narrows.
Two workable habits: log cash on that day, or withdraw a set amount on a schedule and treat the withdrawal as the expense.
What should you check before you move your budget in?
Six things, in this order: can you get your data out, does it connect to your specific bank, how many people can log in, what happens when the free tier ends, how it handles cash, and how much setup it demands before it is useful.
Run these against any tool, app or spreadsheet:
- Export. Can you download your full history as CSV, on demand, without contacting support? If not, you are renting your own records.
- Your bank, specifically. National banks connect nearly everywhere. Smaller regional banks and credit unions are the ones that break. Test yours first.
- Second login. One shared password is not the same as two accounts.
- The end of free. Free tiers get trimmed. Ask what you lose if the current one disappears.
- Cash. An automatic feed will not see cash. You will still enter it by hand.
- Time to useful. Some tools need hours of category setup before they show anything meaningful; some show a picture in ten minutes. Know which you are signing up for.
A spreadsheet passes items 1, 4 and 6 by default and fails item 3 the moment two people edit at once.
What does connecting a bank actually involve?
You authorize a data connection that reads transactions. Modern connections use a token rather than storing your bank password, and access is read-only - it can see transactions, not move money. Details differ by tool and by bank, so read the screen in front of you rather than a description of it.
Worth doing calmly, not fearfully. A few practical habits:
- Read the consent screen instead of clicking through it. It names what is being shared.
- Connect only the accounts you budget from. Retirement, savings, and brokerage accounts rarely need to be there.
- Find the disconnect and delete-my-data controls before you need them, and check whether the connection survives a cancellation.
- Turn on two-factor sign-in wherever the tool offers it.
If none of that sits well with you, that is a legitimate answer, and it points at a spreadsheet. Privacy preference is a valid criterion, not a phobia.
How much manual work does each one really take?
A budgeting app costs you review time; a spreadsheet costs you entry time plus review time. Automatic import does not remove the work - categories still need correcting and cash still needs adding. It moves the work from typing to checking.
An illustrative example with round numbers: 100 transactions a month at 20 seconds each to enter and categorize expenses by hand is a bit over half an hour of typing; reviewing the same 100 imported items at 5 seconds each is under ten minutes. The ratio is the point - automation buys back minutes, not the whole task.
What are the real failure modes of a budgeting app?
Broken connections, category drift, and notification fatigue. A feed to a smaller bank stops without announcing itself, and you find out weeks later when the numbers make no sense. Categories get assigned by pattern and quietly put the wrong things in the wrong buckets. Alerts arrive so often that you stop reading them.
None are fatal, and all are catchable with one habit: a short weekly review where you confirm the imported items correspond to what you actually spent. That habit is the system. The tool only speeds it up.
What are the real failure modes of a spreadsheet?
A broken formula, an entry backlog, and no second pair of eyes. One deleted cell silently changes a total, and nothing warns you. Two weeks of unlogged receipts turn a ten-minute task into an hour you will not do. And when both partners edit the same file, one of them eventually overwrites the other.
Protection is straightforward: lock the formula cells, keep a copy of the blank version, and enter transactions on a schedule rather than in a heap. If you want the guardrails built in, start from a ready-made budget spreadsheet rather than a blank grid.
Which method are you actually running?
The tool matters less than the method. Zero-based budgeting, percentage splits, and envelope budgeting all run in either format, and the method decides which format is comfortable.
- Zero-based work fits a grid, because every dollar needs a line - see zero-based budgeting in a spreadsheet.
- Envelope budgeting is its own tool category with its own trade-offs, covered in digital envelopes versus cash.
- Income that changes month to month needs planning around a base rather than an average - see a setup built for irregular income.
Pick the method first. The format follows from it.
Shared access: two people, one budget
Two people need two logins to the same numbers, not one password passed back and forth. Apps handle this natively; spreadsheets handle it with a shared cloud file, which works until someone edits the wrong cell. If both of you touch the budget weekly, that difference is the deciding factor.
The harder part is not technical. Two incomes of different sizes raise their own questions about who decides what, worth settling before you choose software - budgeting as a couple with unequal incomes covers that conversation.
Does a hybrid setup make sense?
Sometimes, and only in one direction: the app tracks day-to-day transactions, the spreadsheet handles planning and projections. Running two systems for the same job doubles the upkeep and halves the reliability. Splitting them by job works.
A hybrid earns its keep when your finances have two layers - routine monthly flow plus something that needs modeling, like a payoff timeline or a property. With one layer, one tool is enough.
Why does a second switch put the habit at more risk than the first?
Because switching costs history. Move once and you lose comparability with last year, re-create every category, re-enter anything the import misses, and spend a month with numbers you do not trust. Most people survive that once. The second time, they stop budgeting instead of finishing the migration.
Two consequences worth acting on. Do the export test before you commit, not after - a tool you can leave cleanly is a tool you can enter safely. And give your choice a full three months before judging it, because almost everything feels wrong in week two.
If you are tempted to switch, first write down the specific thing that is not working. Half the time it is the method, not the software, and moving your data will not fix it.
How do you test both before committing?
Run one month in each, in parallel, on the same real transactions. Not a demo, not a sample file - your actual month. You will know which one you kept up with, and that is the only comparison that predicts anything.
Judge them on four things: did you open it, did you trust the numbers, did your partner use it, and did it tell you something new. A tool that fails the first question fails all of them.
What counts as working?
You know what you spent, roughly where it went, and what is left before the next paycheck - without a research project. That is the bar. Not perfect categorization, not a color-coded dashboard.
Signs it is holding: you check it in minutes rather than avoiding it, surprise charges get noticed within days, and you can answer a spending question without opening five tabs. If those are true, the tool is fine and you can stop shopping.
When neither one will help
If your spending is above your income, neither a budgeting app nor a spreadsheet will change the outcome. Both are measuring instruments. A scale does not make you lighter, and a budget tool does not create money that is not there.
An illustrative example with round numbers: take-home 4,000 a month against fixed expenses of 4,300. No categorization scheme closes that. The 300 has to come from a change in the numbers themselves - income up, fixed costs down, or a timeline renegotiated with whoever you owe.
That is a different project from choosing software. It starts with three steps: list every recurring expense and cancel what you do not use, call the largest fixed bills and ask what options exist, and get the gap on paper so you know its size. Tracking still helps - it tells you the number. It is not the fix.
If the gap is temporary and you know when it closes, tracking closely gets you through it. If it repeats every month, treat it as a structural problem rather than a tracking problem, and talk to a nonprofit credit counselor instead of buying another tool.
So which one wins?
The one you will still be using in six months. Every durable difference between these two formats comes down to whether the work it takes to manage the budget fits your week. Automatic import wins when data entry is what stops you. A grid wins when control and privacy are what you want.
Pick from the table at the top, run the six checks before you move anything in, then give it three months.
Denis Goncharenko
Head of Content
Editorial Policy: no secondary statistics. Every claim is linked to an official source and dated — datasets and methods are open for review.
Was this article helpful?
Same blogs
Saving Money on Groceries Is Not a Test of Willpower
Federal data shows six grocery categories moving at different rates, not one bill rising evenly. Why the national CPI, the CES spending survey, and USDA's own forecast are each the wrong number to budget against - and how to build your own monthly figure from 8 to 12 weeks of receipts instead.
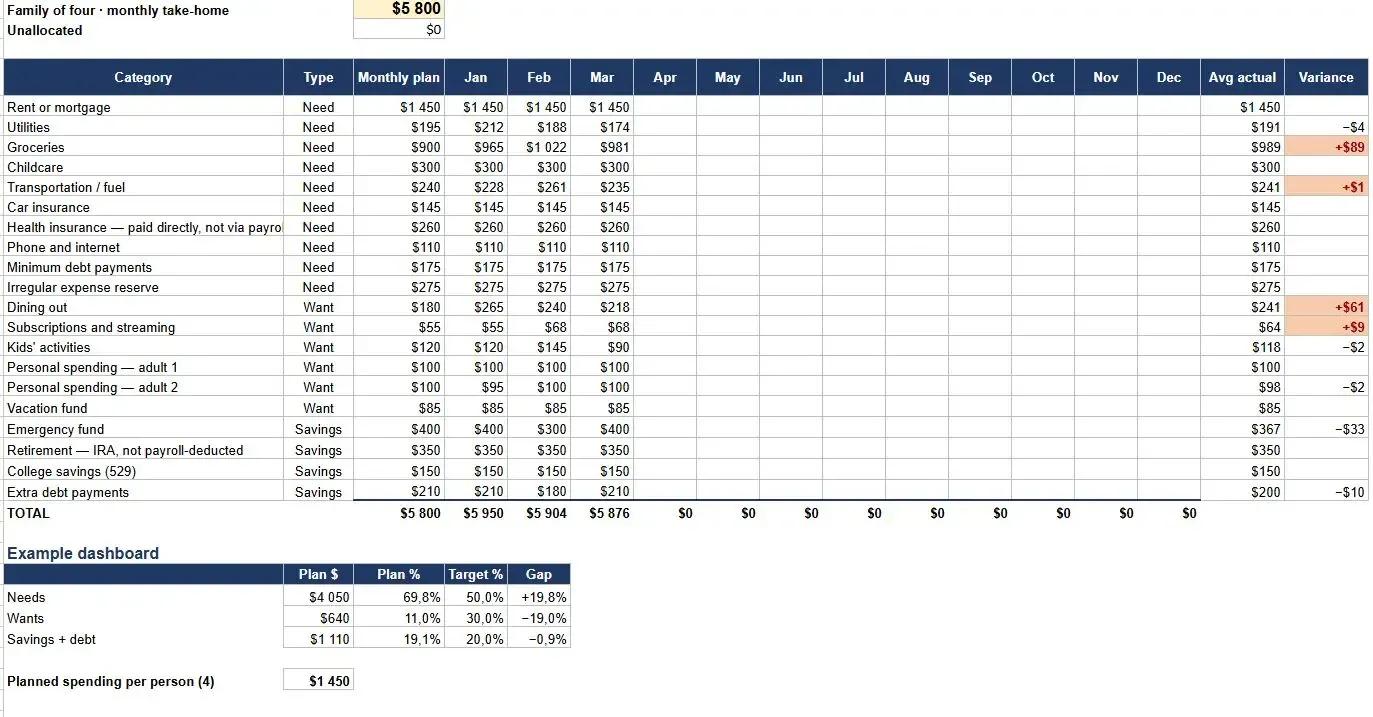
Free Family Budget Template for Excel and Google Sheets
A free household budget spreadsheet for families of three to five, with categories pre-filled and a separate tab that spreads yearly bills like insurance and registration across all twelve months. No email, no sign-up, works in Excel and Google Sheets.
Why Parent PLUS Loans Have Become a Hidden Retirement Crisis for American Parents
Parent PLUS loans can follow parents into retirement, reduce savings, and expose Social Security benefits to offset after default. Here is what near-retirement borrowers should know.