Age & Residency
You generally need to be at least 18 and a U.S. resident to be considered as a borrower. Basic eligibility comes first, before the lender reviews the rest of your request.
A roof repair, a medical bill, or a few payments you want under one schedule can make money feel tight. In Maine, a personal loan lets you borrow a set amount and repay it in equal installments over time, often without collateral. With Bromoney, you fill out one form, compare the options available to you side by side, and decide what, if anything, fits. Lenders make the decision, and no outcome is promised.
Compare lenders and decide,
Get startedSecure 256-bit Connection
A personal loan is a lump-sum installment loan, often $1,000 to $40,000, repaid in fixed monthly payments over a set term, usually two to seven years. The borrower gets the funds at once, then repays the amount borrowed plus interest until the balance is paid off. It's usually unsecured, meaning no collateral is required, and it's also called an unsecured installment loan. In plain terms, it can help you consolidate higher-interest debt or cover one larger planned cost.
You fill out one form and review the options available to you in your account, with the loan amount, APR, and payment schedule laid out where you can actually compare them. Maine treats personal loans as fixed scheduled payments over a set term, so the calendar matters as much as the amount borrowed. You choose who moves forward, or you leave it there with no obligation.
A lower score can feel heavy, but Maine law does not set a credit score floor for personal loans. The state rules focus on lender licensing and cost limits, not a borrower score threshold. The lender still decides whether to make an offer and what terms to show you.
Maine limits finance charges on closed-end consumer loans. The maximum is generally 30% per year on the first $2,000 of unpaid balance, 24% on the portion above $2,000 through $4,000, and 18% on the portion above $4,000. If the amount financed exceeds $8,000, the maximum is generally 18% per year on the entire amount financed. Federal TILA disclosures also show the APR, finance charge, payment schedule, and total of payments before you become contractually obligated.
A lender generally needs a Maine Supervised Lender License if it makes, takes assignment of, or services consumer loans with a finance charge exceeding 12.25% per year, calculated according to the actuarial method, or loans secured by an interest in real estate. Other registration or exemption rules may apply. Banks and credit unions operate under separate regulatory frameworks.
The request may take a few minutes. Here's what most Maine lenders require before they can review your information and decide whether to offer credit.
You generally need to be at least 18 and a U.S. resident to be considered as a borrower. Basic eligibility comes first, before the lender reviews the rest of your request.
A lender will want to see income you can verify, which may include wages, benefits, or another steady source. They'll also look at your credit profile and current debt load to judge whether the payment is realistic, so bad credit may be considered, but it can come with tougher terms.
You usually need an active bank account so funds can be sent and monthly payments can be handled under the loan terms. Before you choose, make sure that account can support the payment date without squeezing essentials.
Sometimes the bill is real before the cash is. A Portland homeowner may be looking at a roof repair before winter, while someone in Bangor might want several monthly bills under one fixed schedule. In Lewiston, a medical bill arriving sooner than expected can create the same squeeze. Whatever started the search, compare the cost and repayment dates before you decide whether the payment fits.
Maine's average FICO Score was 731 in 2025, according to Experian. A statewide average does not determine whether an individual borrower will qualify for a loan, and lenders use their own underwriting criteria.
A new personal loan adds one more scheduled payment to the obligations you already carry. That's why the total repayment term deserves the same attention as the monthly amount. In Lewiston and across Maine, the safer comparison is APR plus total of payments, not the monthly figure by itself.
In the Federal Reserve's 2025 SHED, 63% of U.S. adults said they would cover a $400 emergency expense completely using cash or its equivalent. That means 37% would use another method or would not be able to cover it. This is a national figure, not a Maine-specific measure.
The Maine Bureau of Consumer Credit Protection is the place to check applicable lender authorization and file a complaint. Maine also limits finance charges and delinquency charges on covered consumer loans. After a court judgment, Maine generally limits the amount subject to a court-ordered installment payment from earnings to the lesser of 25% of applicable earnings or the amount above 40 times the higher of the federal or Maine minimum hourly wage.
A planned bill in Maine can leave you wondering what the monthly payment would really look like. Bromoney keeps the next step simple: one form, then the options available to you in your account with the loan amount, APR, and repayment schedule shown side by side. We're not a lender, and we don't make credit decisions. You compare, choose who to move forward with, or stop there, and it's free to start with no obligation. We take a responsible approach to your data and do our best to prevent unwanted calls. Bromoney is operated by Money Broker LLC (DE File No. 10406065).
Estimate exactly how much you'll owe before you commit. Enter your loan amount and repayment term to see total costs, including fees and interest, laid out clearly.
Calculate my loanMaine consumer lending is overseen by the Maine Bureau of Consumer Credit Protection. A lender generally needs a Maine Supervised Lender License if it makes, takes assignment of, or services consumer loans with a finance charge exceeding 12.25% per year, calculated according to the actuarial method, or loans secured by an interest in real estate. Other registration or exemption rules may apply. Maine also limits finance charges and delinquency charges on covered consumer loans. Federal Truth in Lending Act disclosures apply before the borrower becomes contractually obligated, and covered military borrowers receive the Military Lending Act's 36% MAPR protection.
Legal status
Active, supervised market
Maine has an active, supervised consumer lending market. Nonbank lenders must meet state requirements to operate, and the regulator monitors compliance.
Regulator
Maine Bureau of Consumer Credit Protection
This agency oversees lender licensing, accepts borrower complaints, and provides public records you can use to check whether a lender is authorized in Maine.
License required
For covered supervised lenders
A lender generally needs a Maine Supervised Lender License if it makes, takes assignment of, or services consumer loans with a finance charge exceeding 12.25% per year, calculated according to the actuarial method, or loans secured by an interest in real estate. Other registration or exemption rules may apply.
Repayment structure
Fixed scheduled payments over a set term
A personal loan is paid back in equal installments on a set schedule. That schedule is established when the loan is signed.
Collateral
Usually not required
Most personal loans are unsecured and not backed by property. A secured option can exist, but it must be stated in the offer terms.
Minimum credit score
None set by state law
Maine does not set a credit score floor for personal loans. Each lender makes its own credit decision, and no particular result is promised.
Finance charge limits
30% / 24% / 18% tiered limits
For closed-end consumer loans, Maine generally limits the finance charge calculated according to the actuarial method to 30% per year on the first $2,000 of unpaid balance, 24% on the portion above $2,000 through $4,000, and 18% on the portion above $4,000. If the amount financed exceeds $8,000, the maximum is generally 18% per year on the entire amount financed.
Late fee
Limited by state law
A delinquency charge may generally apply only after an installment remains unpaid for 15 days. One permitted calculation is 5% of the unpaid installment, capped at $10; an alternative calculation may be based on the allowable deferral charge.
Prepayment
Generally allowed without penalty
A consumer generally may prepay a consumer credit transaction in full or in part at any time without penalty, subject to limited statutory exceptions.
Cost disclosure (TILA)
Required before you become obligated
For a covered product, federal Truth in Lending Act rules require disclosure of the APR, finance charge, and total of payments before you sign.
Wage garnishment cap
25% or amount above 40x the higher applicable minimum wage, whichever is less
After a court judgment, Maine generally limits the amount subject to a court-ordered installment payment from earnings to the lesser of 25% of applicable earnings or the amount by which those earnings exceed 40 times the higher of the federal or Maine minimum hourly wage. Additional exemptions and exceptions apply.
The information on this page is educational and is not legal or financial advice. Which rules apply to a specific loan depends on the lender's status, license or registration, loan amount, finance charge, collateral, and other facts under Maine law. Regulations can change. Verify current requirements with the Maine Bureau of Consumer Credit Protection and the official Maine consumer credit code. Reviewed as of October 5, 2026.
Moving card debt to a balance-transfer card can give you breathing room during a lower-APR intro period. The catch is structure. You're still using revolving credit, the APR can change after the promo ends, and there usually isn't a fixed payoff date unless you make one and stick with it.
A home equity loan or another secured option may come with a lower cost because collateral backs the debt. That can help when you're borrowing for a major project, but your asset is on the line if payments aren't made, and the process can take more paperwork than an unsecured personal loan.
A credit union personal loan or local nonprofit option can be worth a look, especially if you're already a member or want a lower-cost place to borrow close to home. Loan amounts, APR caps, and local rules change by state, so check your state page before you choose.
Personal loans online don't work the same way in every state. Loan amounts, terms, APR, rate caps, and legal rules can change depending on where you live, whether you borrow to consolidate debt, cover a large expense, or compare options with bad credit. Choose your state below before you repay under local rules.
A personal loan in Maine is a fixed amount borrowed and repaid through scheduled payments over a set term, usually without collateral. The Maine Bureau of Consumer Credit Protection regulates consumer lending in the state. A lender generally needs a Maine Supervised Lender License if it makes, takes assignment of, or services consumer loans with a finance charge exceeding 12.25% per year, calculated according to the actuarial method, or loans secured by an interest in real estate. Other registration or exemption rules may apply. Banks and credit unions operate under separate regulatory frameworks. For a covered product, federal Truth in Lending Act rules require key cost disclosures before you become contractually obligated.
Personal loans in Maine may come from banks, credit unions, and nonbank consumer lenders. Bromoney is a free loan marketplace, not a lender, and it does not make credit decisions. A lender generally needs a Maine Supervised Lender License if it makes, takes assignment of, or services consumer loans with a finance charge exceeding 12.25% per year, calculated according to the actuarial method, or loans secured by an interest in real estate. Other registration or exemption rules may apply. You can verify applicable authorization through the Maine Bureau of Consumer Credit Protection.
Maine law sets no minimum credit score for a personal loan. A bad credit score usually means a FICO score below 580, but that's a market convention, not a Maine legal category. A lower score isn't a character judgment, and it doesn't close the door by itself. The lender still makes the credit decision, and no outcome is promised.
Personal loan amounts and terms in Maine depend on the rules tied to the lender's license and the lender's own review. The payment schedule is fixed when you sign, so it doesn't change on its own later. In your account, each option shows the loan amount, APR, scheduled payment, and term side by side. Compare the APR with the total of payments, because a lower APR alone doesn't always mean fewer dollars paid over the life of the loan.
Maine limits finance charges on closed-end consumer loans. Under 9-A M.R.S. § 2-401, the maximum finance charge calculated according to the actuarial method is generally 30% per year on the part of the unpaid balance up to $2,000, 24% on the part above $2,000 through $4,000, and 18% on the part above $4,000. If the amount financed exceeds $8,000, the maximum is generally 18% per year on the entire amount financed. Before you become contractually obligated on a covered loan, the lender must also provide the disclosures required by the federal Truth in Lending Act, including the APR, finance charge, payment schedule, and total of payments.
A personal loan in Maine usually doesn't require collateral. Most are unsecured, which means your property isn't backing the loan. Secured personal loans do exist, but that would be spelled out in a specific offer rather than assumed under Maine law. If an option requires collateral or a co-borrower, you'll see that term before you agree, and the lender makes that call.
Personal loans can affect your credit in Maine because the request may place a hard inquiry on your credit file. After an account opens, on-time payments and account activity may be reported to the major credit bureaus, but lenders don't all report the same way, so ask before you count on it to support your history. Missed payments, collections, or a court judgment can hurt your score. Under federal law, a negative entry can remain on your credit report for around seven years. A personal loan isn't a credit repair tool.
A delinquency charge may generally apply only after an installment remains unpaid for 15 days. Maine law limits the amount: one permitted calculation is 5% of the unpaid installment, capped at $10, while an alternative calculation may be based on the allowable deferral charge. If the debt remains unpaid, a creditor may pursue collection or sue. After a court judgment, Maine generally limits the amount subject to a court-ordered installment payment from earnings to the lesser of 25% of applicable earnings or the amount by which those earnings exceed 40 times the higher of the federal or Maine minimum hourly wage, subject to additional exemptions and exceptions. Consumer debt is a civil matter, not a criminal one.
FICO and VantageScore can show different numbers for the same person because they use different models, bureau files, and update timing.
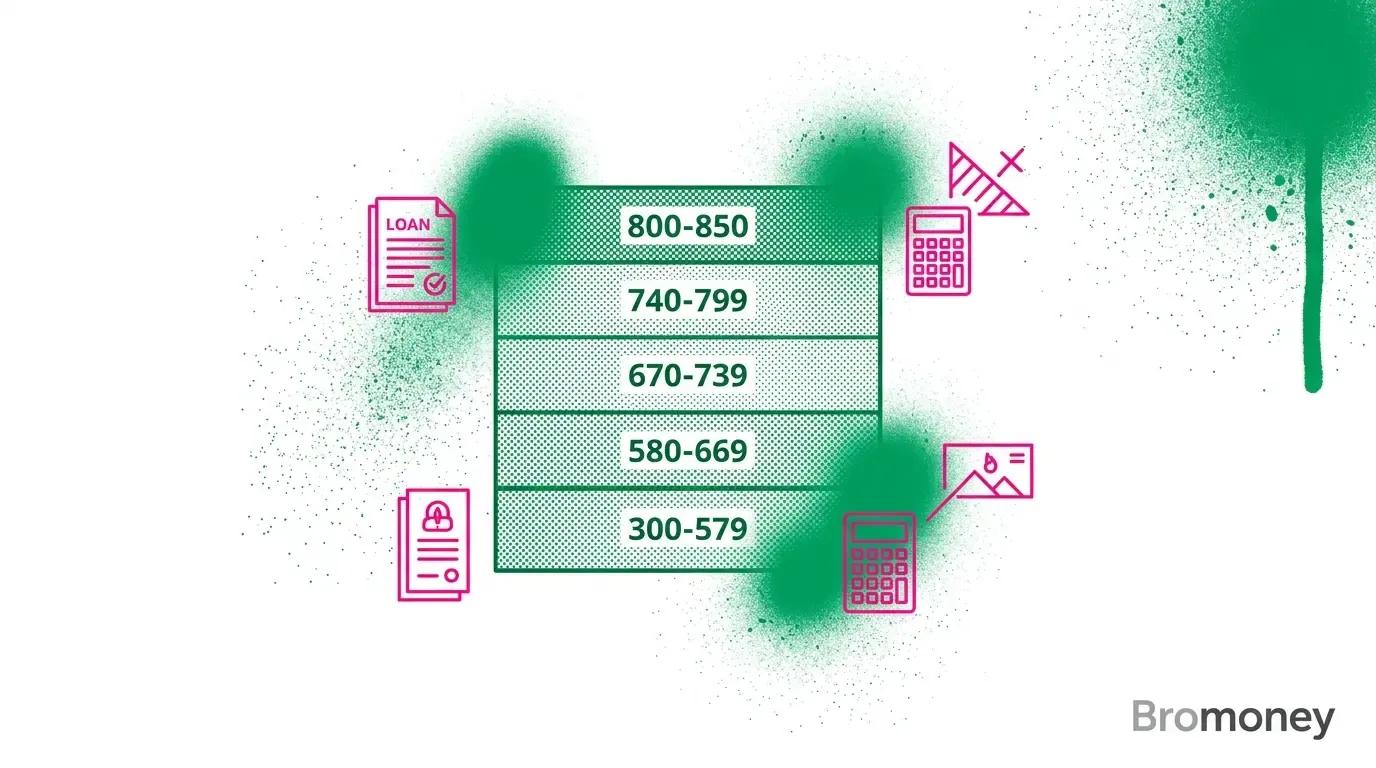
A practical guide to U.S. credit score ranges, including what 580, 650, 720, and 800 mean for mortgages, auto loans, credit cards, and rates.
A practical guide to private mortgage refinancing, including lender types, approval steps, costs, risks, and exit strategy.
We bridge the gap between your financial goals and premier lending services nationwide.
Bromoney is a free loan marketplace operated by Money Broker LLC (DE File No. 10406065). Bromoney is not a lender and does not make credit decisions. Lenders may run hard inquiries; more than one inquiry is possible, and your credit score can be affected. A lower credit score does not disqualify you by law. The decision belongs to the lender, and no outcome is promised. Submitting a request shares your details with lenders and partners in our marketplace, who may contact you by phone, text, or email. Before you become contractually obligated on a covered loan, the lender must provide the disclosures required by the federal Truth in Lending Act, including the APR, finance charge, payment schedule, and total of payments. Personal lending in Maine is regulated by the Maine Bureau of Consumer Credit Protection. Covered military borrowers are protected by the Military Lending Act's 36% MAPR limit.
You know the drill: one loan request, then waiting for the calls to start. Here you stay in control — we treat your information with care, you compare the options available to you, and you choose which lender or partner to move forward with. We can't speak for every partner, but we do our best to keep unwanted calls down.
Submitted over a secure connection