

Identity and Residency
Lenders typically ask that you're 18 or older, live in the U.S. and can show a government-issued ID and a Social Security number, so they can confirm who you are. Some lenders accept an ITIN instead.

Need to clear high-interest cards, renovate an apartment or pay for a move in New York? With a personal loan, the full sum is yours up front, so you can cover it in one go.
A New York personal loan lets you borrow one lump sum for nearly any purpose, from card balances to a renovation, and repay it in fixed monthly installments. New York law is on your side while you compare: a licensed lender works under a rate ceiling, so even its priciest offer has a limit.
Checking available options with Bromoney does not require a credit-bureau inquiry and does not affect your credit score. If you select a partner and continue, that partner may perform a hard credit inquiry that can affect your score.
In New York, the licensed-lender rules cover personal loans of $25,000 or less, so a $20,000 loan from a licensee gets the same fee and rate protections as a $3,000 one. The amount you're offered depends on the lender.
New York personal loans are repaid over a fixed number of months, so the date of your last payment is known before you sign. A credit card balance has no such finish line if you only pay the minimum.
Under the federal Truth in Lending Act, the lender has to disclose the APR, the finance charge and the total you'll repay before you're bound by anything. With a sum this size, that total tells you the real price, and turning an offer down costs you nothing.
The request may take a few minutes. Here's what most New York lenders require before they can review your information and decide whether to offer credit.
Lenders typically ask that you're 18 or older, live in the U.S. and can show a government-issued ID and a Social Security number, so they can confirm who you are. Some lenders accept an ITIN instead.
Lenders want income they can verify, such as wages, self-employment income or benefits, and they compare your monthly debt payments with it. The lower your debt-to-income ratio, the more room a new payment has.
An active checking account in your name is usually where the funds arrive and where monthly payments are drawn from. If you're consolidating, some lenders may pay your creditors directly instead.
In New York, some costs land all at once: storm damage to a Long Island house after a nor'easter, a last-minute flight home for a family emergency, a large vet bill, or a laptop you need for work. One personal loan can take care of a bill like that in full. If the cost is modest and you'd rather repay it within months, look at an installment loan as well.
In New York, plenty of reasons are planned: a kitchen or bathroom update in a co-op, moving costs for a first apartment in Albany or Rochester, a wedding in the Hudson Valley, or several card balances you'd like to roll into one payment. Consolidating makes sense only when the new loan's APR beats the rates on those cards, and how debt consolidation works shows how to run the numbers.
In New York, borrowing $5,000 for 36 months at the 25% ceiling works out to about $198.80 a month, roughly $7,157 altogether, and $2,157 of that is interest. A state-licensed lender can't charge more than that, and offers may come in below it. The DTI and max loan calculator helps you see which payment your budget can absorb. If you'd rather repay in fixed monthly amounts with a clear end date, compare installment loans in New York as well.
In New York, $10,000 spread over 60 months at that same ceiling means about $293.51 a month, roughly $17,611 altogether, and $7,611 of that is interest. The longer the schedule, the smaller each payment and the bigger the total, so read why a lower payment can cost more before you settle on a term.
In New York, a nonbank lender needs a state license to charge more than the general 16% limit on a personal loan. Search the lender's exact legal name in the NY Dept. of Financial Services list of supervised companies before you send documents or sign.
A personal loan is often a bigger number, so a gap of a few points in APR can add hundreds of dollars to what you repay. Bromoney gives you a single form in place of typing the same details for each lender. If partners respond with offers, you'll find them in your account with the rate, payment, length and total cost laid out together. You choose whether to continue and with which partner, and using Bromoney costs nothing.
Estimate exactly how much you'll owe before you commit. Enter your loan amount and repayment term to see total costs, including fees and interest, laid out clearly.
Calculate my loanNew York law sets these limits for licensed lenders; they describe your protections, not an offer from any lender.
Lender's own loan fees
Not allowed
Origination, service, brokerage and commission charges can't be stacked on top of interest by a licensee.
Interest taken up front
Not allowed
Interest is figured on the principal you still owe and can't be deducted in advance or compounded.
Late charge
Up to 5%, once
Only after a payment is more than 10 days overdue, and once per missed installment.
If you're overcharged
Twice the interest back
A licensee that knowingly charges more interest than allowed forfeits it, and you can recover twice the interest you paid.
State rules reviewed November 2026. For the current limits, check with the New York State Department of Financial Services.
Personal loans for debt consolidation pay off several card or loan balances and replace them with one monthly payment and a known payoff date. The move pays off when the new APR and total cost are lower than what those balances cost you, so compare before you shift the debt.
Small personal loans, starting at $1,000, can cover one bill, a repair or a deposit without a commitment that lasts for years. A smaller amount usually comes with a shorter term, which keeps the total interest down.
Unsecured personal loans rely on your income and credit rather than an asset, which is how most personal loans are set up. Secured personal loans put something you own, like a savings account or a vehicle, behind the debt, so check which type your offer is before you sign.
Some lenders let you add a cosigner or a co-borrower. Personal loans with a cosigner, or joint personal loans, can help when your income or credit history is thin, because the lender also weighs the second person's profile, but that person shares responsibility for every payment.
Personal loans for home improvement, a move, a wedding or a major car repair let you pay for a larger cost at once and spread it over the months ahead instead of carrying it on a card at a revolving rate.
Personal loans for bad credit exist, but the price shifts: a lender that works with a lower score usually balances the risk with a higher APR, a smaller amount or a shorter term. That's why lining up several options matters more here than anywhere else on this page.
Personal loan rules differ by state, from rate limits to the licenses lenders need. Pick your state to see what applies there and compare the options available to you.
In New York, a personal loan gives you the full amount at the start, and you pay it back in fixed monthly installments. Early payments go mostly to interest and later ones mostly to principal, until the balance reaches zero.
Possibly. In New York, lenders set their own credit criteria, and a lender may also consider your income and existing debt, so your score is only part of the picture, though no result is promised. You can view an estimated credit score in your Bromoney account for free, and if a lender declines you, read what to do after a loan denial. Worried your score could hold you back? Compare the options for New York bad credit loans first and see what lenders weigh besides the number.
In New York, how much you're offered comes down to the lender's view of your income, debts and credit history. For an amount above the licensed-lender line, ask the lender which New York rules its offer falls under. To pick a number you can live with, run a budget stress test first.
In New York, the timing is set by each lender and may differ between offers. Before sharing its terms, a partner may want to confirm some details, for example with recent pay stubs or bank statements.
In New York, the request form covers your income, job, bank account and how to reach you. Later on, a lender may want ID or proof of income, so keep the documents checklist handy.
In New York, interest on a loan from a state-licensed lender is capped at 25% a year, the line drawn by N.Y. Penal Law § 190.40. Banks and credit unions operate under other rules and may price differently, and the offers partners send on Bromoney may differ from one another. Look at the APR rather than the interest rate to see the full yearly cost.
Yes, and finishing early can save you money. In New York, a licensed lender can add only the charges state law lists, and an early-payoff fee isn't among them, while repaying ahead may also trim the interest you owe. Try the debt payoff calculator to see how many months you could cut.
In New York, any late charge from a licensed lender has to stay within the state limit, and your agreement says when it kicks in. A missed payment may be reported to the credit bureaus by the lender, so if money is tight before a due date, call the lender early.
No. State law in New York doesn't authorize payday loans, so they aren't offered there. A personal loan spreads a larger amount over many monthly installments instead of one lump repayment.
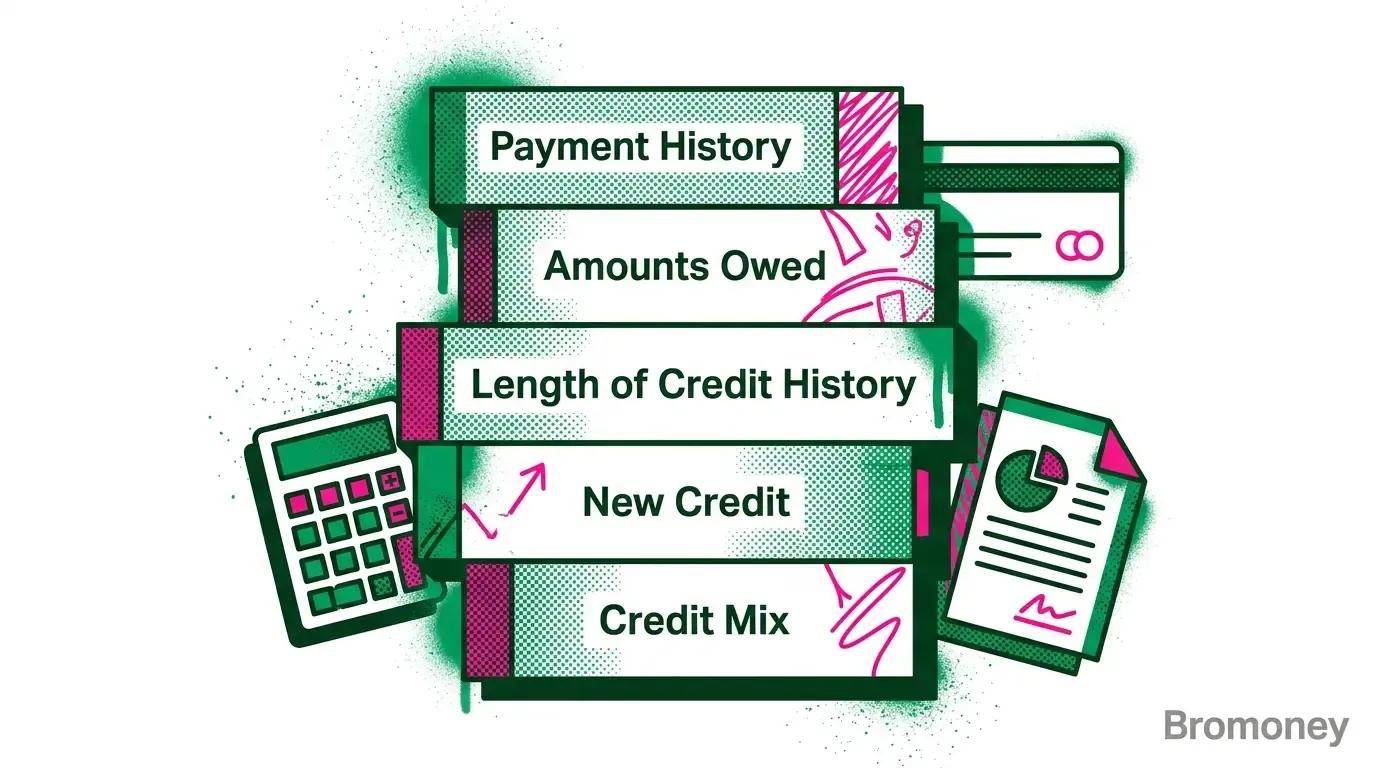
A practical breakdown of the five FICO Score factors, how each one works, and which actions improve your credit profile first.
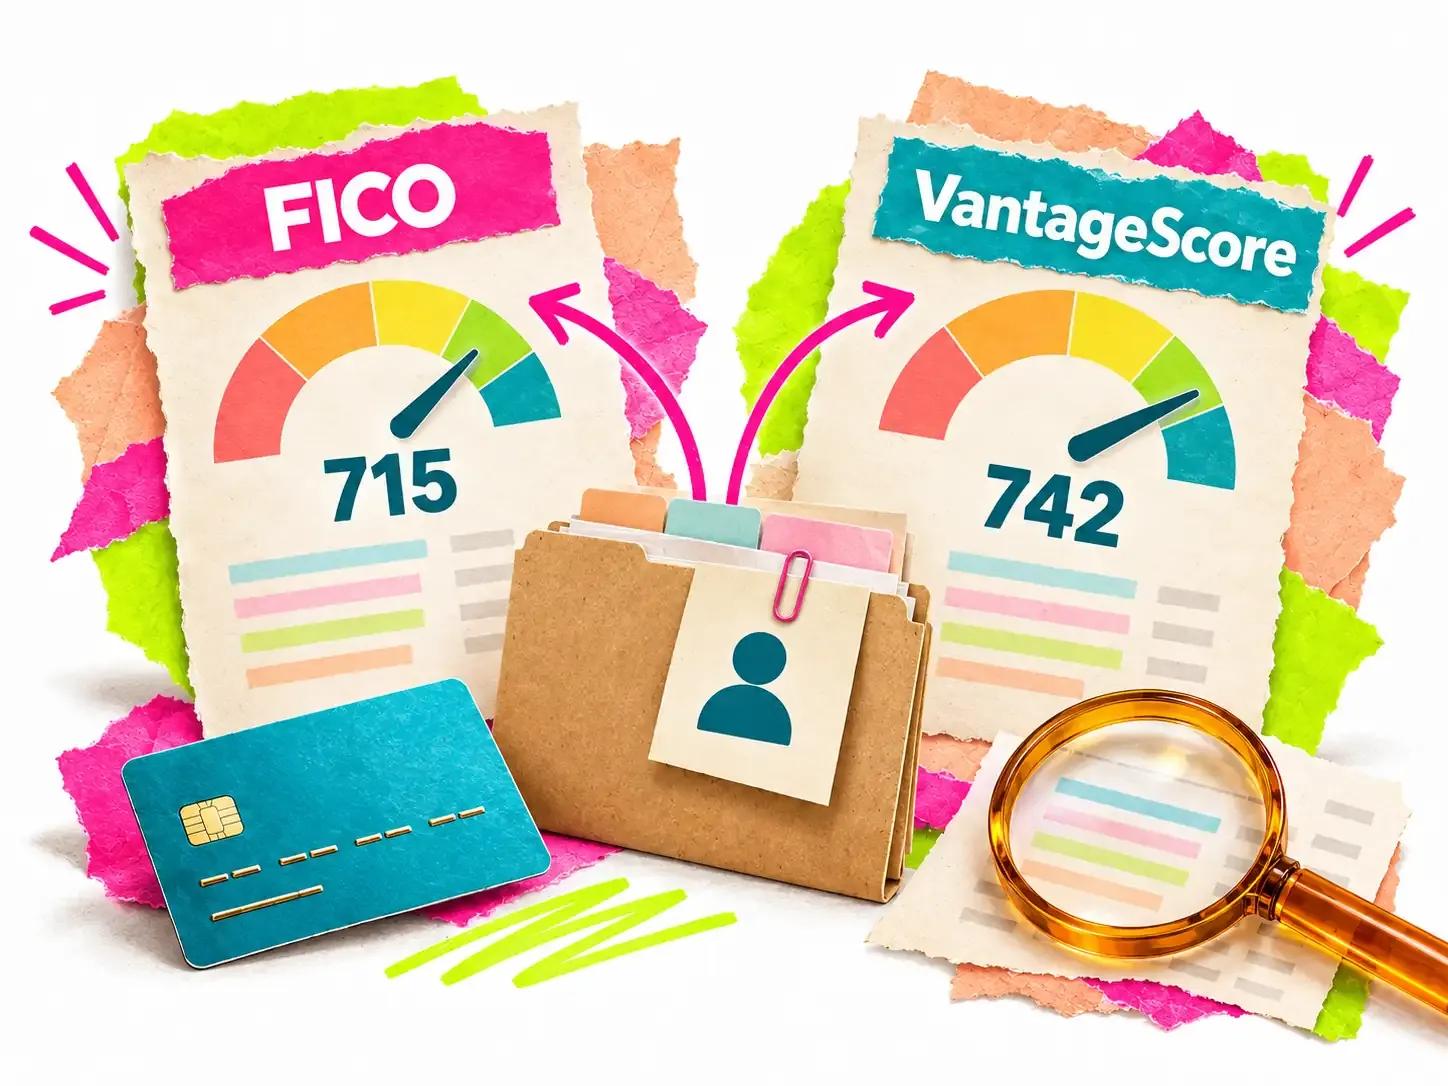
FICO and VantageScore can show different numbers for the same person because they use different models, bureau files, and update timing.
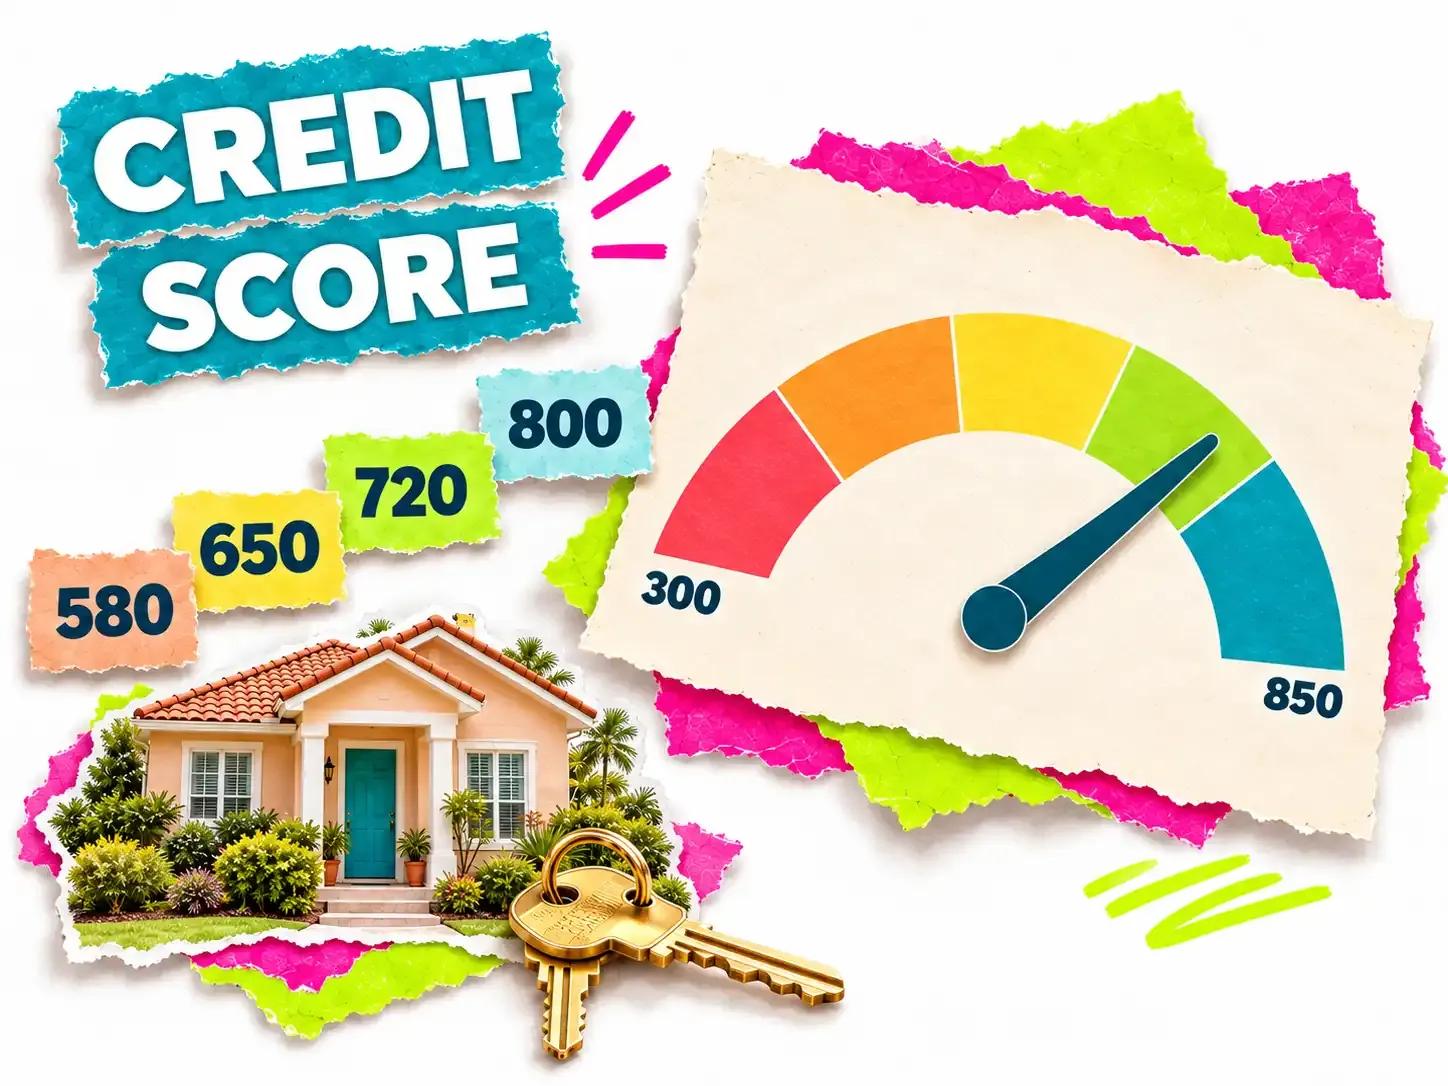
A practical guide to U.S. credit score ranges, including what 580, 650, 720, and 800 mean for mortgages, auto loans, credit cards, and rates.
We bridge the gap between your financial goals and premier lending services nationwide.
Bromoney is a financial marketplace, not a lender. Availability depends on the lender, the applicant's information, and where the applicant lives. When you submit a request form, your information is shared with lenders and partners in our marketplace so they can evaluate your request. Bromoney is operated by MONEY BROKER LLC (Delaware, DE File No. 10406065). This page is for general information and is not financial or legal advice.
You know the drill: one loan request, then waiting for the calls to start. Here you stay in control — we treat your information with care, you compare the options available to you, and you choose which lender or partner to move forward with. We can't speak for every partner, but we do our best to keep unwanted calls down.

Submitted over a secure connection


