

Age & Residency
You'll generally need to be at least 18 and live in the U.S. Lenders use that basic borrower information to start an eligibility review.

Power bill or a copay due before your paycheck lands in South Carolina? A payday loan covers a small gap, and you repay it in one payment on a date you agree on.
A payday loan in South Carolina bridges a few days between paychecks, so one small bill doesn't turn into a late fee or a shutoff notice. South Carolina law limits the amount, term and main deferred-presentment fee, restricts repeat borrowing and prohibits rollovers.
Checking available options with Bromoney does not require a credit-bureau inquiry and does not affect your credit score. If you select a partner and continue, that partner may perform a hard credit inquiry that can affect your score.
South Carolina caps the deferred-presentment fee at 15% of the principal amount, and that fee may be imposed only once for each agreement. A lender may also pass through up to one-half of the actual state-database verification cost, subject to the statutory limit.
In South Carolina, a payday lender can't ask you to pledge your car or anything else as security, and it can't require a friend or relative to co-sign or back the loan. The check you write is part of the deferred-presentment transaction.
In South Carolina, your agreement states the fee in dollars and as an APR and names the exact date the lender may deposit your check. A standard state disclosure form comes with every loan, so offers from different lenders read the same way.
The request may take a few minutes. Here's what most South Carolina lenders require before they can review your information and decide whether to offer credit.
You'll generally need to be at least 18 and live in the U.S. Lenders use that basic borrower information to start an eligibility review.
Your income can come from work or benefits, but it needs to be steady enough for the lender to see how you'll repay.
Most lenders ask for an active bank account so funds and repayment can move through a place you already use.
In South Carolina, a payday loan fits the small gaps: a power bill that jumps after a sweltering August, the county tax on your car that has to be paid before the registration can be renewed, or a new tire when your drive to work runs along I-26. It can cover a bill like that until your pay lands, so a lapsed tag or a reconnection fee doesn't make it bigger.
In South Carolina, a payday loan stops at a small sum and a single due date. If the cost is bigger, such as a used-car down payment or a repair that runs past a week's pay, an installment loan in South Carolina can spread it over several monthly payments instead.
On a $300 advance, the maximum deferred-presentment fee under South Carolina's 15% cap is $45, so principal plus that fee would total $345 on the due date. A small database-verification charge may also apply if permitted under state law. A $45 charge over 14 days corresponds to an APR of about 391% before considering any separately permitted database charge. Offers can come in lower. To see whether the payment fits next to your other bills, try the DTI and max loan calculator.
In South Carolina, each payday location needs its own Deferred Presentment license. Applications and license records are handled through NMLS under the supervision of the Consumer Finance Division, so you can look up a company on NMLS Consumer Access before you hand over a check or bank details.
When a bill is due before payday, one form on Bromoney saves you from typing the same details for lender after lender. If partners send offers to your account, you can see each one's dollar fee, amount and due date side by side and pick the one your next paycheck can cover. Whether to continue, and with whom, is your call, and Bromoney is free for you.
Estimate exactly how much you'll owe before you commit. Enter your loan amount and repayment term to see total costs, including fees and interest, laid out clearly.
Calculate my loanThese are protections South Carolina law gives payday borrowers, not terms any lender has offered.
If your check bounces
No returned-check fee
The lender can collect through civil means but can't add a returned-check charge, and writing the check can't make you criminally liable; your bank may still charge its own fee (S.C. Code § 34-39-180(G)).
Changed your mind
Cancel at no cost
You can rescind the transaction at no cost until the close of the next business day after entering into it (S.C. Code § 34-39-270).
Loans from several lenders
One open loan at a time
Every licensee checks the state's deferred presentment database before lending, so no lender can add a second loan while one is still open (S.C. Code §§ 34-39-175, 34-39-270).
State rules reviewed November 9, 2026. For the limits in effect, check with the South Carolina Consumer Finance Division.
If one due date feels too tight, an installment loan spreads the amount borrowed across fixed payments. You repay over a longer window, which can make budgeting easier, though the lender's terms still decide the real cost.
A credit union PAL or a personal loan can be a slower, lower-cost path when you have room to plan. You may need credit union membership for a PAL, while a personal loan usually leans harder on your credit profile.
Sometimes the better move is closer to home: state assistance, a local credit union, or a community program. Options change by state, so use your state page to see what may sit alongside payday loans.
Payday loans online work differently by state. What you can borrow, what a cash advance can cost, and how you repay may change under state laws. If you have bad credit or a tight bill gap, choose your state below to review legal loan amounts, terms, and the options available to you.
In South Carolina, a payday loan works as a deferred deposit: you write a personal check, the lender advances cash, and it agrees in writing to hold the check until a set date no more than 31 days later. On that date you pay the amount due, or the lender deposits the check.
Possibly. In South Carolina, each lender decides who qualifies and may weigh your income and checking account along with your score, though no outcome is promised. If your score keeps getting in the way, the bad credit loans guide walks through other routes.
In South Carolina, state law caps what a lender can advance to you at one time at $550, not counting the fee (S.C. Code § 34-39-180(B)). A lender may offer less than $550 based on its own eligibility and underwriting criteria. A budget stress test can help you compare the payment with the rest of your budget.
In South Carolina, how the advance reaches you is up to the lender, and timing may vary from one lender to another. A partner may ask you to confirm some details before it shows its terms.
South Carolina law requires the check used in a deferred-presentment transaction to be drawn on a legitimate, open and active account. Bromoney or a participating lender may separately request income, identity, employment or contact information when evaluating a request. The documents checklist shows documents a lender may ask you to keep ready.
In South Carolina, the deferred-presentment fee and other charges covered by the statutory cap generally can't exceed 15% of the amount advanced (S.C. Code § 34-39-180(E)). A lender may also pass through up to one-half of the actual database-verification cost as permitted by state law. Because a payday loan lasts only weeks, the 15% fee can translate into a much higher APR, the figure that shows the yearly cost. Lenders can price below the ceiling, so the dollar cost of actual offers can differ.
Ask the lender for an extended payment plan before the due date. South Carolina law provides this option once in a 12-month period with the licensee. The balance is split into at least four substantially equal installments with no additional interest or fees, and you can pay it off early without a penalty (S.C. Code § 34-39-280). Missing a plan installment counts as a default, so review the payment dates carefully before entering the plan.
No. A South Carolina licensee may not renew or extend the transaction beyond the agreed date, and the same licensee or an affiliate may not use the proceeds of another deferred-presentment transaction to repay the existing one (S.C. Code § 34-39-180(F)). After any payday transaction is repaid, another one cannot begin the same business day. If the next transaction would be your eighth or later in the calendar year, South Carolina requires an additional business-day gap (§ 34-39-270). Here's how installment and payday loans compare on cost.
No. In South Carolina, a payday loan is repaid in one payment within weeks, while an installment loan spreads repayment over scheduled installments and a longer term. For a bigger borrowing need, South Carolina personal loans are worth comparing too.
The South Carolina Board of Financial Institutions, Consumer Finance Division licenses and supervises deferred-presentment lenders. For consumer complaints involving payday loans, the Division directs borrowers to the South Carolina Department of Consumer Affairs. Use the lender's exact legal name and keep your agreement, disclosures and payment records when filing a complaint.
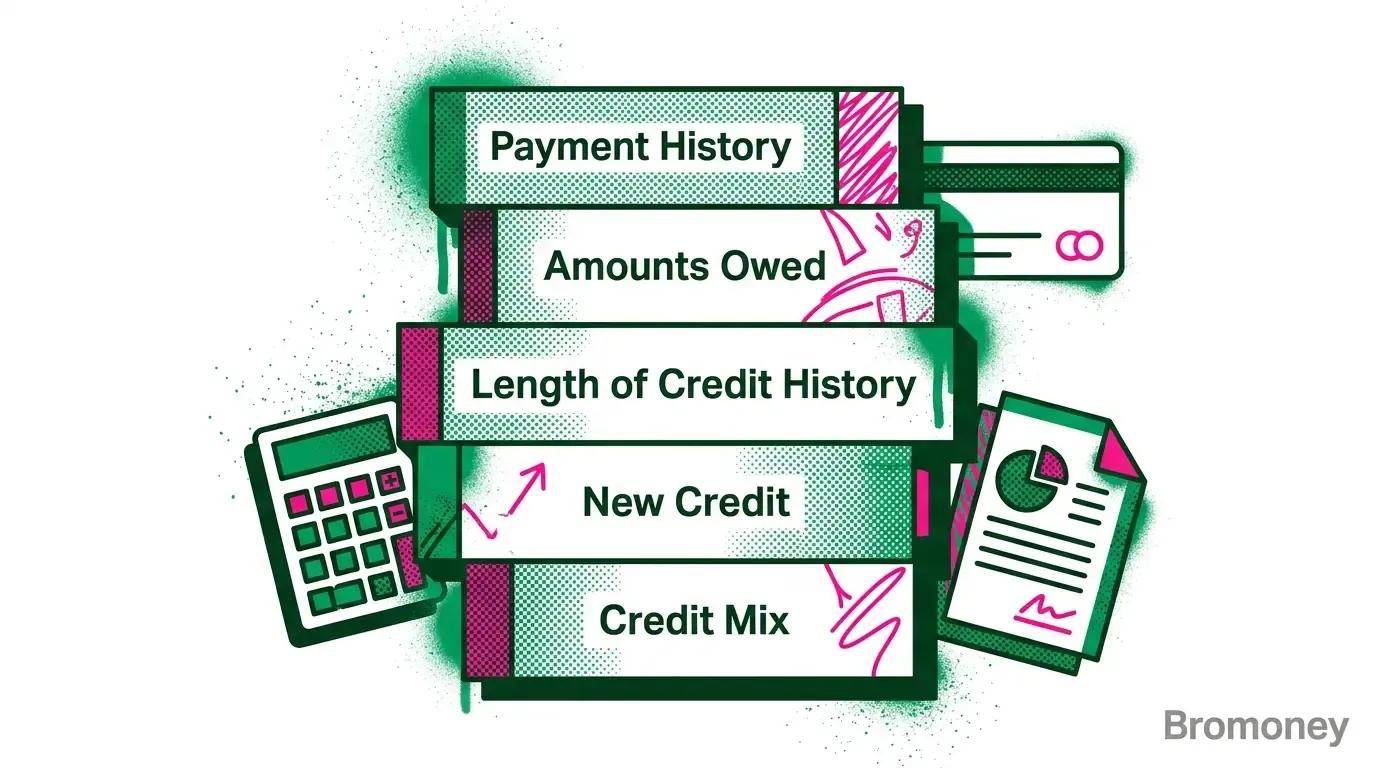
A practical breakdown of the five FICO Score factors, how each one works, and which actions improve your credit profile first.
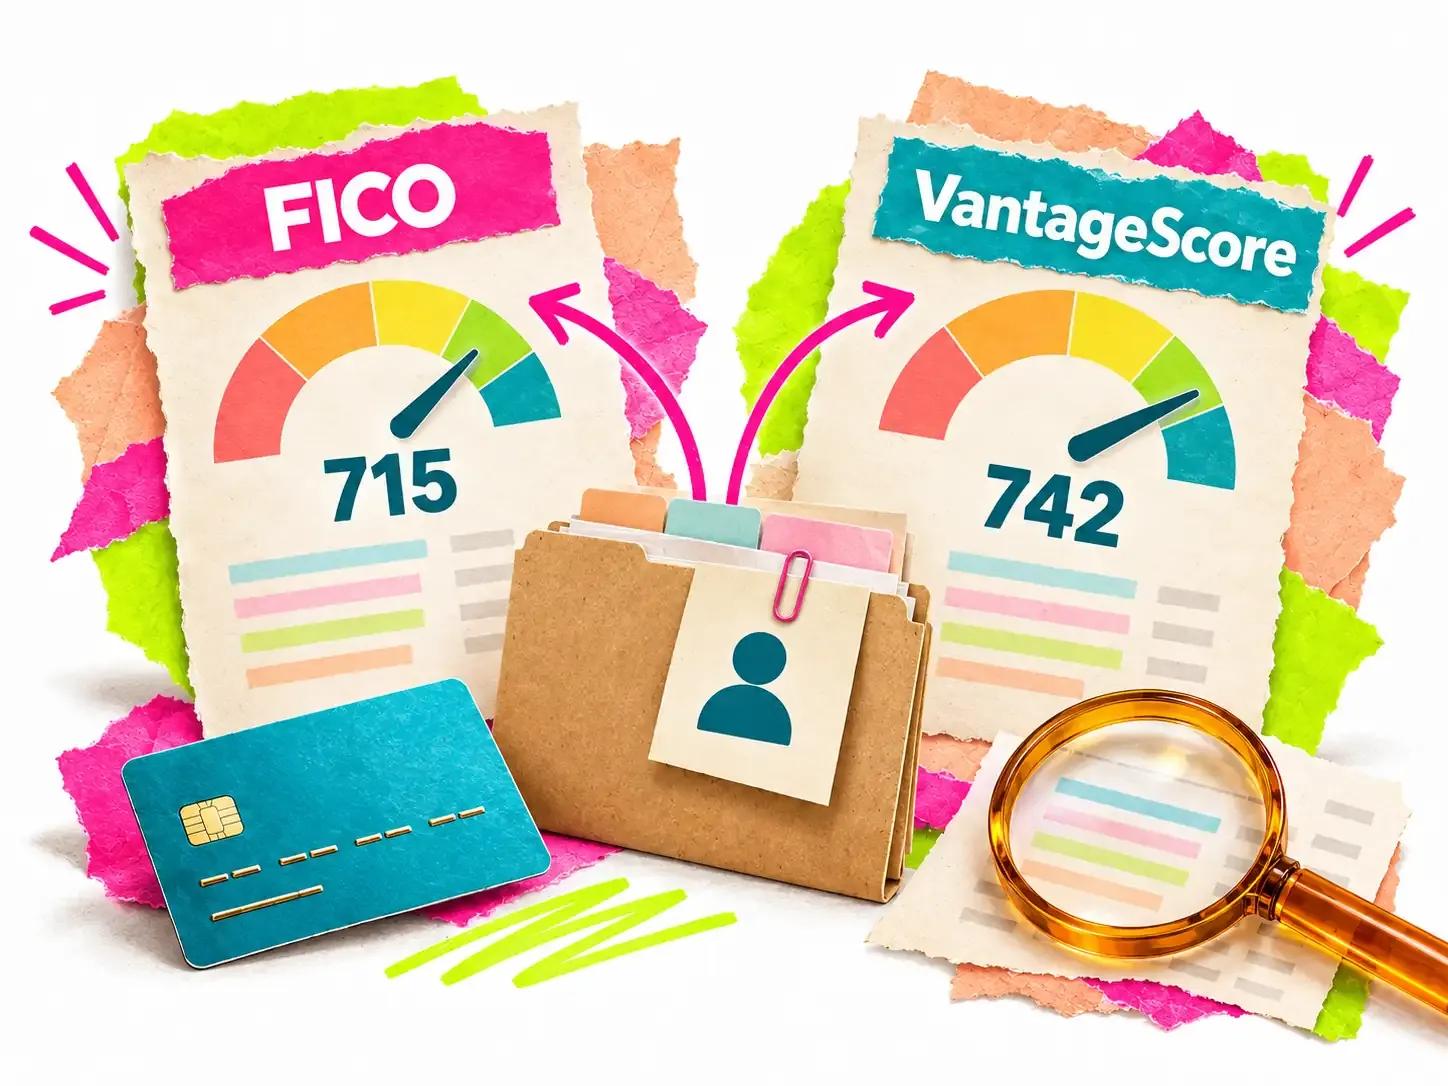
FICO and VantageScore can show different numbers for the same person because they use different models, bureau files, and update timing.
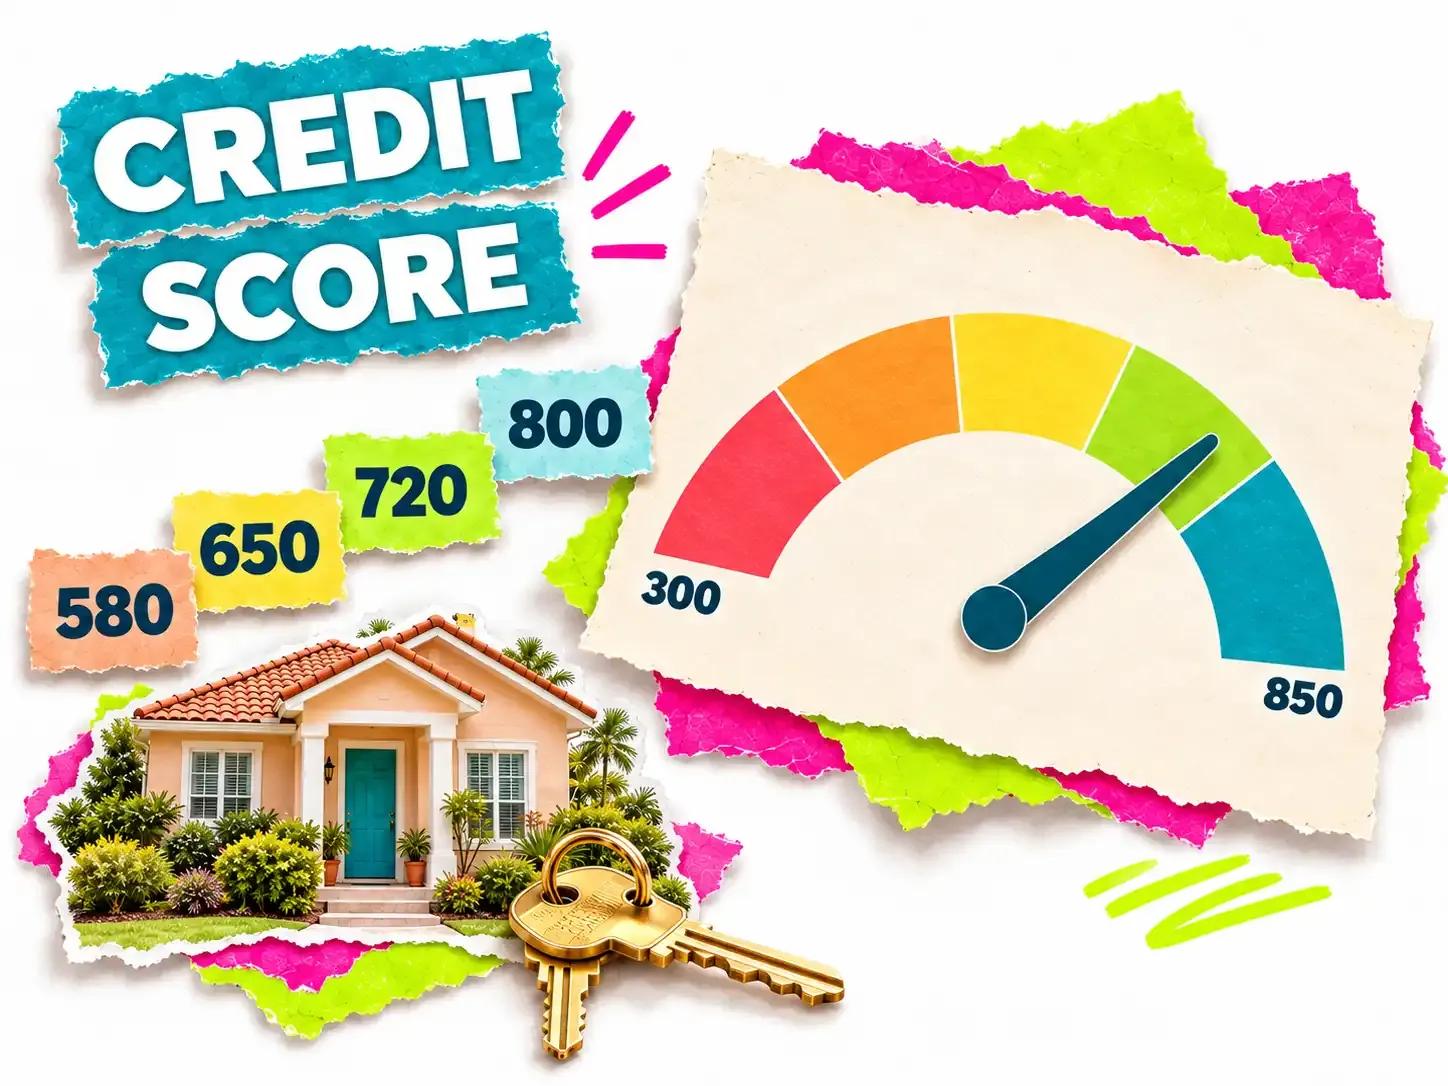
A practical guide to U.S. credit score ranges, including what 580, 650, 720, and 800 mean for mortgages, auto loans, credit cards, and rates.
We bridge the gap between your financial goals and premier lending services nationwide.
Bromoney is a financial marketplace, not a lender. Availability depends on the lender, the applicant's information, and where the applicant lives. When you submit a request form, your information is shared with lenders and partners in our marketplace so they can evaluate your request. Bromoney is operated by MONEY BROKER LLC (Delaware, DE File No. 10406065). This page is for general information and is not financial or legal advice.
You know the drill: one loan request, then waiting for the calls to start. Here you stay in control — we treat your information with care, you compare the options available to you, and you choose which lender or partner to move forward with. We can't speak for every partner, but we do our best to keep unwanted calls down.

Submitted over a secure connection


