

Age & Residency
You'll generally need to be at least 18 and live in the U.S. Lenders use that basic borrower information to start an eligibility review.

Short on cash a few days before payday in Kentucky? Payday loans in Kentucky can cover a small gap for a short time, within fee and size limits set by state law.
A payday-style loan in Kentucky is regulated as a deferred deposit transaction: a lender accepts a payment instrument and agrees to hold it for a period before deposit or presentment. Payday lending is permitted in Kentucky. As of July 2026, the total proceeds received from all open deferred deposit transactions may not exceed $600, and a customer may have no more than two open transactions at a time. The maximum service fee is $15 per $100 of the payment instrument's face amount, and a separate $3 state-database fee may also be charged to the customer. The $600 proceeds limit is subject to annual CPI-U adjustments under state law, may increase or decrease, is rounded up to the nearest $10, and may not exceed $850.
Checking available options with Bromoney does not require a credit-bureau inquiry and does not affect your credit score. If you select a partner and continue, that partner may perform a hard credit inquiry that can affect your score.
Kentucky caps the service fee at $15 per $100 of the payment instrument's face amount. The actual service fee may be lower. A separate $3 state-database fee may also be charged to the customer.
A Kentucky licensee or its affiliate may not charge a fee to renew, roll over or consolidate a deferred deposit transaction. The state also uses a database to track open transactions and enforce the limits on simultaneous borrowing.
Kentucky requires deferred-deposit lenders to provide the written disclosures required by federal consumer-credit law, including the APR and applicable finance-charge and payment information before you become obligated.
The request may take a few minutes. Here's what most Kentucky lenders require before they can review your information and decide whether to offer credit.
You'll generally need to be at least 18 and live in the U.S. Lenders use that basic borrower information to start an eligibility review.
Your income can come from work or benefits, but it needs to be steady enough for the lender to see how you'll repay.
Most lenders ask for an active bank account so funds and repayment can move through a place you already use.
Kentucky law limits the total proceeds a borrower may have outstanding, the number of open transactions and the service fee a lender may charge. The current proceeds limit is $600 across no more than two open transactions, while the maximum service fee is $15 per $100 of the payment instrument's face amount. A separate $3 state-database fee may also apply. Those limits are ceilings, not promises about what any lender will offer.
If you expect trouble repaying on the agreed date, contact the lender before the payment instrument is presented. Ask what lawful options are available and what each would cost in dollars. Kentucky prohibits a licensee or its affiliate from charging a fee simply to renew, roll over or consolidate the same deferred deposit transaction.
Payday lenders generally need a Kentucky deferred deposit license. The Kentucky Department of Financial Institutions regulates these companies and provides license information through NMLS. Look up the exact legal company name before you proceed and keep your agreement and disclosures in case you need to file a complaint.
Kentucky borrowers can fill out one form on Bromoney instead of typing the same details into site after site. If partners send offers, you'll see them side by side in your account, with the payment, term and total in view. Whether to continue, and with which lender, is your call. Using Bromoney costs you nothing.
Estimate exactly how much you'll owe before you commit. Enter your loan amount and repayment term to see total costs, including fees and interest, laid out clearly.
Calculate my loanThe figures below come from state law, not from any lender's offer. For the limit in force today, check with the Kentucky Department of Financial Institutions.
Status
Permitted, fee-capped
Legal in Kentucky with a statutory service-fee limit.
Open-loan proceeds cap
$600 total
The total proceeds received from all open deferred deposit transactions may not exceed $600. A customer may have no more than two open transactions at a time.
Service-fee limit
$15 per $100 of payment instrument
Calculated on the face amount of the payment instrument. The actual service fee may be lower.
Database fee
$3 per transaction
The commissioner imposes a $3 database fee for each deferred deposit transaction, and the licensee may charge that fee to the customer.
Term
14-day minimum fee period; up to 60 days
The statutory service fee applies to a period of at least 14 days, and a licensee may not agree to hold the transaction for more than 60 days.
Fee-based rollovers
Prohibited
A licensee or affiliate may not charge a fee to renew, roll over or consolidate a deferred deposit transaction.
Loan limit
Maximum 2 open transactions
The combined proceeds of all open transactions may not exceed the current state limit. Open transactions are tracked through a state database.
Returned check
Actual financial-institution charge
A licensee may pass through a check-collection charge actually imposed by a financial institution if the conditions for the charge were disclosed in writing in advance.
Military
36% MAPR
Federal Military Lending Act limit for covered active-duty servicemembers and covered dependents.
State rules reviewed November 2026. For current limits, check with the Kentucky Department of Financial Institutions, Division of Non-Depository Institutions.
If one due date feels too tight, an installment loan spreads the amount borrowed across fixed payments. You repay over a longer window, which can make budgeting easier, though the lender's terms still decide the real cost.
A credit union PAL or a personal loan can be a slower, lower-cost path when you have room to plan. You may need credit union membership for a PAL, while a personal loan usually leans harder on your credit profile.
Sometimes the better move is closer to home: state assistance, a local credit union, or a community program. Options change by state, so use your state page to see what may sit alongside payday loans.
Payday loans online work differently by state. What you can borrow, what a cash advance can cost, and how you repay may change under state laws. If you have bad credit or a tight bill gap, choose your state below to review legal loan amounts, terms, and the options available to you.
Yes. Kentucky permits deferred deposit transactions subject to state limits. As of July 2026, the total proceeds from all open transactions may not exceed $600, a customer may have no more than two open transactions at a time, and the maximum service fee is $15 per $100 of the payment instrument's face amount. A separate $3 state-database fee may also apply. The payday loans guide explains how these loans work.
As of July 2026, the total proceeds you receive from all open deferred deposit transactions in Kentucky may not exceed $600, and you may have no more than two open transactions at a time. The statutory proceeds limit is subject to annual CPI-U adjustments and may not exceed $850.
Kentucky caps the service fee at $15 per $100 of the payment instrument's face amount. The service fee may be lower, but it may not exceed that statutory limit. A separate $3 state-database fee may also be charged to the customer. Compare the dollar service fee, database fee and APR disclosed in any actual option available to you.
Kentucky's statutory service-fee structure applies to a period of at least 14 days, and a licensee may not agree to hold a deferred deposit transaction for more than 60 days. The statutory maximum service fee does not increase simply because the transaction lasts longer. The actual fee may be lower than the statutory maximum, so compare the dollar fee and APR in the lender's disclosure. If a single due date feels tight, installment loans use a different repayment structure.
Kentucky prohibits a licensee or its affiliate from charging a fee to renew, roll over or consolidate a deferred deposit transaction. That prevents a lender from repeatedly charging a new payday fee simply to push the same obligation forward. See how installment and payday loans compare.
Kentucky permits no more than two open deferred deposit transactions at a time. The total proceeds received from all open transactions also may not exceed the current statutory limit, which is $600 as of July 2026. Lenders use the state database to check open transactions before entering into another one.
A Kentucky licensee may pass through a check-collection charge actually imposed by a financial institution for a returned or dishonored payment instrument if the conditions for that charge were disclosed in writing in advance. Your own bank or payment provider may separately impose its own charge.
Kentucky does not set a statutory rescission window for this product. Some lenders may offer their own cancellation terms; if that matters to you, review the agreement and ask about any cancellation policy before becoming obligated.
It may be possible, but the decision belongs to the lender. Kentucky's deferred-deposit statutes do not establish a specific credit-score threshold. The statutory fee and transaction limits apply regardless of your score. If your credit score is the main concern, the bad credit loans guide explains common credit-score tiers.
The Kentucky Department of Financial Institutions, Division of Non-Depository Institutions licenses deferred deposit companies and handles consumer complaints. Use the exact legal company name shown in your agreement when checking a license or filing a complaint, and keep copies of the agreement, disclosures and payment records.
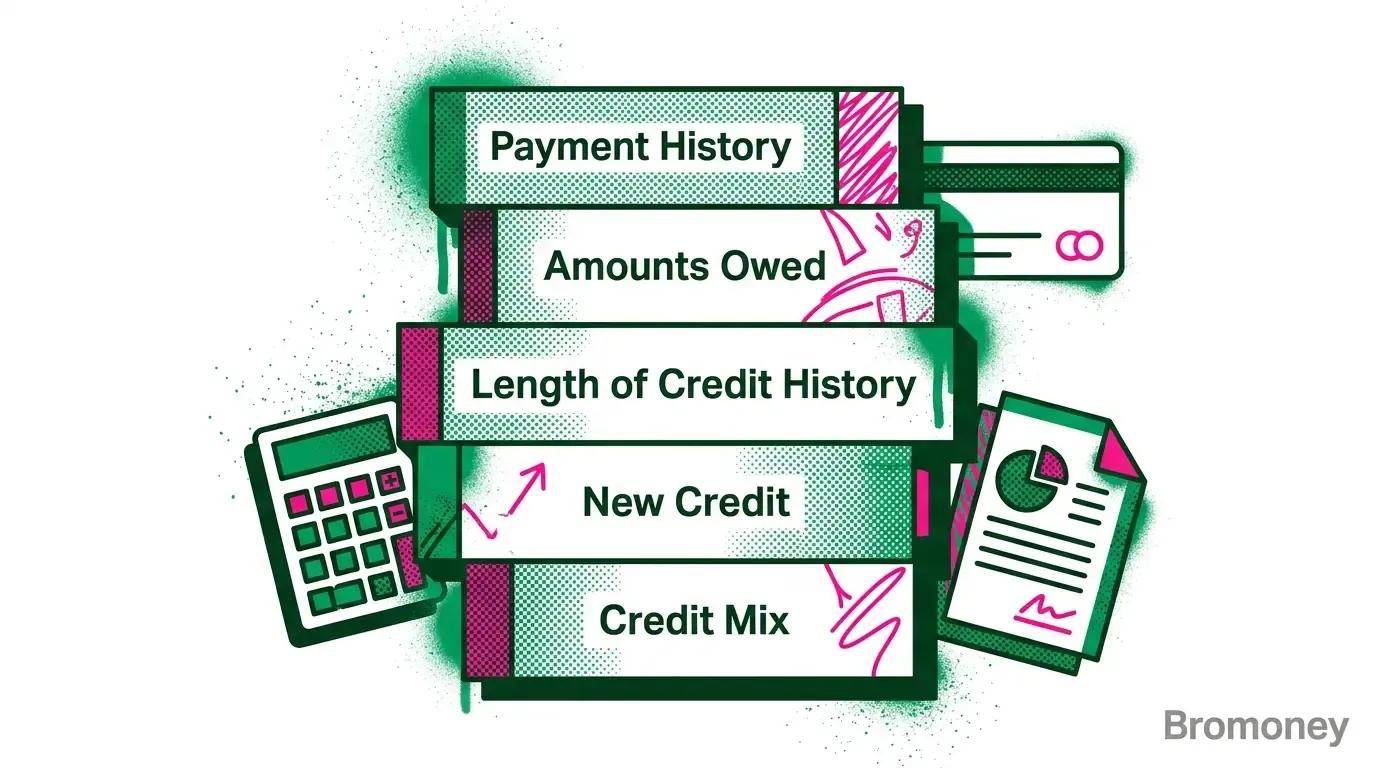
A practical breakdown of the five FICO Score factors, how each one works, and which actions improve your credit profile first.
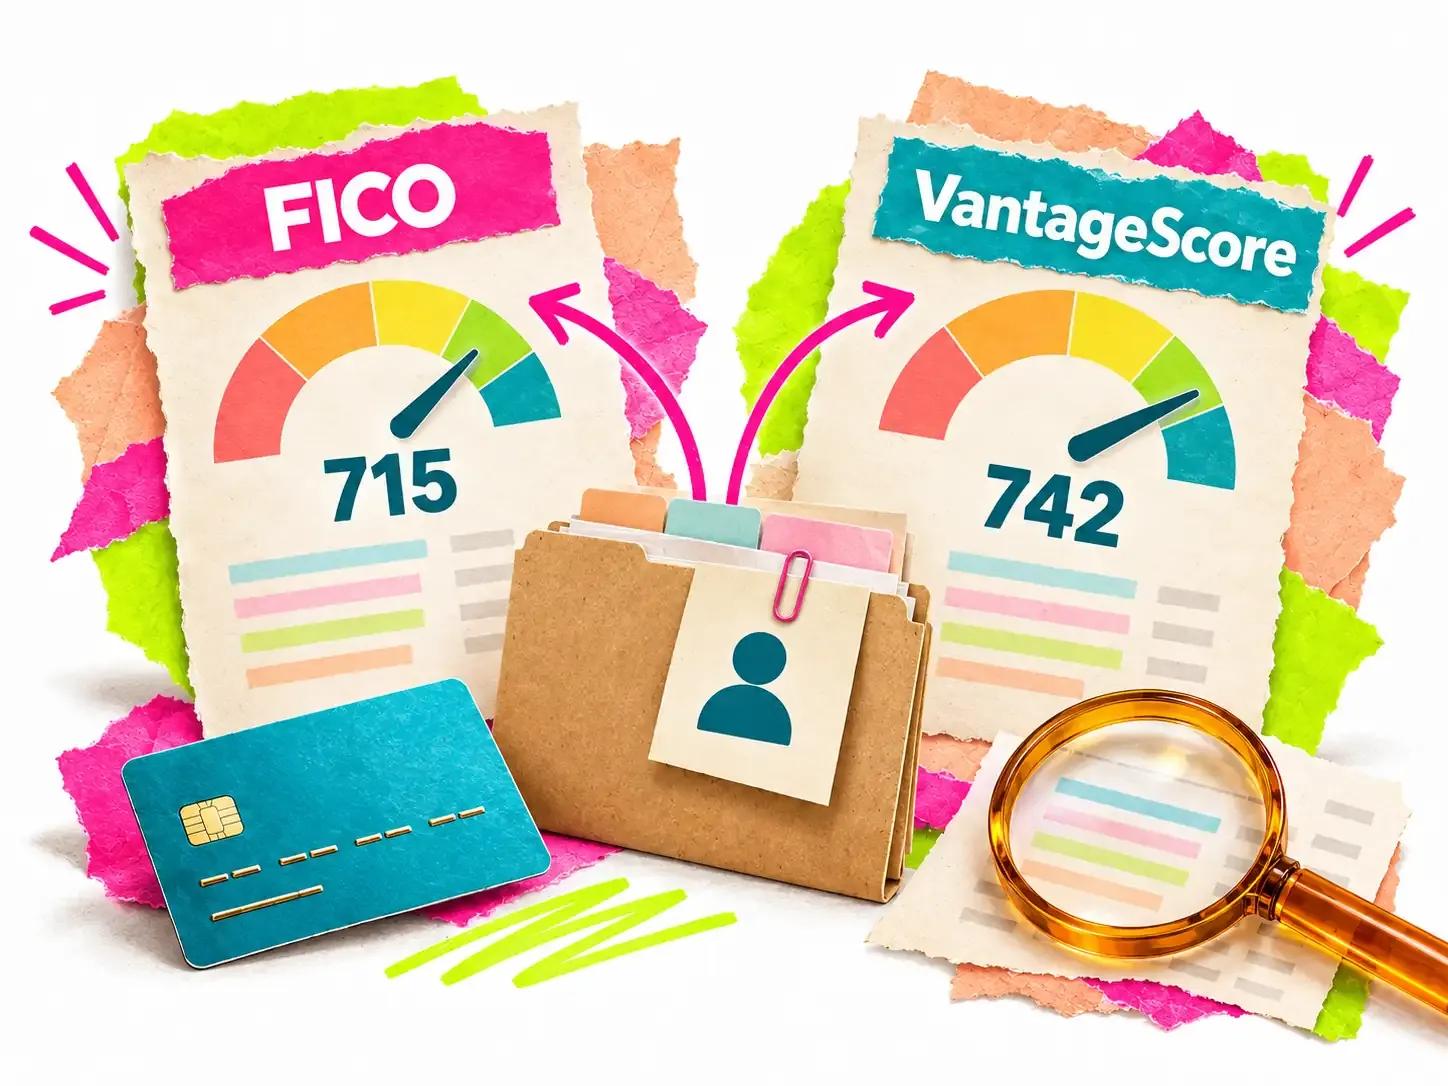
FICO and VantageScore can show different numbers for the same person because they use different models, bureau files, and update timing.
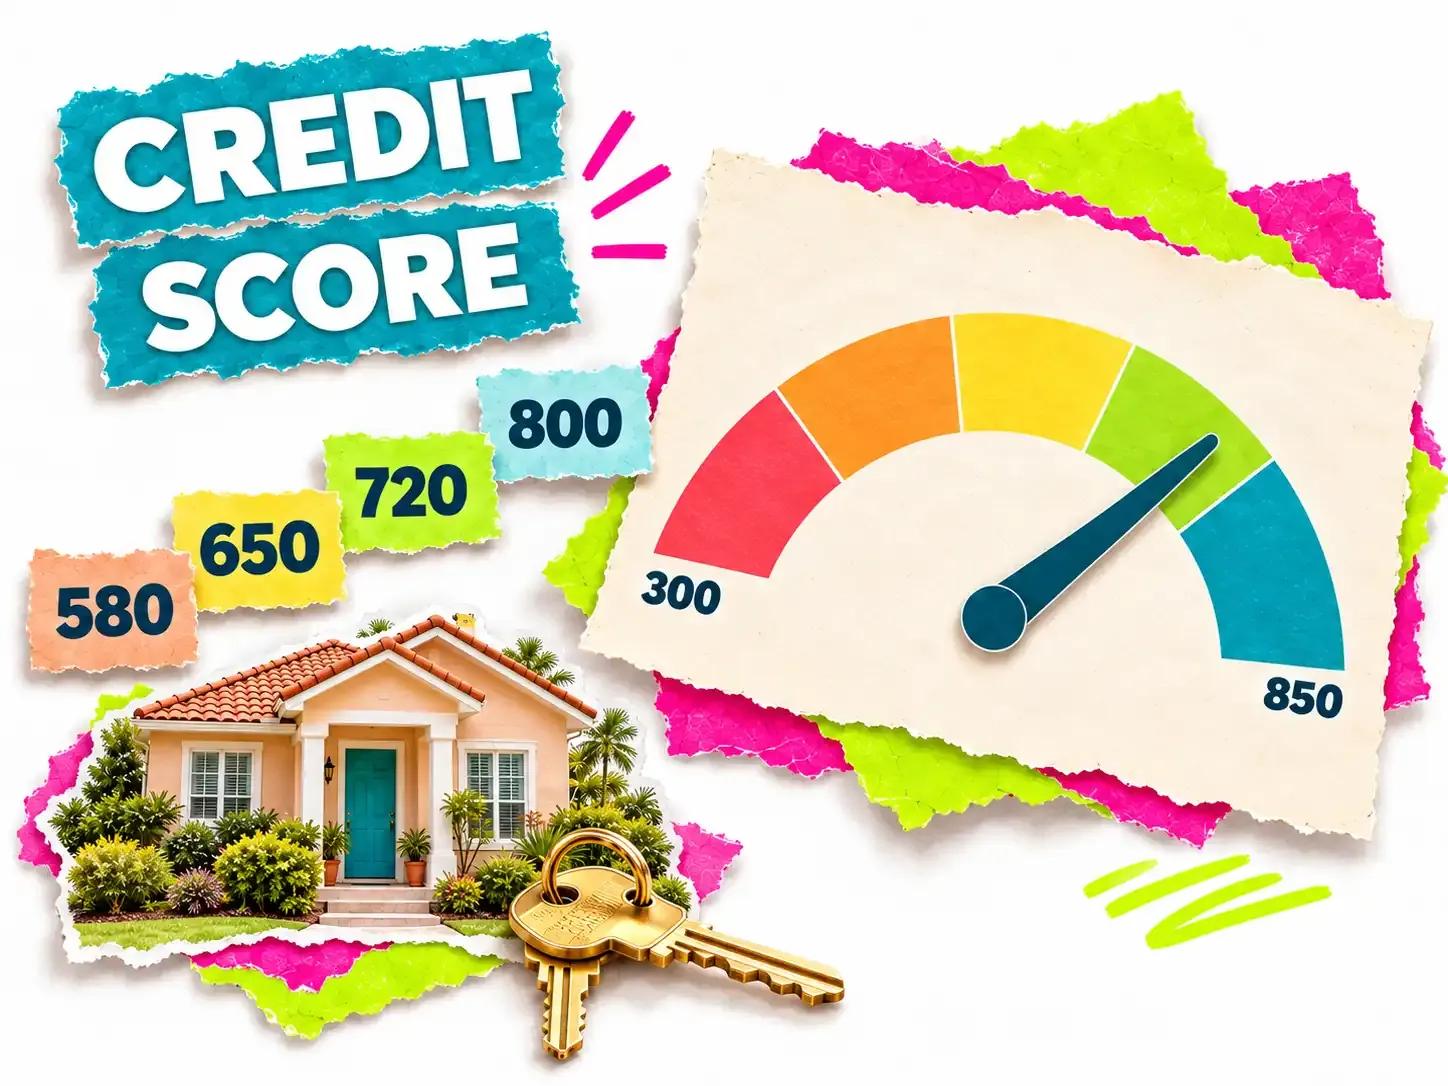
A practical guide to U.S. credit score ranges, including what 580, 650, 720, and 800 mean for mortgages, auto loans, credit cards, and rates.
We bridge the gap between your financial goals and premier lending services nationwide.
Bromoney is a financial marketplace, not a lender. Availability depends on the lender, the applicant's information, and where the applicant lives. When you submit a request form, your information is shared with lenders and partners in our marketplace so they can evaluate your request. Bromoney is operated by MONEY BROKER LLC (Delaware, DE File No. 10406065). State rules reviewed November 2026. This page is for general information and is not financial or legal advice.
You know the drill: one loan request, then waiting for the calls to start. Here you stay in control — we treat your information with care, you compare the options available to you, and you choose which lender or partner to move forward with. We can't speak for every partner, but we do our best to keep unwanted calls down.

Submitted over a secure connection


