

Age & Residency
You'll generally need to be at least 18 and live in the U.S. Lenders use that basic borrower information to start an eligibility review.

Short on cash before payday in Delaware? Payday loans in Delaware let you borrow a small amount and pay it back on a short schedule.
A payday-style loan in Delaware falls under the state's rules for short-term consumer loans: loans of $1,000 or less that charge interest or fees, have a stated repayment period of less than 60 days, and are not secured by a motor-vehicle title. Delaware does not impose a general statutory APR cap on these loans, so the lender must disclose the applicable APR, finance charge and payment terms before you become obligated. A lender may roll over the same short-term consumer loan no more than four times. But each rollover or refinancing also counts as a short-term consumer loan toward Delaware's separate limit of five such loans from all licensees in any 12-month period. A statewide database is used to determine whether a borrower is eligible for another transaction.
Checking available options with Bromoney does not require a credit-bureau inquiry and does not affect your credit score. If you select a partner and continue, that partner may perform a hard credit inquiry that can affect your score.
Delaware does not impose a general statutory APR cap on licensed short-term consumer loans. The lender sets the loan's interest and permitted charges under the agreement, so compare the disclosed APR and finance charge before you borrow.
A Delaware licensee may roll over the same short-term consumer loan no more than four times. Each rollover or refinancing also counts toward the statewide limit of five short-term consumer-loan transactions from all licensees in any 12-month period.
Federal Truth in Lending rules require covered closed-end loans to disclose the APR and finance charge, along with the applicable payment terms, before you become obligated. Use those figures to compare what borrowing will actually cost.
The request may take a few minutes. Here's what most Delaware lenders require before they can review your information and decide whether to offer credit.
You'll generally need to be at least 18 and live in the U.S. Lenders use that basic borrower information to start an eligibility review.
Your income can come from work or benefits, but it needs to be steady enough for the lender to see how you'll repay.
Most lenders ask for an active bank account so funds and repayment can move through a place you already use.
Delaware's short-term consumer-loan rules apply to qualifying loans of up to $1,000 with a stated repayment period of less than 60 days. Those are ceilings, not promises. No lender has to offer you the full $1,000 or the longest permitted term. Read the amount, due date, APR and finance charge in the actual agreement before you continue.
If you cannot repay as scheduled, contact the lender before the due date and ask what lawful options are available. Delaware law provides for workout agreements after the permitted rollover cycle. A statutory workout agreement must spread repayment over equal installments for at least 90 days, and the lender may not add another fee or interest charge because the debt was converted to the workout plan.
Non-depository businesses engaged in payday or other consumer lending in Delaware generally need a Licensed Lender license from the Office of the State Bank Commissioner, subject to statutory exemptions. Check the exact legal company name before you borrow and keep the signed disclosures and agreement in case you need to file a complaint.
Delaware borrowers fill out one form on Bromoney instead of typing the same details for every lender. If partners send offers, you'll see them side by side in your account. Compare the payment, the term and the total cost, and pick what fits your budget. Whether to continue, and with which partner, is your call. Using Bromoney costs you nothing.
Estimate exactly how much you'll owe before you commit. Enter your loan amount and repayment term to see total costs, including fees and interest, laid out clearly.
Calculate my loanThe figures below come from state law, not from any lender's offer. For current requirements, check with the Office of the State Bank Commissioner.
Status
Permitted; no general APR cap
Delaware permits licensed short-term consumer loans but does not impose a general statutory APR cap on them.
Largest loan
$1,000
Delaware's short-term consumer-loan rules apply to qualifying loans of $1,000 or less.
General interest/APR cap
None
The loan agreement sets the interest and pricing, subject to applicable disclosure requirements and specific limits on certain charges.
Term
Less than 60 days
Delaware defines a short-term consumer loan as having a stated repayment period of less than 60 days.
Rollovers
Up to 4
Each rollover or refinancing also counts as a separate short-term consumer loan toward the statewide 12-month transaction limit.
Loan limit
5 transactions per 12 months
Rollovers and refinancings count toward this five-transaction limit. Eligibility is tracked across licensees through Delaware's short-term-loan database.
Rescission
Until next business day's close
A borrower may return the full amount borrowed by the close of business on the business day after funds were disbursed or advanced, without a fee or other charge.
Military
36% MAPR
Federal Military Lending Act limit for covered active-duty servicemembers and covered dependents.
State rules reviewed November 2026. For current requirements, check with the Office of the State Bank Commissioner.
If one due date feels too tight, an installment loan spreads the amount borrowed across fixed payments. You repay over a longer window, which can make budgeting easier, though the lender's terms still decide the real cost.
A credit union PAL or a personal loan can be a slower, lower-cost path when you have room to plan. You may need credit union membership for a PAL, while a personal loan usually leans harder on your credit profile.
Sometimes the better move is closer to home: state assistance, a local credit union, or a community program. Options change by state, so use your state page to see what may sit alongside payday loans.
Payday loans online work differently by state. What you can borrow, what a cash advance can cost, and how you repay may change under state laws. If you have bad credit or a tight bill gap, choose your state below to review legal loan amounts, terms, and the options available to you.
Lenders in Delaware often prioritize factors like your income, employment, and active checking account over your credit score alone. A FICO score below 580 isn't an automatic disqualification, as they also consider your debt-to-income ratio. Using a pre-qualification tool can help you see options without a hard credit inquiry.
Yes. Delaware permits qualifying short-term consumer loans of up to $1,000 with a stated repayment period of less than 60 days. Delaware does not impose a general statutory APR cap on these loans. The payday loans guide explains how payday-style borrowing works.
Most Delaware lenders require: proof of being 18 or older with a valid ID; a verifiable source of recurring income; an active checking account in your name; and a valid Social Security Number or ITIN. Some may also request a recent pay stub or bank statement.
Delaware's short-term consumer-loan rules cover qualifying loans of $1,000 or less. The amount actually available to you depends on the lender and your information.
Delaware does not impose a general statutory APR cap on licensed short-term consumer loans. The interest rate and permitted charges are governed by the loan agreement and applicable state rules, so review the APR, finance charge and any separately disclosed charges before you agree.
Yes. A company that originates a payday loan or other short-term consumer loan in Delaware must hold the appropriate license from the Delaware Office of the State Bank Commissioner. A borrower may reach a lender directly or through a marketplace or connection service. The marketplace itself is not necessarily the company that originates, approves, or funds the loan. Before accepting an offer, verify the actual lender’s license and review the lender’s disclosures, including the APR, finance charge, fees, payment schedule, and total amount due.
A Delaware short-term consumer loan has a stated repayment period of less than 60 days. The exact due date is set in the agreement. If a single-payment structure does not fit your budget, installment loans use a different repayment structure with scheduled installments over time.
Yes, but with important limits. A Delaware licensee may roll over the same short-term consumer loan no more than four times. Each rollover or refinancing also counts as a separate short-term consumer loan toward the statewide limit of five transactions from all licensees in any 12-month period. After the permitted rollover cycle, a borrower may be eligible for a workout agreement or the lender may use other lawful collection options. A statutory workout agreement must spread repayment over equal installments for at least 90 days, and the lender may not add another fee or interest charge because the debt was converted to the workout plan. See how installment and payday loans compare.
Delaware limits a borrower to five short-term consumer-loan transactions from all licensees in any 12-month period. Rollovers and refinancings count toward that five-transaction limit. Lenders use a statewide database to determine whether another transaction is permitted.
If your agreement provides for it, a Delaware licensed lender may charge a returned-check or denied-electronic-debit fee in the amount stated in the agreement. Only one such lender charge may be assessed per returned item. Your bank or payment provider may separately impose its own fee.
Yes. Delaware requires short-term consumer loans to include a right of rescission. You may return the amount borrowed in full by the close of business on the business day following the day the funds were disbursed or advanced, without incurring a fee or other charge.
It may be possible, but the decision belongs to the lender. Delaware's short-term consumer-loan rules do not establish a specific credit-score threshold for borrowers. Compare the APR, finance charge, payment terms and other disclosed charges in any actual option available to you. If your credit score is the main concern, the bad credit loans guide explains how common credit-score tiers are used.
The Office of the State Bank Commissioner regulates covered non-depository lenders and handles consumer complaints. Businesses required to hold a Delaware lending license can be checked using the exact legal company name shown in the loan documents. Banking organizations, federal credit unions and certain other entities may be subject to different regulatory frameworks or statutory exemptions.
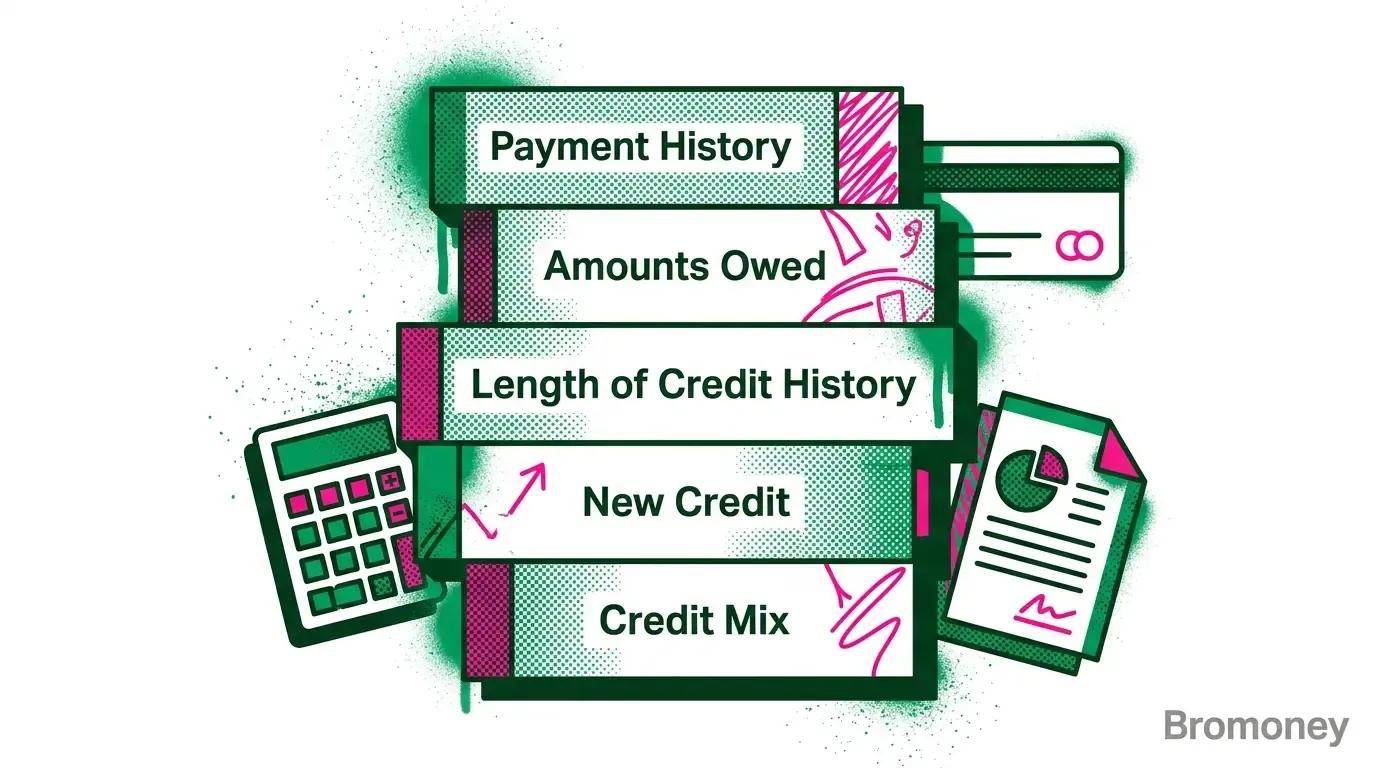
A practical breakdown of the five FICO Score factors, how each one works, and which actions improve your credit profile first.
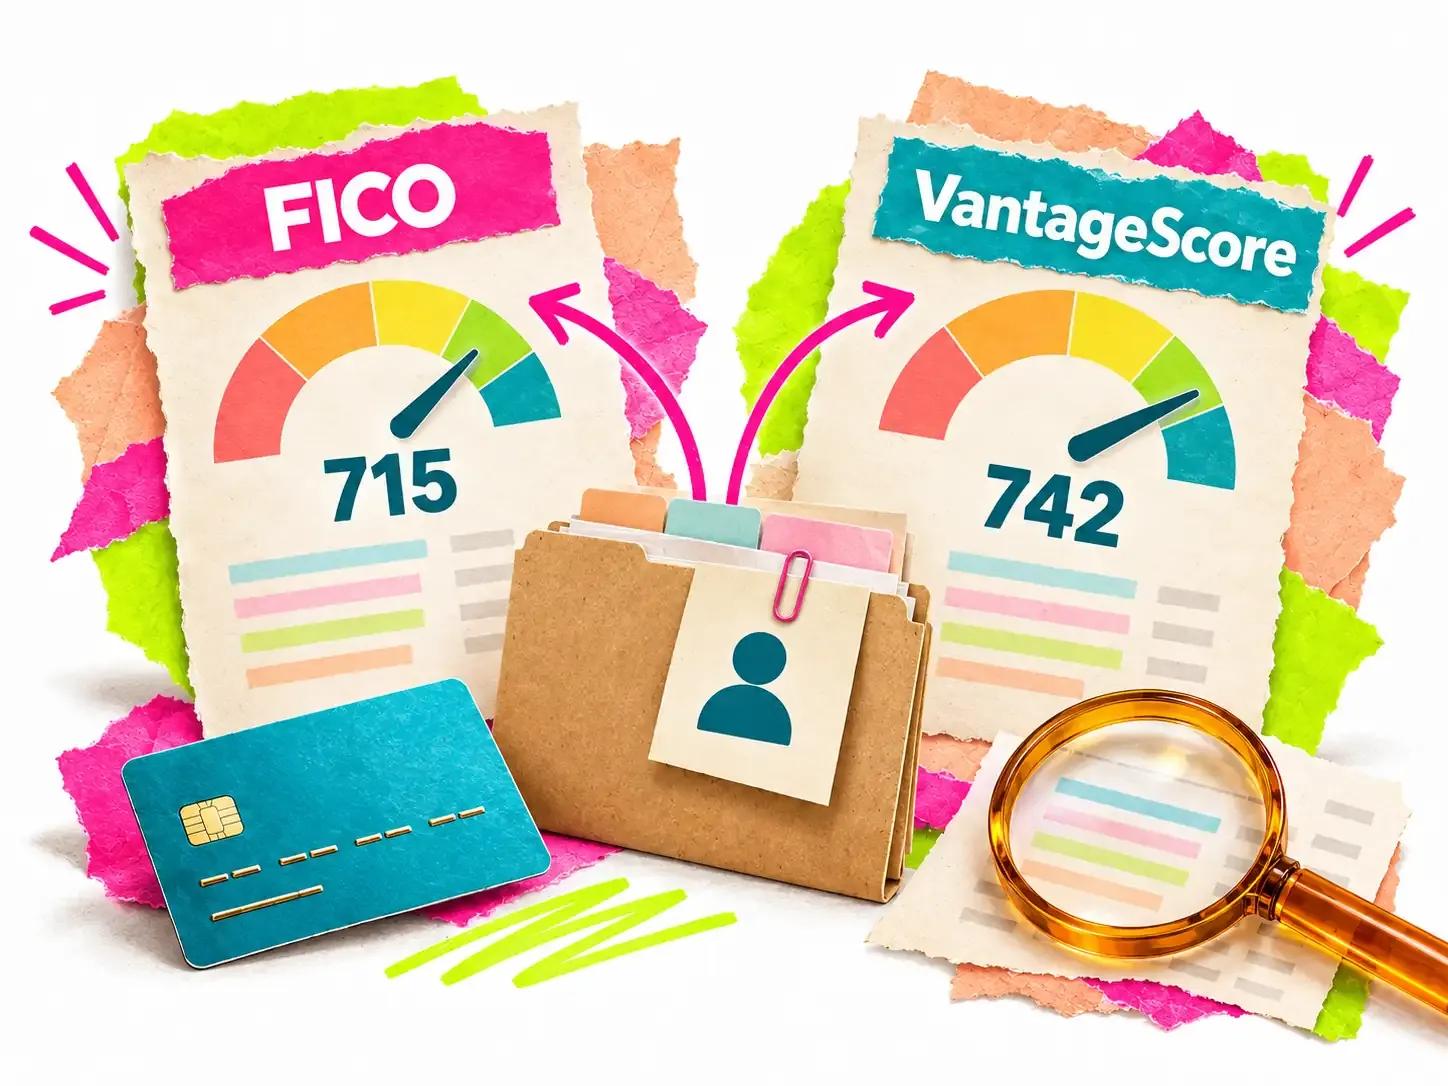
FICO and VantageScore can show different numbers for the same person because they use different models, bureau files, and update timing.
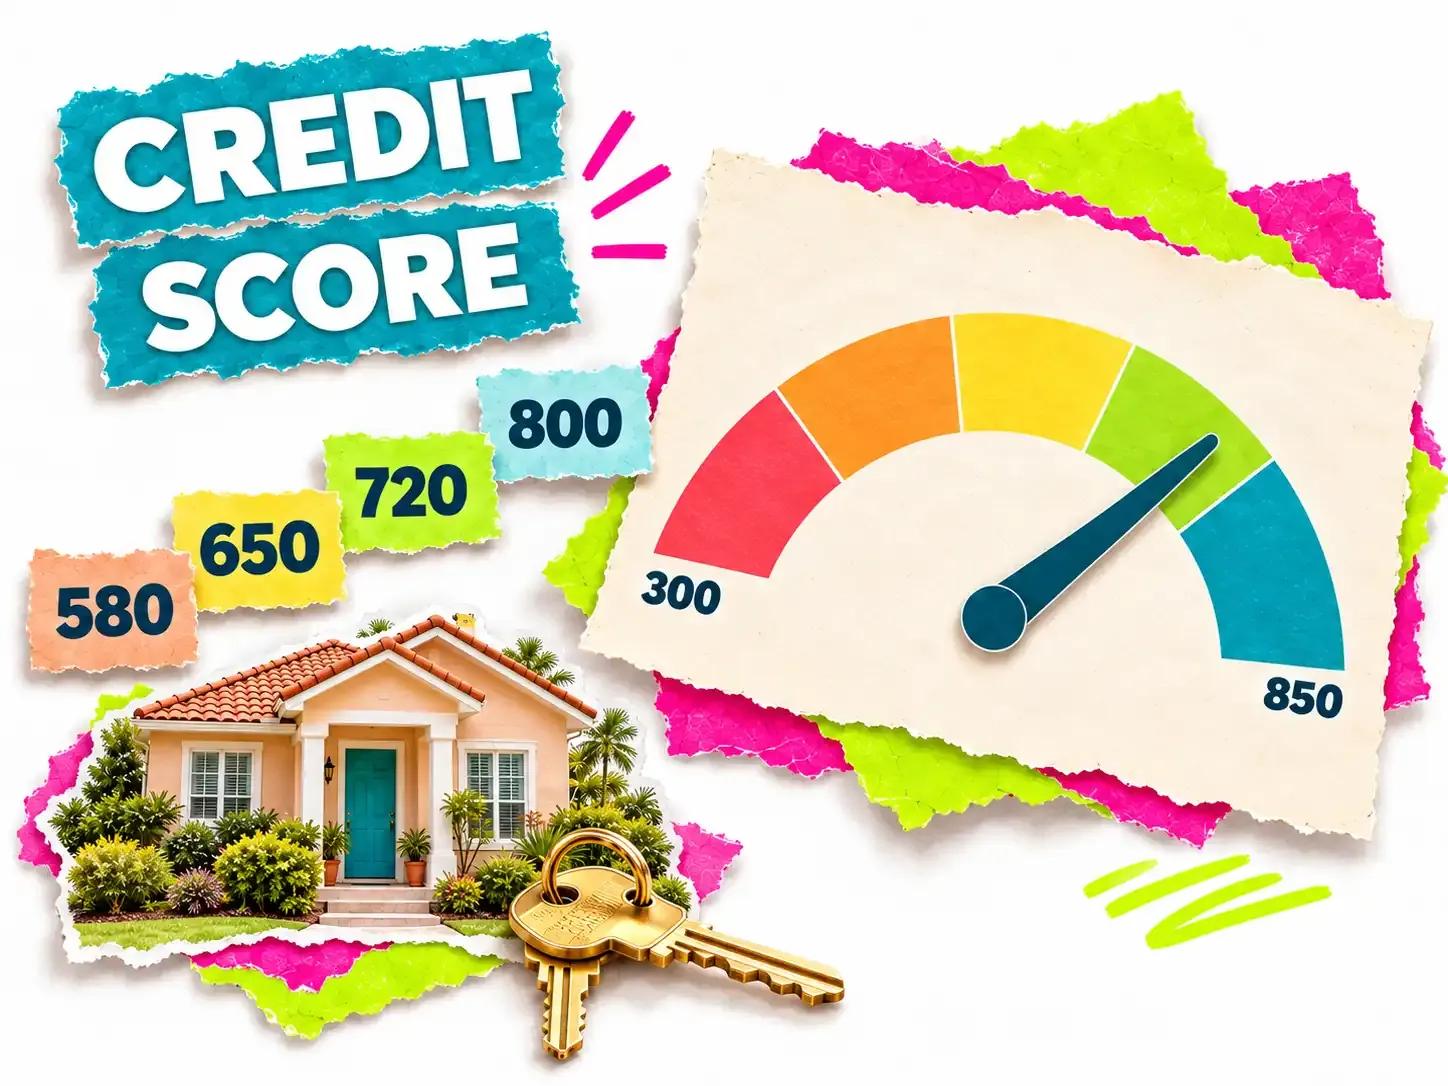
A practical guide to U.S. credit score ranges, including what 580, 650, 720, and 800 mean for mortgages, auto loans, credit cards, and rates.
We bridge the gap between your financial goals and premier lending services nationwide.
Bromoney is a financial marketplace, not a lender. Availability depends on the lender, the applicant's information, and where the applicant lives. When you submit a request form, your information is shared with lenders and partners in our marketplace so they can evaluate your request. Bromoney is operated by MONEY BROKER LLC (Delaware, DE File No. 10406065). State rules reviewed November 2026. This page is for general information and is not financial or legal advice.
You know the drill: one loan request, then waiting for the calls to start. Here you stay in control — we treat your information with care, you compare the options available to you, and you choose which lender or partner to move forward with. We can't speak for every partner, but we do our best to keep unwanted calls down.

Submitted over a secure connection


