

Identity and Residency
Lenders typically ask that you're 18 or older, live in the U.S. and can show a government-issued ID and a Social Security number, so they can confirm who you are. Some lenders accept an ITIN instead.

Paying off pricey cards, a big home project or a large bill in South Dakota? A personal loan puts one larger sum in your hands, so you can take care of it at once.
A personal loan in South Dakota gives you a larger sum up front, repaid in fixed monthly payments over a term you settle with the lender. South Dakota law is on your side: a state-licensed money lender generally may not impose finance charges above a 36% annual rate, regardless of the loan amount.
Checking available options with Bromoney does not require a credit-bureau inquiry and does not affect your credit score. If you select a partner and continue, that partner may perform a hard credit inquiry that can affect your score.
In South Dakota, the money from a personal loan isn't locked to a single item the way a car loan or store financing is, so one amount can cover a repair, a move and a deposit together. The lender decides how much to offer and may ask what the funds are for.
In South Dakota, rolling several card balances into a personal loan can replace multiple minimum payments and due dates with one installment payment and a defined repayment schedule. When consolidating card balances, compare the new APR, repayment term, fees and total of payments with the cost of keeping the existing debts. A lower APR can help, but a longer term may still increase the total cost.
South Dakota requires a licensed lender's contract to show the loan amount, payment amounts and due dates, how charges are calculated, the APR, delinquency terms and other required details. The contract must also include the South Dakota Division of Banking's contact information, and the lender must give you a copy.
The request may take a few minutes. Here's what most Dakota del Sur lenders require before they can review your information and decide whether to offer credit.
Lenders typically ask that you're 18 or older, live in the U.S. and can show a government-issued ID and a Social Security number, so they can confirm who you are. Some lenders accept an ITIN instead.
Lenders want income they can verify, such as wages, self-employment income or benefits, and they compare your monthly debt payments with it. The lower your debt-to-income ratio, the more room a new payment has.
An active checking account in your name is usually where the funds arrive and where monthly payments are drawn from. If you're consolidating, some lenders may pay your creditors directly instead.
In South Dakota, a well or septic system that fails on an acreage, a transmission that gives out on the pickup right before harvest, or a hospital bill after a long drive for care rarely fits into one paycheck. One personal loan can pay a bill that size in full. If the cost is smaller and you'd rather keep the schedule short, an installment loan may suit it better.
In South Dakota, the warm months are short, so a basement finish, new siding or a deck often has to happen in a single season. Others put a personal loan toward a wedding in the Black Hills, furnishing a first place in Sioux Falls or Brookings, or clearing several cards at once. When consolidating debt, compare the new APR, repayment term, fees and total of payments with what your existing debts would cost. How debt consolidation works walks through that option step by step.
In South Dakota, a $4,000 loan repaid over 36 months at a 36% annual rate would require payments of about $183.22 a month and total about $6,596, including roughly $2,596 in interest. This illustration assumes equal monthly payments, on-time repayment and no additional default-related charges. The DTI and max loan calculator helps you find a payment that fits your income.
In South Dakota, a $15,000 loan repaid over 60 months at a 36% annual rate would require payments of about $541.99 a month and total about $32,520, including roughly $17,520 in interest. This illustration assumes equal monthly payments, on-time repayment and no additional default-related charges. A longer term lowers the monthly payment but increases the total interest paid, the reason a smaller monthly payment can cost you more.
Businesses engaged in money lending in South Dakota generally need a Division of Banking license unless a statutory exemption applies. You can verify covered money lenders through NMLS Consumer Access before sending documents. Your loan contract must also include the Division of Banking's address and phone number, so you know where to raise a concern about how a loan was made.
On a larger loan, even a small gap in APR keeps adding up year after year, so lining up offers is worth the effort. Bromoney lets you send one form online rather than typing your details out for every lender. If partners send offers to your account, you'll see the APR, monthly payment, term and total for each one together. Whether to go ahead, and with whom, is your call, and using Bromoney is free.
Estimate exactly how much you'll owe before you commit. Enter your loan amount and repayment term to see total costs, including fees and interest, laid out clearly.
Calculate my loanThese protections come from South Dakota law for state-licensed money lenders; they aren't terms any lender has offered.
Credit insurance
Your choice
A licensed lender can't make credit life or health insurance a condition of your loan.
Add-ons and loan fees
Inside the rate limit
Charges for ancillary products or services and other fees incident to extending credit generally count toward the 36% annual limit. Certain charges arising after default, including late fees, returned-check fees and attorney's fees, are treated separately.
Once you've paid it off
Release within 60 days
Within 60 days after payment in full, the lender must cancel the note and send the borrower the note marked paid in full along with releases of any applicable liens or assignments.
State rules reviewed November 2026. For the current limits, check with the South Dakota Division of Banking.
Personal loans for debt consolidation pay off several card or loan balances and replace them with one monthly payment and a known payoff date. The move pays off when the new APR and total cost are lower than what those balances cost you, so compare before you shift the debt.
Small personal loans, starting at $1,000, can cover one bill, a repair or a deposit without a commitment that lasts for years. A smaller amount usually comes with a shorter term, which keeps the total interest down.
Unsecured personal loans rely on your income and credit rather than an asset, which is how most personal loans are set up. Secured personal loans put something you own, like a savings account or a vehicle, behind the debt, so check which type your offer is before you sign.
Some lenders let you add a cosigner or a co-borrower. Personal loans with a cosigner, or joint personal loans, can help when your income or credit history is thin, because the lender also weighs the second person's profile, but that person shares responsibility for every payment.
Personal loans for home improvement, a move, a wedding or a major car repair let you pay for a larger cost at once and spread it over the months ahead instead of carrying it on a card at a revolving rate.
Personal loans for bad credit exist, but the price shifts: a lender that works with a lower score usually balances the risk with a higher APR, a smaller amount or a shorter term. That's why lining up several options matters more here than anywhere else on this page.
Personal loan rules differ by state, from rate limits to the licenses lenders need. Pick your state to see what applies there and compare the options available to you.
In South Dakota, you get a personal loan as one lump sum, and each monthly installment goes partly to interest and partly to principal, bringing the balance to zero by the final month.
Possibly. In South Dakota, lenders set their own credit standards and may look at your income and current debts as well as your score, so a lower score doesn't decide things on its own, though no outcome is promised. You may be able to check an estimated credit score free in your Bromoney account, and if a lender says no, these next steps after a denial can help.
In South Dakota, the lender sets the amount after looking at your income, existing debts and credit history. Before you settle on a number, a budget stress test shows what payment still leaves room for a surprise or two.
In South Dakota, when the money arrives is up to the lender and may vary. Before it shares its terms, a partner may want to see pay stubs or bank statements.
In South Dakota, the form asks about your income, employment, bank account and how to reach you. A lender may ask for ID or proof of income later, and the documents checklist lists what to have on hand.
In South Dakota, a state-licensed money lender can charge no more than 36% a year under SDCL 54-4-44, a limit voters set through Initiated Measure 21 in 2016, and a loan above it is void. Banks and federally insured credit unions are exempt from that chapter, so their rates may differ, and offers partners send on Bromoney can vary by lender. Look at the APR, not just the interest rate, to see each offer's full yearly price.
Your agreement decides that, and where it allows it, paying ahead may lower the interest you pay overall. In South Dakota, ask the lender for a payoff figure for a specific date, and the debt payoff calculator lets you test how extra payments move your payoff date.
In South Dakota, your loan contract must spell out any delinquency charge, so you know what a late payment would cost before you sign. The lender may report a missed payment to the credit bureaus, so reach out to it ahead of the due date if money looks tight.
No. In South Dakota, a payday loan can't exceed $500, while a personal loan can cover a much larger sum and stretches repayment over months or years.
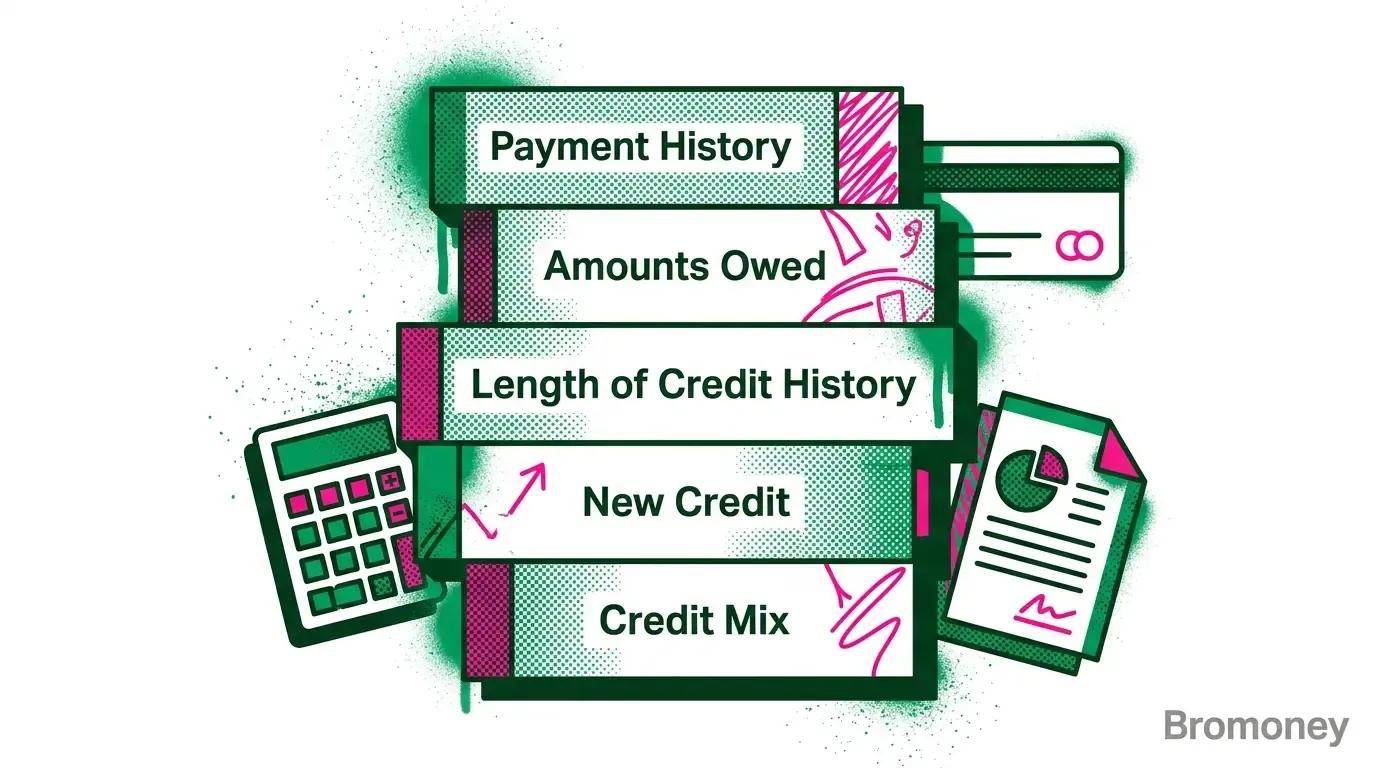
A practical breakdown of the five FICO Score factors, how each one works, and which actions improve your credit profile first.
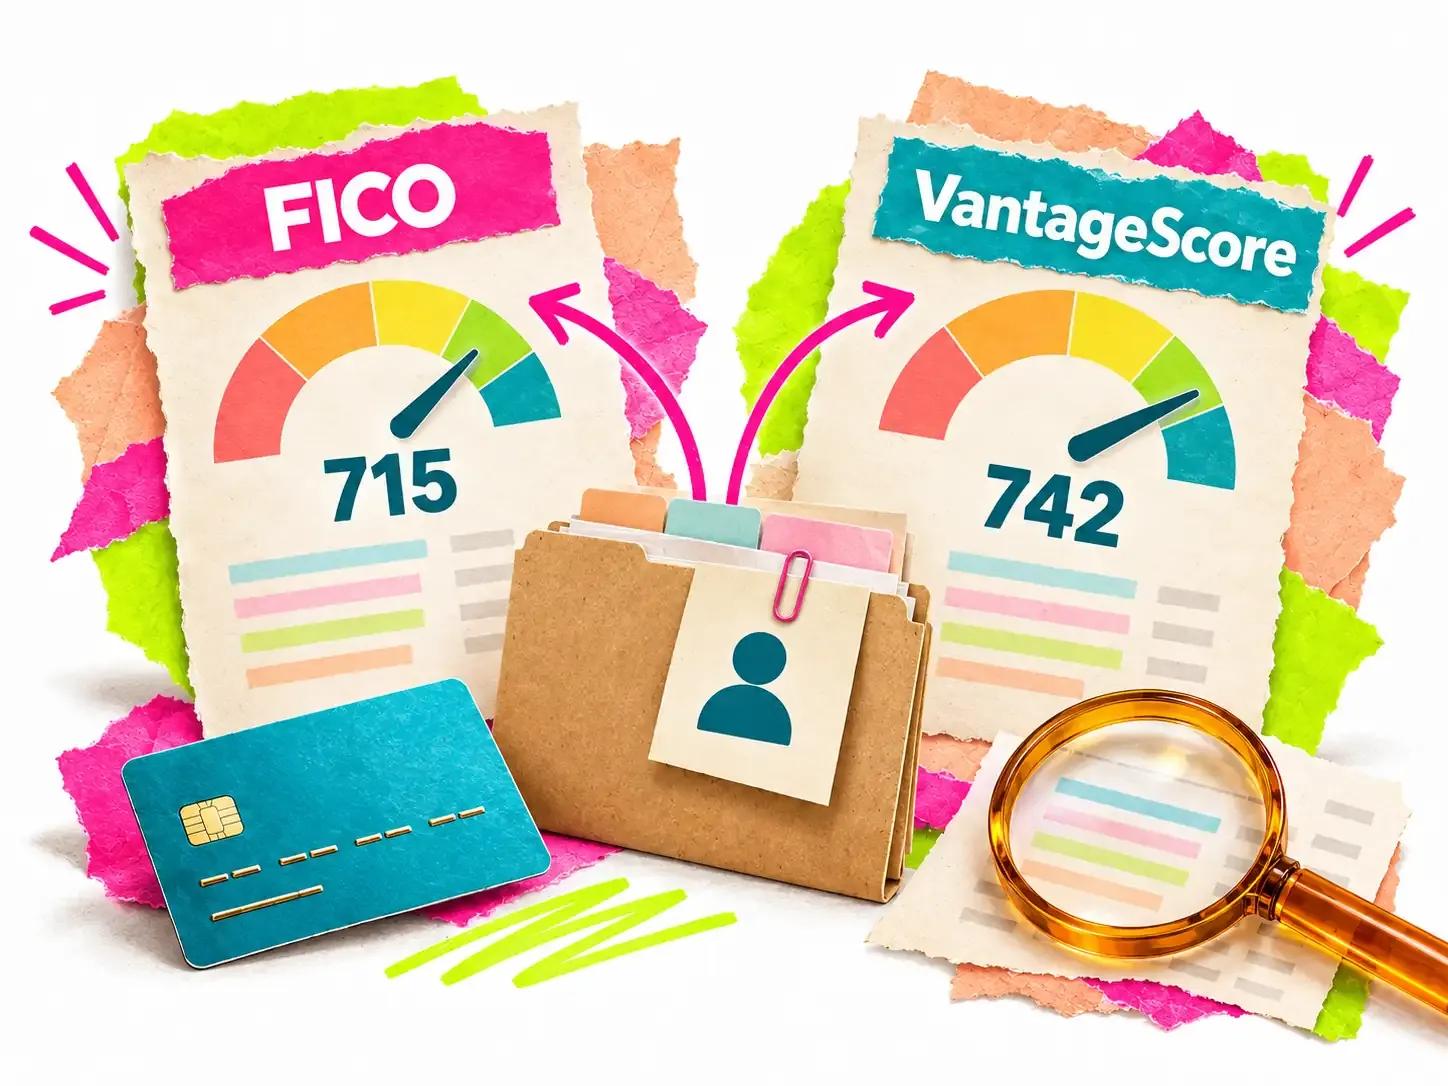
FICO and VantageScore can show different numbers for the same person because they use different models, bureau files, and update timing.
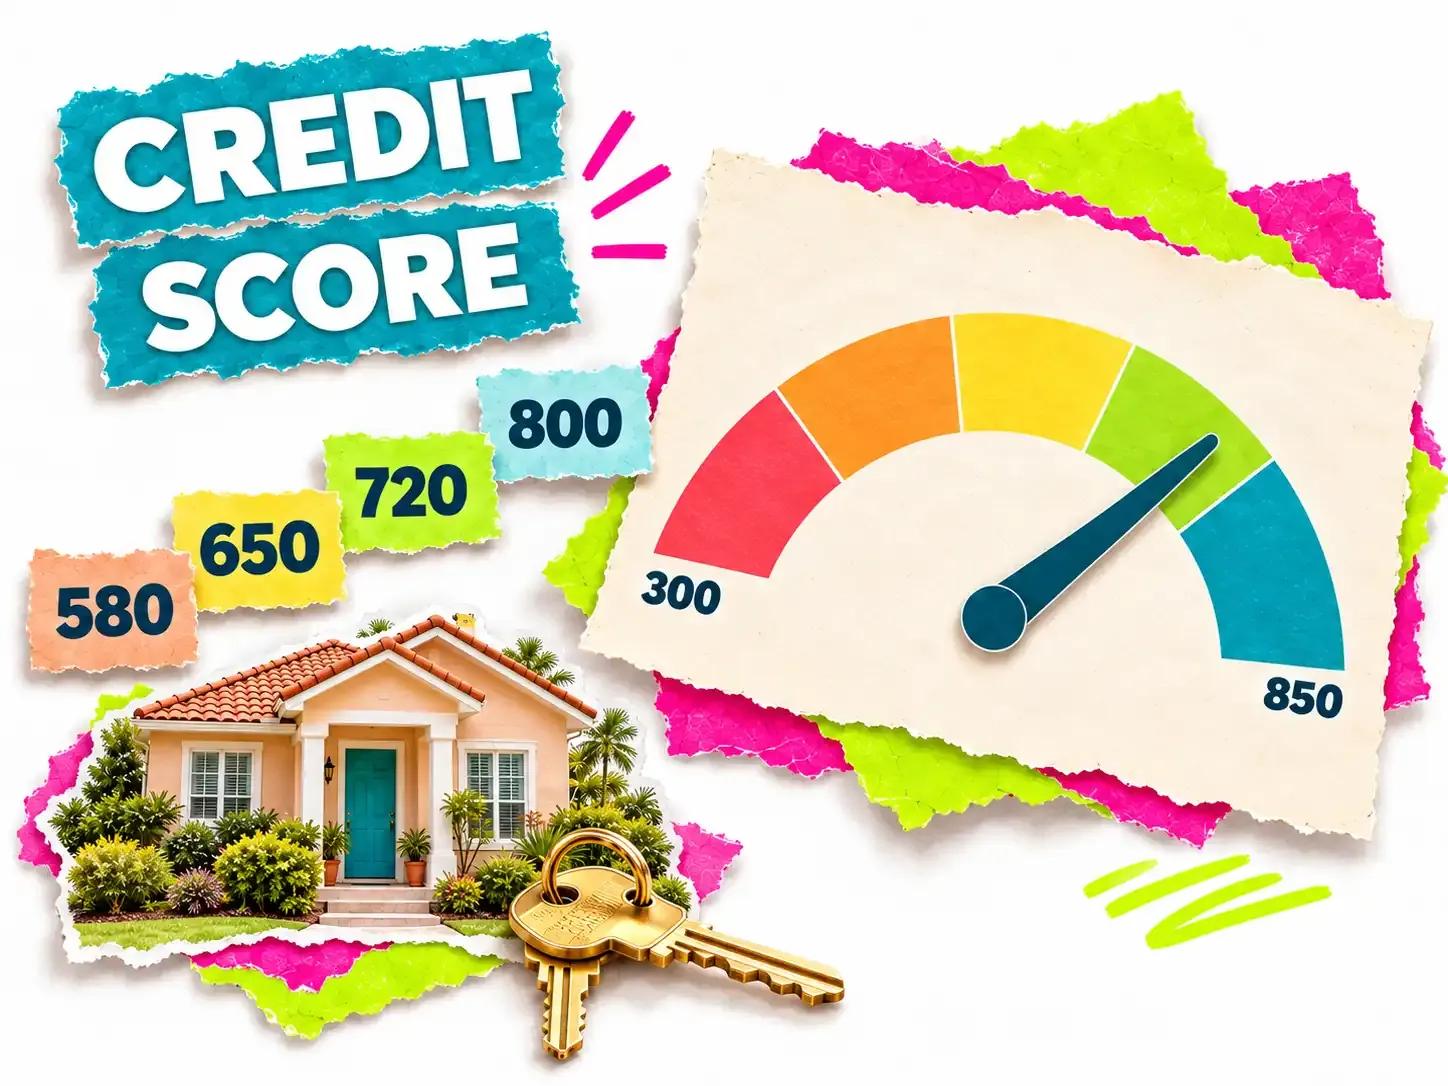
A practical guide to U.S. credit score ranges, including what 580, 650, 720, and 800 mean for mortgages, auto loans, credit cards, and rates.
We bridge the gap between your financial goals and premier lending services nationwide.
Bromoney is a financial marketplace, not a lender. Availability depends on the lender, the applicant's information, and where the applicant lives. When you submit a request form, your information is shared with lenders and partners in our marketplace so they can evaluate your request. Bromoney is operated by MONEY BROKER LLC (Delaware, DE File No. 10406065). This page is for general information and is not financial or legal advice.
You know the drill: one loan request, then waiting for the calls to start. Here you stay in control — we treat your information with care, you compare the options available to you, and you choose which lender or partner to move forward with. We can't speak for every partner, but we do our best to keep unwanted calls down.

Submitted over a secure connection


