

Identity and Residency
Lenders typically ask that you're 18 or older, live in the U.S. and can show a government-issued ID and a Social Security number, so they can confirm who you are. Some lenders accept an ITIN instead.

Clearing high-rate cards, finishing the basement or covering a big medical bill in Utah? A personal loan gives you one larger sum, so you can pay for the whole thing at once.
A personal loan in Utah typically gives you a larger amount up front and is repaid through scheduled installments over an agreed term. Covered consumer credit agreements are generally governed by the Utah Consumer Credit Code, which sets rules for disclosures, fees, repayment and other lending practices. Utah does not impose a general interest-rate cap on ordinary consumer credit agreements covered by the Code.
Checking available options with Bromoney does not require a credit-bureau inquiry and does not affect your credit score. If you select a partner and continue, that partner may perform a hard credit inquiry that can affect your score.
In Utah, the money from a personal loan isn't locked to a single purchase the way an auto loan or store card is, so the same sum can pay the contractor, the permit and the materials. The lender decides the amount and may ask what it's for.
In Utah, folding several card balances into a personal loan can replace multiple minimum payments and due dates with one scheduled payment and a defined repayment term. When consolidating card balances, compare the new APR, repayment term, fees and total of payments with the cost of keeping the existing debts. A lower APR can help, but a longer term may still increase the total amount you repay.
In Utah, a creditor that sends negative information about you to a credit bureau has to tell you in writing, no later than 30 days after the report. You hear about it from the lender instead of discovering it months later.
The request may take a few minutes. Here's what most Utah lenders require before they can review your information and decide whether to offer credit.
Lenders typically ask that you're 18 or older, live in the U.S. and can show a government-issued ID and a Social Security number, so they can confirm who you are. Some lenders accept an ITIN instead.
Lenders want income they can verify, such as wages, self-employment income or benefits, and they compare your monthly debt payments with it. The lower your debt-to-income ratio, the more room a new payment has.
An active checking account in your name is usually where the funds arrive and where monthly payments are drawn from. If you're consolidating, some lenders may pay your creditors directly instead.
In Utah, a cracked sewer line under an older Salt Lake City home, a transmission on the family SUV, or the hospital bill after a ski-season injury can run well past one month's budget. A personal loan pays a bill that size in full. For a smaller cost you'd rather clear in a few months, an installment loan may suit it better.
In Utah, finishing an unfinished basement, adding solar panels or replacing an old furnace and AC together is easier to plan with the full amount in hand. Others use a personal loan for a trailer before a summer of trips to the southern parks, or to pay off several cards at once, and how debt consolidation works lays out that option.
In Utah, the price of a loan depends on the offer, so it helps to know your limit before you compare. The DTI and max loan calculator turns your earnings and existing debts into a monthly figure to test every offer against.
In Utah, stretching the same loan from 36 to 60 months shrinks each payment but adds two more years of interest, so the total climbs even at the same APR. Before you pick the lower payment, see why a smaller monthly payment can cost you more.
Entities subject to Utah's Consumer Credit Notification requirement must file through NMLS before conducting covered consumer-credit business in the state and renew by December 31 each year. Federally insured depository institutions and their wholly owned subsidiaries are exempt from this notification requirement. You can check a company's status through NMLS Consumer Access before you send documents.
On a larger loan, the gap between one lender's price and another's is where the money is, so it's worth seeing more than one offer. Bromoney gives you a single online form instead of the same questions at every lender. If partners send offers to your account, you see each one's APR, monthly payment, term and total in one place. The decision to continue, and with whom, stays yours, and Bromoney costs you nothing.
Estimate exactly how much you'll owe before you commit. Enter your loan amount and repayment term to see total costs, including fees and interest, laid out clearly.
Calculate my loanThese protections come from Utah's Consumer Credit Code; they aren't terms any lender has offered.
Insurance a lender requires
Your policy, your insurer
You can use coverage you already have or buy it elsewhere; the lender may decline it only for reasonable cause.
Assignment of your wages
Only on your terms
Allowed only if you can revoke it, it's a payroll plan you set up at the start, or it covers pay already earned.
An oversized final payment
Right to refinance it
If one payment is more than twice the average of earlier ones, you can refinance it when due, if the lender still offers that credit and you qualify.
State rules reviewed November 2026. For current requirements, check with the Utah Department of Financial Institutions.
Personal loans for debt consolidation pay off several card or loan balances and replace them with one monthly payment and a known payoff date. The move pays off when the new APR and total cost are lower than what those balances cost you, so compare before you shift the debt.
Small personal loans, starting at $1,000, can cover one bill, a repair or a deposit without a commitment that lasts for years. A smaller amount usually comes with a shorter term, which keeps the total interest down.
Unsecured personal loans rely on your income and credit rather than an asset, which is how most personal loans are set up. Secured personal loans put something you own, like a savings account or a vehicle, behind the debt, so check which type your offer is before you sign.
Some lenders let you add a cosigner or a co-borrower. Personal loans with a cosigner, or joint personal loans, can help when your income or credit history is thin, because the lender also weighs the second person's profile, but that person shares responsibility for every payment.
Personal loans for home improvement, a move, a wedding or a major car repair let you pay for a larger cost at once and spread it over the months ahead instead of carrying it on a card at a revolving rate.
Personal loans for bad credit exist, but the price shifts: a lender that works with a lower score usually balances the risk with a higher APR, a smaller amount or a shorter term. That's why lining up several options matters more here than anywhere else on this page.
Personal loan rules differ by state, from rate limits to the licenses lenders need. Pick your state to see what applies there and compare the options available to you.
In Utah, you get a personal loan as one lump sum and repay it in equal monthly installments, each covering some interest and some principal until the balance reaches zero.
Possibly. In Utah, each lender uses its own credit standards and may consider your income and current debts along with your score, so a lower score isn't the only factor, though no outcome is promised. You may be able to see an estimated credit score free in your Bromoney account, and if a lender turns you down, read what to do after a denial.
In Utah, the lender sets the amount from your income, debts and credit history. A budget stress test helps you choose a figure that still works if costs rise or income dips.
In Utah, the lender decides when funds go out, and timing may vary between offers. A partner may want pay stubs or bank statements before it shows its terms.
In Utah, the form asks about your income, employer, bank account and contact details. A lender may follow up for ID or proof of income before it finalizes anything.
In Utah, there's no state cap: under Utah Code § 70C-2-101, the lender and borrower can agree on any finance charge and fees unless the Consumer Credit Code says otherwise. That makes the spread between lenders wide, so compare the APR, not just the interest rate, since offers partners send on Bromoney can differ.
Yes, with no prepayment penalty. In Utah, the Consumer Credit Code has let you prepay a closed-end loan without a penalty since May 6, 2026, though an upfront fee paid at the start isn't refunded unless your agreement says so. The debt payoff calculator shows what extra payments could save.
In Utah, a non-bank lender can add a late fee only if your contract provides for one, capped at the greater of $30 or 5% of the overdue amount and charged once per installment; banks may set a higher fee. The lender may also report the missed payment to the credit bureaus, so call before the due date if money looks short.
No. In Utah, a payday loan is a short-term loan usually repaid in a single payment, and interest stops once it has been outstanding for 10 weeks. A personal loan covers a larger sum over months or years of fixed installments.
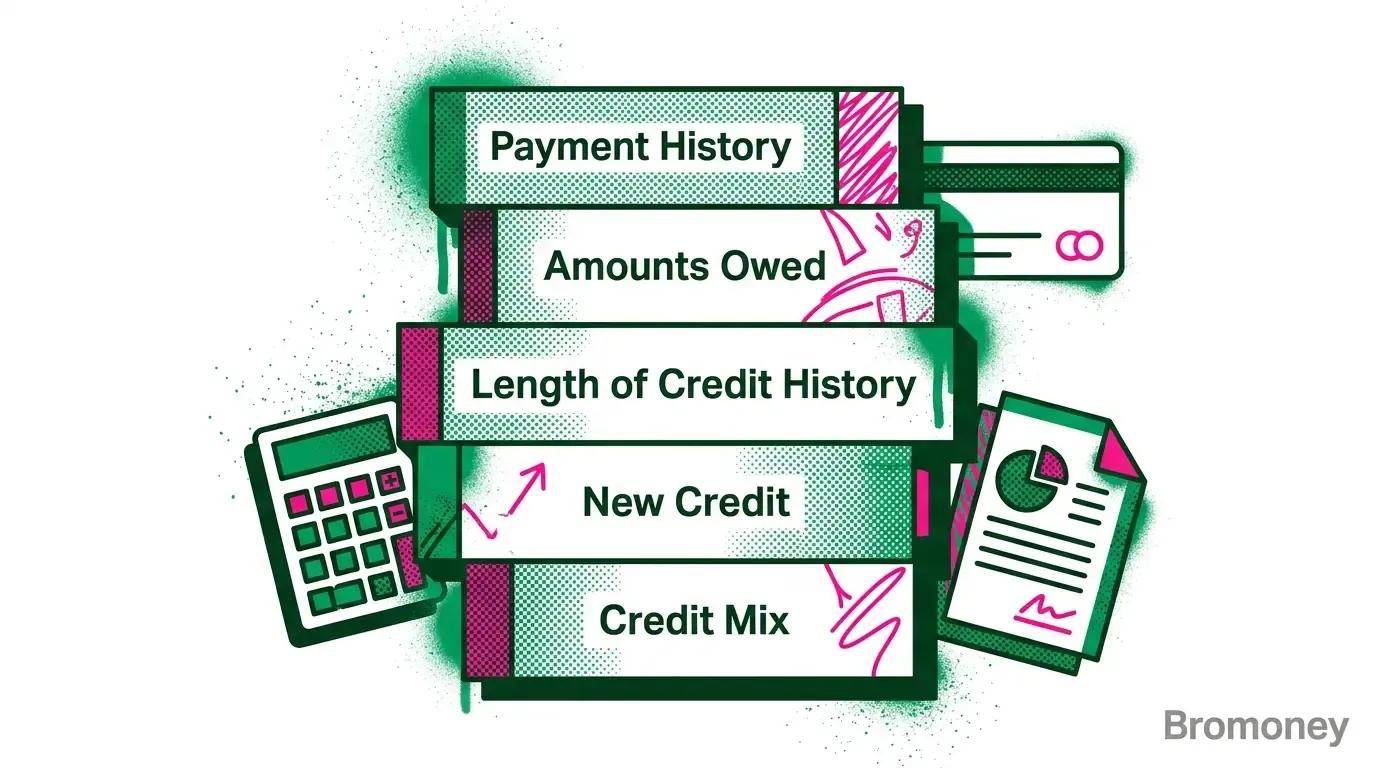
A practical breakdown of the five FICO Score factors, how each one works, and which actions improve your credit profile first.
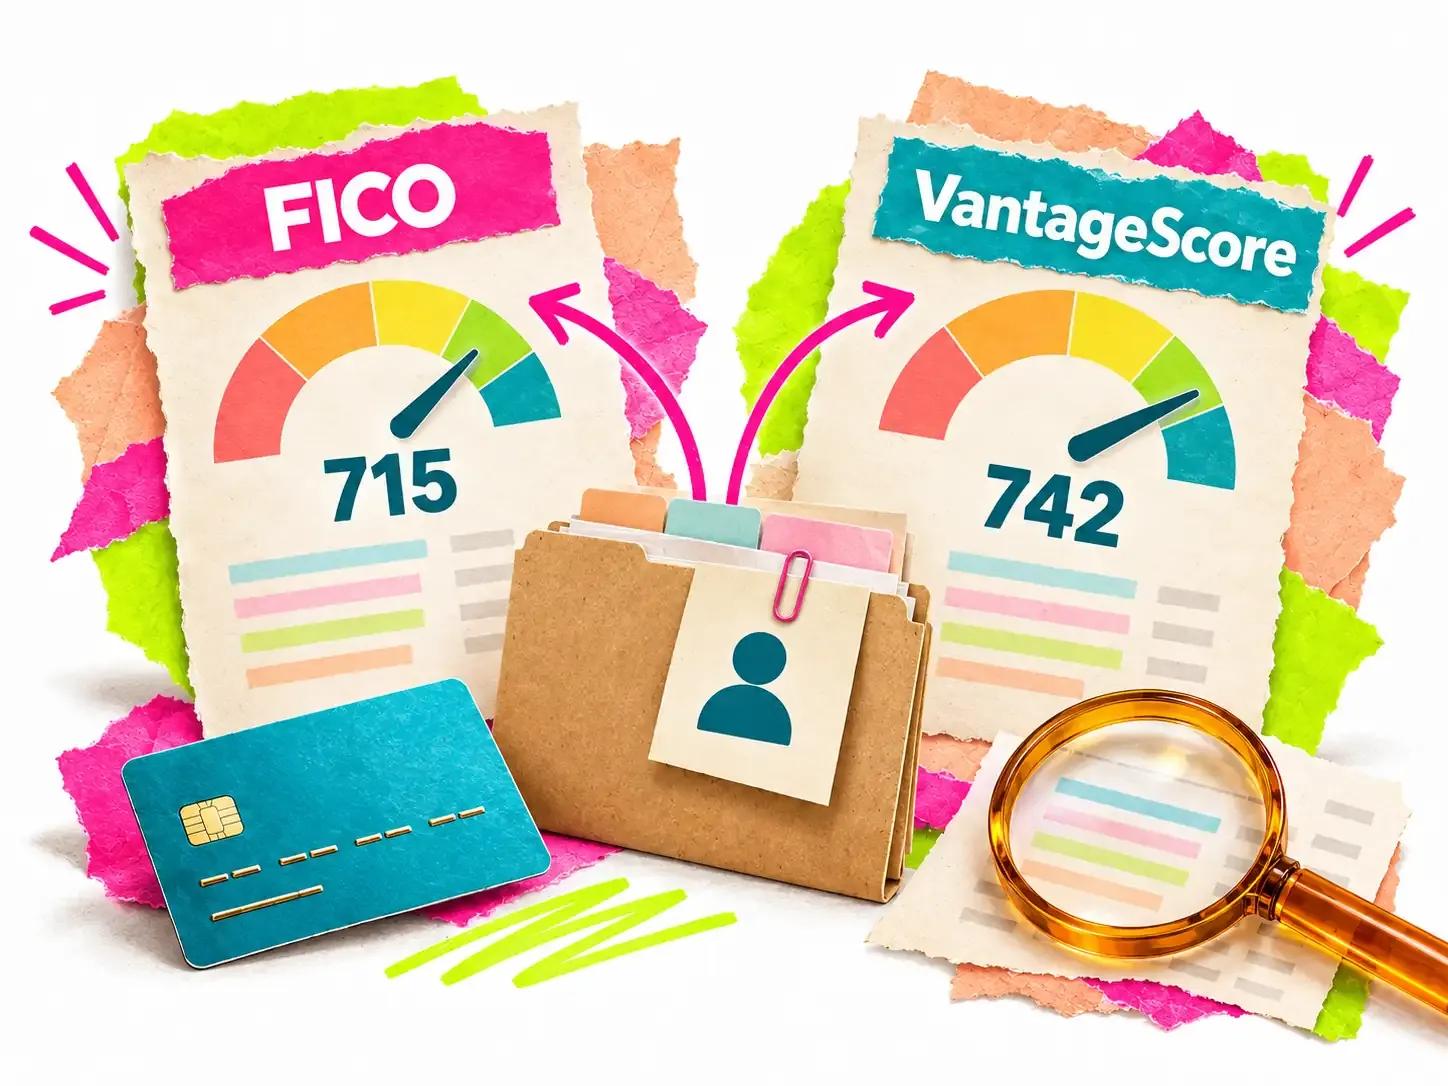
FICO and VantageScore can show different numbers for the same person because they use different models, bureau files, and update timing.
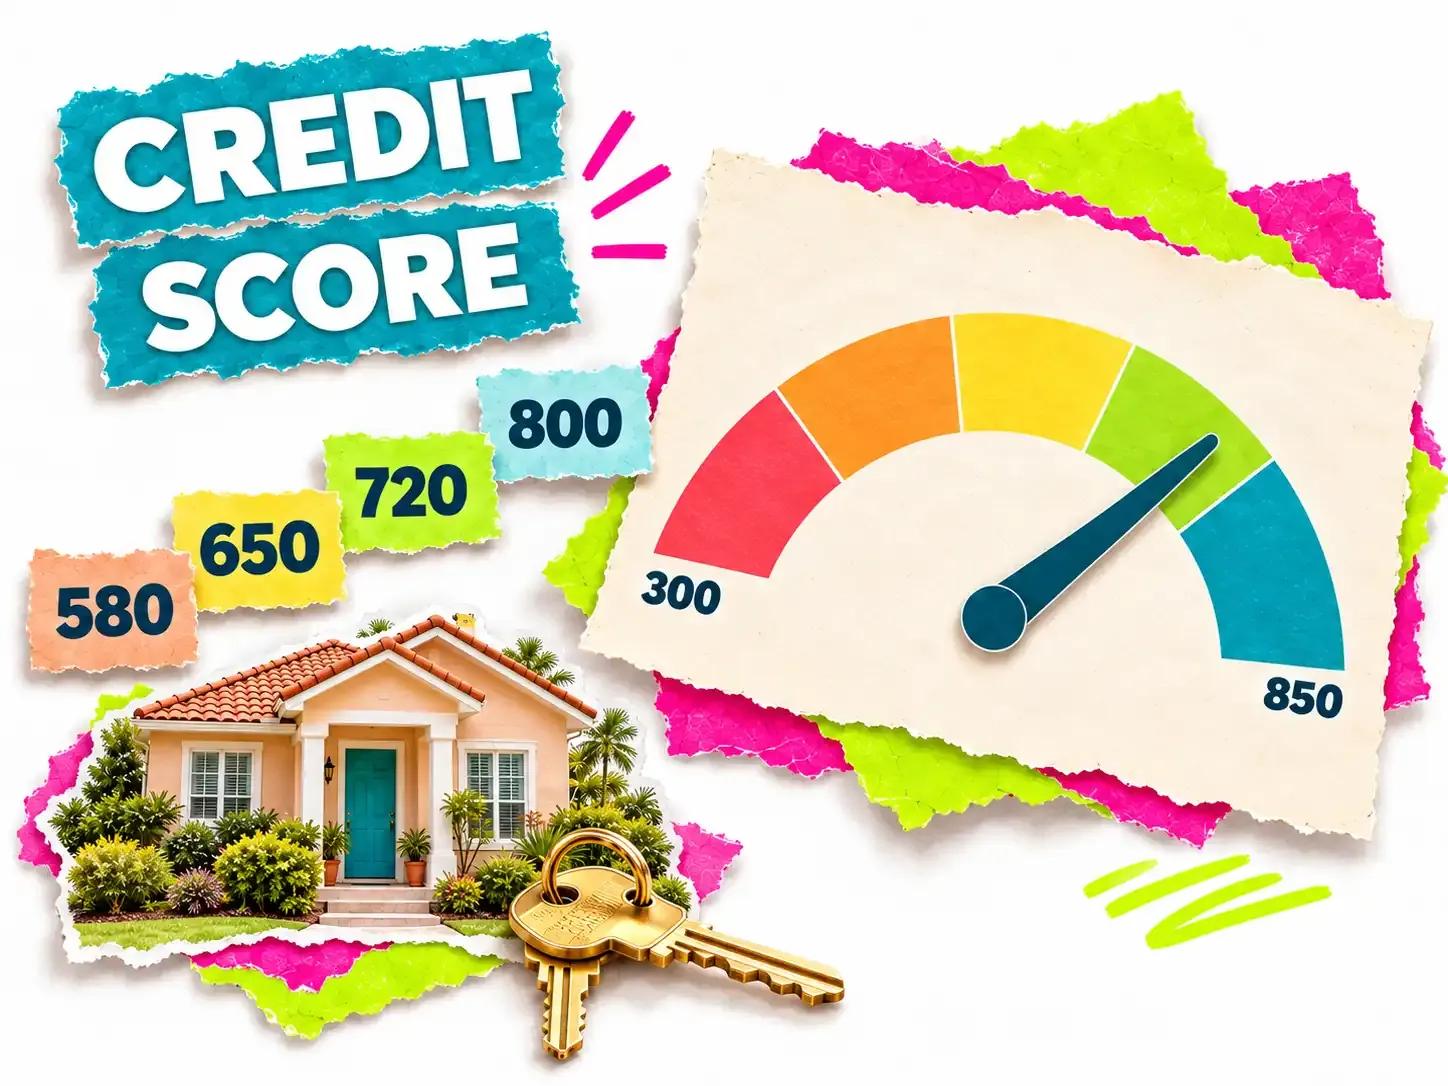
A practical guide to U.S. credit score ranges, including what 580, 650, 720, and 800 mean for mortgages, auto loans, credit cards, and rates.
We bridge the gap between your financial goals and premier lending services nationwide.
Bromoney is a financial marketplace, not a lender. Availability depends on the lender, the applicant's information, and where the applicant lives. When you submit a request form, your information is shared with lenders and partners in our marketplace so they can evaluate your request. Bromoney is operated by MONEY BROKER LLC (Delaware, DE File No. 10406065). This page is for general information and is not financial or legal advice.
You know the drill: one loan request, then waiting for the calls to start. Here you stay in control — we treat your information with care, you compare the options available to you, and you choose which lender or partner to move forward with. We can't speak for every partner, but we do our best to keep unwanted calls down.

Submitted over a secure connection


