Age & Residency
You'll generally need to be at least 18 and live in the U.S. Lenders use that basic borrower information to start an eligibility review.
Montana borrowers can request payday loans online through Bromoney and receive offers from direct lenders in minutes. Compare real terms, apply from anywhere in MT, and get a decision without leaving home.
Compare lenders and decide,
Get StartedSecure 256-bit Connection
A payday loan is a short-term, small-dollar loan, often $100-$500 and in some states higher, usually due by your next paycheck or within about two to four weeks. The borrower receives funds, then repays the amount borrowed plus a fee on the due date. Also called a cash advance, it can cover a bill that lands before your paycheck does.
Montana applicants who complete the form before the daily cutoff typically receive funds in their checking account within one business day.
Direct lenders on Bromoney evaluate Montana borrowers primarily on income and banking history, not credit score alone - making approval accessible even after past financial setbacks.
Every lender in the Bromoney network serving Montana holds a valid license from the Montana Division of Banking and Financial Institutions and operates within the state's 36% APR cap.
The request may take a few minutes. Here's what most Montana lenders require before they can review your information and decide whether to offer credit.
You'll generally need to be at least 18 and live in the U.S. Lenders use that basic borrower information to start an eligibility review.
Your income can come from work or benefits, but it needs to be steady enough for the lender to see how you'll repay.
Most lenders ask for an active bank account so funds and repayment can move through a place you already use.
Montana's 36% APR ceiling stands in sharp contrast to neighboring Wyoming, which has no rate cap at all, and North Dakota, which allows fees up to 20% per $100 borrowed. Montana borrowers pay significantly less in finance charges, but the stricter cap also means fewer lenders operate in the state compared to its neighbors.
Consumer lending in Montana is supervised by the Montana Division of Banking and Financial Institutions (DBFI), part of the Montana Department of Administration. Borrowers can file complaints, verify lender licenses, and access consumer guidance at banking.mt.gov. The DBFI enforces the 36% APR ceiling and the prohibition on rollovers under the Montana Deferred Deposit Loan Act.
Montana's Initiative 164 caps payday loan APR at 36%, one of the lowest limits in the country. Bromoney surfaces only lenders who comply with that ceiling, so residents of Billings or Missoula see real, legal offers - not bait-and-switch rates that collapse under state scrutiny. One form, multiple compliant lenders, zero guesswork.
Estimate exactly how much you'll owe before you commit. Enter your loan amount and repayment term to see total costs, including fees and interest, laid out clearly.
Calculate my loanLegal lending restrictions for MT residents.
Max Loan Amount
No statutory cap
Based on Montana Deferred Deposit Loan Act; lender limits typically $100-$300 in practice
Max Term
31 days
Maximum allowed repayment window
APR/Fees
36% APR
Legal cap in Montana per Initiative 164 (2010)
Rollovers
Not allowed
Montana law prohibits rolling over or refinancing a payday loan into a new deferred deposit loan to extend the repayment period.
Information provided is for educational purposes only. Borrowers are encouraged to review all loan terms carefully before signing. Interest rates and fees vary by lender and loan type.
If one due date feels too tight, an installment loan spreads the amount borrowed across fixed payments. You repay over a longer window, which can make budgeting easier, though the lender's terms still decide the real cost.
A credit union PAL or a personal loan can be a slower, lower-cost path when you have room to plan. You may need credit union membership for a PAL, while a personal loan usually leans harder on your credit profile.
Sometimes the better move is closer to home: state assistance, a local credit union, or a community program. Options change by state, so use your state page to see what may sit alongside payday loans.
Payday loans online work differently by state. What you can borrow, what a cash advance can cost, and how you repay may change under state laws. If you have bad credit or a tight bill gap, choose your state below to review legal loan amounts, terms, and the options available to you.
Yes. Payday loans are legal in Montana under the Montana Deferred Deposit Loan Act. However, lenders must hold a license issued by the Montana Division of Banking and Financial Institutions and may not charge an APR above 36% per year. Loans exceeding that cap are unenforceable under state law.
Montana does not set a fixed dollar cap on payday loan principal by statute. In practice, licensed lenders typically offer between $100 and $300 on a single loan, because the 36% APR cap makes larger short-term amounts unprofitable for lenders. The exact amount depends on your income and the lender's own underwriting criteria.
The Montana Deferred Deposit Loan Act limits payday loan terms to a maximum of 31 days. Lenders cannot extend the term beyond one calendar month, and rollovers are prohibited - meaning you cannot refinance or roll over the same loan into a new one to avoid repayment.
Many Montana-licensed direct lenders on the Bromoney platform do not require a strong credit score. Approval decisions typically weigh proof of steady income and an active checking account more heavily than a FICO score. Some lenders perform only a soft credit inquiry during the application process, though others may conduct a hard credit pull.
After a lender approves your application, funds are usually deposited via ACH transfer within one business day. Some lenders offer same-day funding if the approval is completed before the bank's daily cutoff time. Weekend applications are typically processed on the next business day.
The form may ask for identifying, contact, income, employment, and banking information. A lender or partner may request supporting information before deciding whether to continue. Requirements and the information accepted can vary by lender, partner, state, and the option available to you.
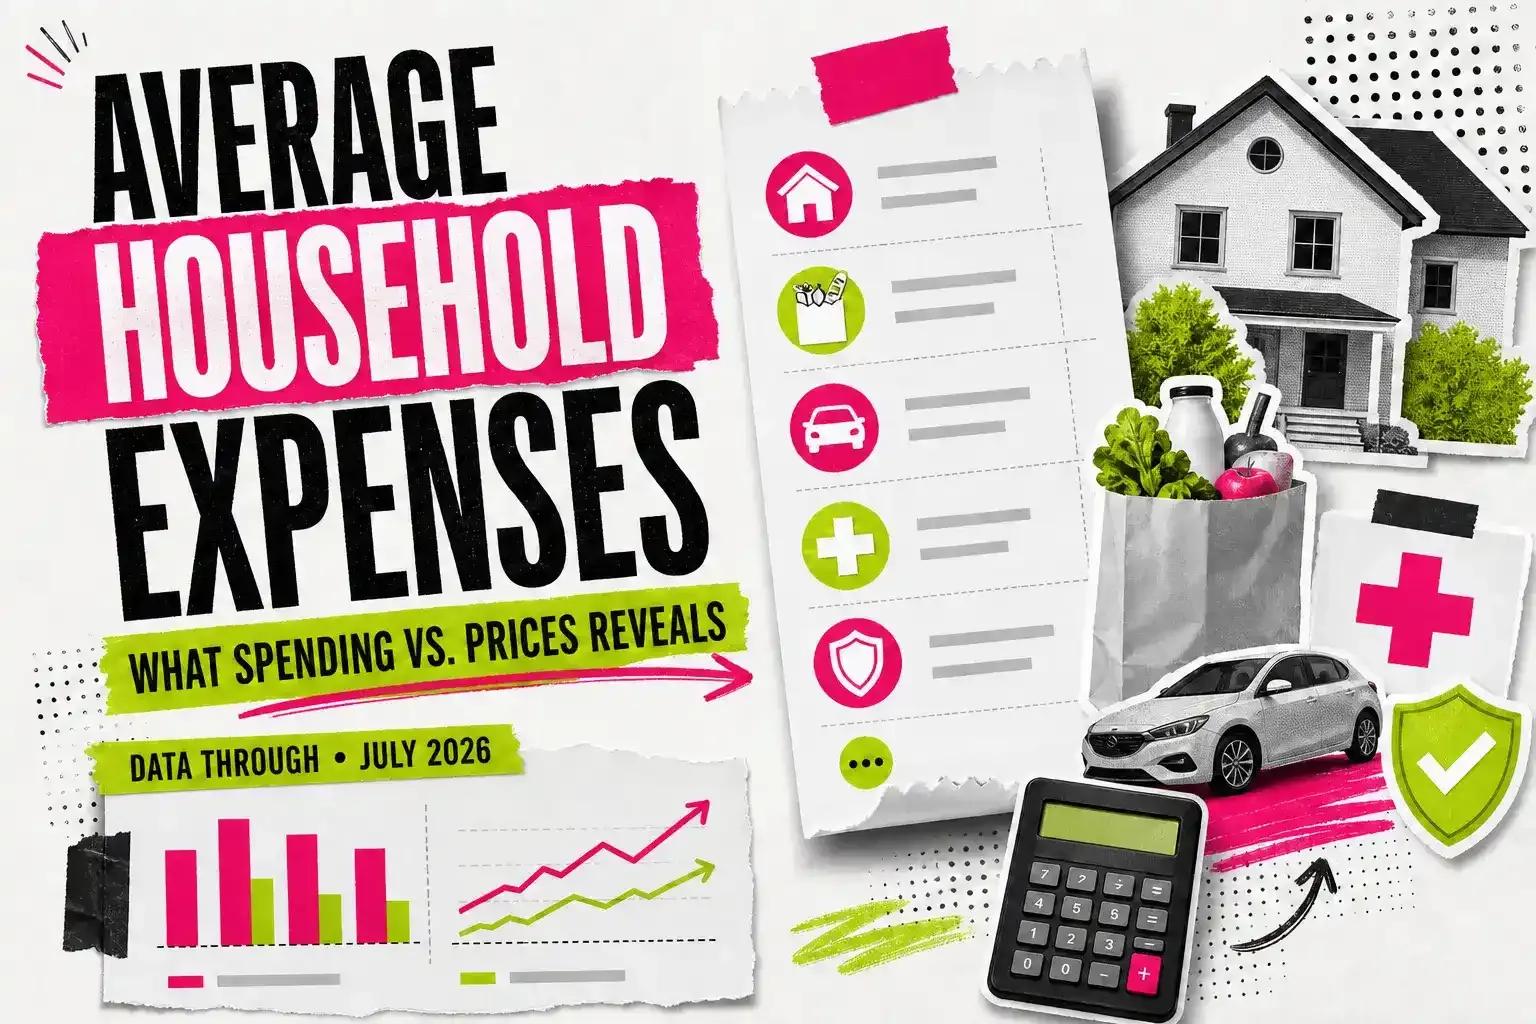
The average US consumer unit spent $78,535 in 2024 - about $6,545 a month. This page sets that spending record against the price indexes for the same two years, category by category, using our own CE-CPI crosswalk, and states plainly what the figures cannot show.
We bridge the gap between your financial goals and premier lending services nationwide.
This page is informational and does not guarantee approval. Actual rates depend on your lender and Montana regulations.
You know the drill: one loan request, then waiting for the calls to start. Here you stay in control — we treat your information with care, you compare the options available to you, and you choose which lender or partner to move forward with. We can't speak for every partner, but we do our best to keep unwanted calls down.
Submitted over a secure connection


