Age & Residency
You'll generally need to be at least 18 and a U.S. resident. Those basics help lenders review borrower eligibility before they look at the rest of your request.
Trying to cover a planned cost without turning your whole month upside down? Montana installment loans are paid back in equal scheduled payments over a set term. Complete one form, review the options that appear in your account, then choose what fits your budget, or walk away. Free to start. No obligation.
Compare lenders and decide,
Get startedSecure 256-bit Connection
An installment loan is a loan repaid in a set number of scheduled payments, called installments, often for $300 to $5,000 and repaid over a fixed term in equal payments. The borrower gets the funds up front, then repays the amount borrowed plus interest until the balance reaches zero. It's also called a structured or scheduled-payment loan. Unlike a payday loan due in one lump sum, it spreads the cost across multiple payments, so you can plan around it.
A bill can land before your budget is ready for it. With Bromoney, one form reaches lenders and partners in our marketplace, and your account shows the options available to you in one place. Montana's repayment structure is Scheduled installments over a set term, so each option should be reviewed by its payment schedule, term, and total cost. You compare, you choose, or you walk away. No obligation.
A thin or rough credit file can feel like a label. It isn't. Montana's legal status for installment lending is Legal and regulated, and state law sets no minimum credit score for borrowers. A lender still makes the decision, and no outcome is promised, but you can review the options available to you without letting one number do all the talking.
That monthly payment is only one piece of the math. Under Cost disclosure (TILA), Montana borrowers get this protection: Required before you agree. The lender must show the APR, finance charge, scheduled payment, and total of payments before you accept the loan, which helps you see what the loan costs across the full term, not just this month.
Installment lending in Montana isn't a free-for-all. License required: Yes, meaning Montana law requires installment lenders to hold a state license from the Montana Division of Banking and Financial Institutions before operating. If you're an active-duty service member or covered dependent, Military protection is 36% MAPR (federal MLA), no matter what a lender might otherwise charge.
The request may take a few minutes. Here's what most Montana lenders require before they can review your information and decide whether to offer credit.
You'll generally need to be at least 18 and a U.S. resident. Those basics help lenders review borrower eligibility before they look at the rest of your request.
A steady, verifiable income source, including benefits, helps lenders decide whether the payment fits your budget. They also review your credit profile, so keep the amount you can repay in mind before you move forward.
An active bank account is usually needed to receive funds and make scheduled payments. Check the payment setup before you choose, so the due dates don't catch you off guard.
The heating system needs work before winter. The car repair in Billings can't wait. A medical bill lands during a slower pay cycle in Missoula. None of that has to mean panic, but it can knock a month sideways. In Great Falls and elsewhere in Montana, some borrowers look at installment loans because the cost is paid back through equal monthly payments over a set term. You compare the options available to you, then pick the payment and term that fit your cash flow.
Montana's average credit score is around 727 as of 2023, according to Experian, which puts the state toward the higher end. Still, plenty of borrowers in Billings and across the state have fair, thin, or uneven files. That isn't a moral scorecard. A hard inquiry is possible, and more than one lender may run one, and it can affect your credit score, so go in with that part clear.
ExperianExperian reports that consumers in Montana carry an average credit card balance of around $5,800 as of 2023. When several balances are moving at once, one scheduled monthly payment can feel easier to track than a stack of due dates. It doesn't erase what you owe. It just puts the payoff on a fixed schedule you can compare before choosing.
ExperianThe Federal Reserve SHED report found that roughly 37% of U.S. adults as of 2023 would have trouble covering an unexpected $400 expense without borrowing or selling something. That's a national number, not a Montana-only figure. Even so, the pressure can feel very local in Billings or Missoula when one uneven paycheck turns a manageable month into a tight one. Knowing your options before you're under the gun gives you more room to think.
Federal Reserve SHEDThe Montana Division of Banking and Financial Institutions issues licenses for installment lenders operating in Montana, takes consumer complaints, and lets you verify whether a lender can do business in the state. If you're active-duty military or a covered dependent, including those stationed at Malmstrom Air Force Base, the federal Military Lending Act caps your rate at 36% MAPR. That's federal protection, not a lender courtesy.
Montana Division of Banking and Financial InstitutionsYou fill out one form, then review the options that appear in your account. The APR, scheduled monthly payment, and term sit side by side, which makes the trade-off easier to see without chasing numbers all over the place. Bromoney isn't a lender, doesn't make credit decisions, and doesn't push one offer over another. If nothing works for your budget, you can leave it there. It's free to start, and there's no obligation. We take a responsible approach to your data and do our best to prevent unwanted calls. Bromoney is operated by Money Broker LLC (DE File No. 10406065).
Estimate exactly how much you'll owe before you commit. Enter your loan amount and repayment term to see total costs, including fees and interest, laid out clearly.
Calculate my loanMontana oversees installment lending through the Montana Division of Banking and Financial Institutions, and state law requires installment lenders to hold the proper license before operating. Federal Truth in Lending Act rules add another layer by requiring APR and finance charge disclosures before you sign. Active-duty service members and covered dependents also have the Military Lending Act's 36% MAPR ceiling. For the rate, payment schedule, and terms tied to your own request, review the options shown in your account before you agree.
Legal status
Legal and regulated
Installment lending is allowed in Montana, with state rules covering lender licensing and consumer protections.
Regulator
Montana Division of Banking and Financial Institutions
This agency issues licenses for installment lenders in Montana and handles consumer complaints. You can check a lender's license with the regulator.
License required
Yes
Montana law requires installment lenders to hold a state license from the Montana Division of Banking and Financial Institutions before operating. This describes state law, not any specific marketplace participant.
Payday lending status
Legal and regulated separately
Payday lending is legal in Montana, but it is regulated as a separate product and is not the same as an installment loan.
Repayment structure
Scheduled installments over a set term
An installment loan pays down over time through equal scheduled payments, unlike a single-payment product due all at once.
Rollovers
Not applicable to installment loans
Installment loans use a fixed repayment schedule. Rollovers belong to single-payment products, not structured installment lending.
Cost disclosure (TILA)
Required before you agree
The federal Truth in Lending Act requires disclosure of the APR, finance charge, scheduled payment, and total of payments before you sign.
Military protection
36% MAPR (federal MLA)
The Military Lending Act caps covered consumer credit at 36% MAPR for active-duty service members and covered dependents. This is federal protection.
This information is educational and is not legal or financial advice. The rules for a specific loan depend on the lender's license type and the loan amount under Montana law, so an individual agreement may not look the same as the general figures above. Regulations change. For current requirements, consult the Montana Division of Banking and Financial Institutions at https://banking.mt.gov/ and the official Montana code.
If your next paycheck is the only repayment date, that window can feel tight. A payday or single-payment loan is usually repaid in one lump sum, while an installment loan spreads what you borrow across scheduled payments over a term.
A credit card or line of credit works more like a running tab. You can borrow again as you repay, but there's usually no fixed payoff date. An installment loan is different: one amount, one scheduled payment, and a term with an ending point.
Credit unions, local lenders, and nonprofit programs may be worth a look, especially if you're already a member somewhere. Costs and rules can change by state, so compare those local options against any installment loan terms you see online.
Installment loans online don't work the same way in every state. Loan amounts, terms, APR caps, and legal rules can change where you live. Whether you borrow for a repair, scheduled payments, structured repayment, bad credit, or to consolidate bills, choose your state below and compare the options available to you.


The average US consumer unit spent $78,535 in 2024 - about $6,545 a month. This page sets that spending record against the price indexes for the same two years, category by category, using our own CE-CPI crosswalk, and states plainly what the figures cannot show.
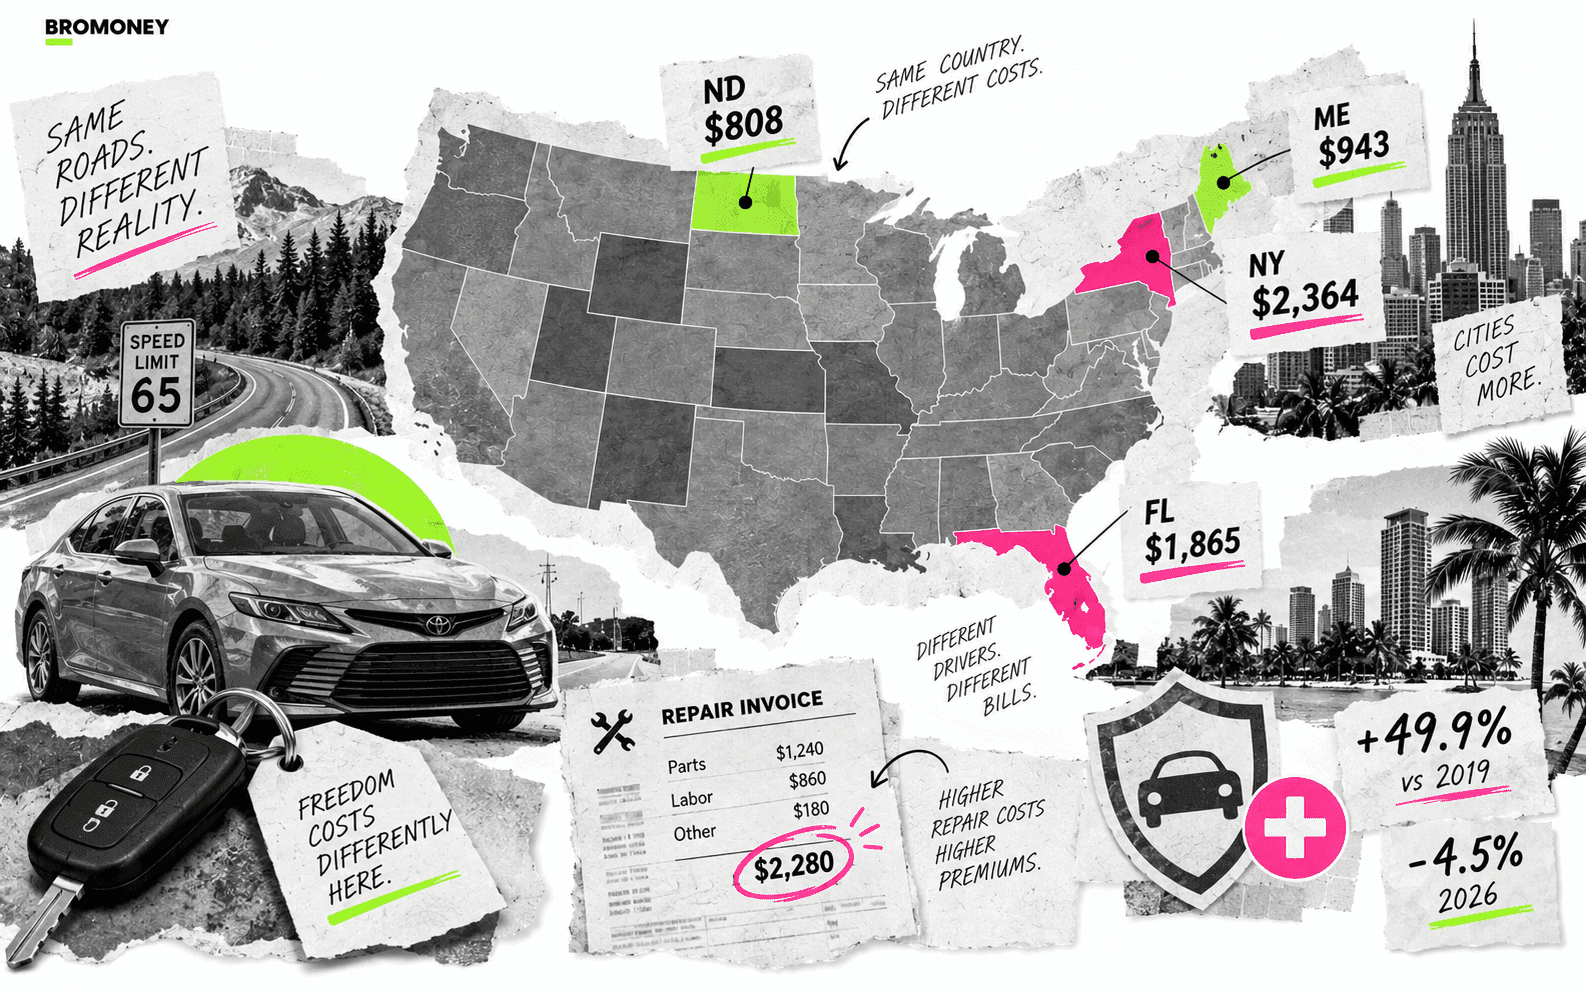
Car insurance spending rose 12.3 percent in 2024, one of only two costs BLS called statistically significant. NAIC's 2023 state averages, why rates are falling even as the level sits 49.9 percent above 2019, what actually drives claims costs, and which levers on your policy are worth checking.
BLS data shows apparel and entertainment spending barely moved in 2024, while car insurance, housing and groceries rose - some by double digits. Why the numbers behind the top impulse-buying articles don't hold up, and a review method that starts with the bills, not the coffee.
We bridge the gap between your financial goals and premier lending services nationwide.
Bromoney is a free loan marketplace operated by Money Broker LLC (DE File No. 10406065). Bromoney is not a lender and does not make credit decisions. A hard inquiry is possible, and more than one lender may run one, and it can affect your credit score. Before you agree to any loan, the lender must disclose the loan amount, APR, finance charge, scheduled payment, and total of payments. Installment lending in Montana is overseen by the Montana Division of Banking and Financial Institutions. Covered military borrowers receive the Military Lending Act's 36% MAPR protection. Bromoney is not available in all states. We take a responsible approach to your data and do our best to prevent unwanted calls, but you may be contacted about your request.
You know the drill: one loan request, then waiting for the calls to start. Here you stay in control — we treat your information with care, you compare the options available to you, and you choose which lender or partner to move forward with. We can't speak for every partner, but we do our best to keep unwanted calls down.
Submitted over a secure connection