

Steady Income
Pay stubs, benefit letters or regular deposits show you can carry a payment. With a low score, a long and steady income record can carry real weight in a lender's decision.

Credit score lower than you hoped in Alaska? Compare bad credit loans in Alaska and see which option fits your budget.
In Alaska, the CFPB credit score tiers describe groups of borrowers, not any one lender's cutoff. Each lender sets its own line. Two lenders can look at scores in the same tier and still reach different answers, because they weigh the same report in their own ways when deciding who qualifies and on what terms. Beyond the score, lenders read the records behind it. Payment history makes up about 35% of a FICO Score for the general population, and amounts owed about 30%. Weights still vary from person to person. That's why two people in Alaska with the same score can get different results once a lender looks closer.
In Alaska, a high APR on a small, short loan can cost fewer dollars than a lower rate stretched over a longer term. Rates alone can point the wrong way. At a lower credit score, it pays to compare what each offer costs in dollars.
Under Alaska’s Small Loans Act, licensed small-loan companies use a tiered interest structure. They may charge up to 3% per month on the portion of unpaid principal up to $850, up to 2% per month on the portion above $850 through $10,000, and a rate agreed by contract on the portion above $10,000 through $25,000. Different rules may apply to other types of lenders.
The request may take a few minutes. Here's what most Alaska lenders require before they can review your information and decide whether to offer credit.
Pay stubs, benefit letters or regular deposits show you can carry a payment. With a low score, a long and steady income record can carry real weight in a lender's decision.
Some lenders review your checking account: regular deposits, a positive balance and few overdrafts tell them how you handle money from month to month, which your score alone doesn't show.
Lenders add up your monthly debt payments and compare them with your income. A lower debt-to-income ratio leaves room for a new payment, even when your score is low.
In Alaska, as across the country, the Federal Reserve's average rate for personal loans at commercial banks came close to 12%. That figure measures the broad market, not the end of it built for lower credit scores. It blends borrowers across the full score range, so it tells you little about what you'd be offered. The numbers that count for your loan are the ones printed in the agreement you sign.
For loans subject to Alaska’s general usury rule, interest agreed by contract generally may not exceed the greater of 10% per year or five percentage points above the applicable 12th Federal Reserve District advance rate. Loans above $25,000 are exempt from that general limit. Licensed small-loan companies may operate under the separate rate structure in the Alaska Small Loans Act, while banks, credit unions and other exempt institutions may be subject to different rules.
Bromoney is a financial marketplace, not a lender. If partners send offers to your Alaska account, you'll see the monthly payment, term and total cost of each side by side. Then you pick what fits your budget. Whether to move forward, and with which partner, is your call. Using Bromoney costs you nothing.
Estimate exactly how much you'll owe before you commit. Enter your loan amount and repayment term to see total costs, including fees and interest, laid out clearly.
Calculate my loanScore tiers from CFPB research come first, followed by the rules that apply to lenders in Alaska.
Deep subprime
Credit scores below 580
Subprime
580-619
Near-prime
620-659
Prime
660-719
Super-prime
720 and above
Licensed small-loan rate
Up to 3% per month on the first $850
Under Alaska's Small Loans Act, a licensed lender may charge up to 3% per month on the portion of unpaid principal up to $850; 2% per month applies to the portion above $850 through $10,000.
Amount above $10,000
Rate agreed by contract
For a licensed small loan, the rate on the portion of unpaid principal above $10,000 and up to $25,000 may be set by contract.
Regulator
Alaska Banking & Securities Div.
Small-loan license
Required in specified cases
A lender making loans of $25,000 or less and charging more than an unlicensed lender may lawfully charge generally must hold an Alaska Small Loans Act license, subject to statutory exemptions.
State rules reviewed October 2026.
Below 580, the range the CFPB calls deep subprime, many traditional banks won't lend, and the options that remain tend to be small loans for bad credit with higher costs and shorter terms. If an urgent bill is the reason you're looking, emergency and online loans for bad credit from lenders who weigh income and banking, not just FICO, are where most borrowers in this range start.
Between 580 and 619, more lenders will review your request, and unsecured installment options with longer terms start to appear. Rates are still well above what better scores get, so the amount and the total cost deserve a close look before you agree.
From 620 to 659, you're close to the line many lenders draw for their better pricing. A debt consolidation loan for bad credit becomes more realistic here, and even a modest improvement in your score can noticeably change the APR you're shown.
At 660 and above, the CFPB's prime and super-prime ranges, mainstream lenders compete for your business, which usually means lower APRs, larger amounts and longer terms. If you're just under this line, it can pay to work on your score for a few months before you borrow a larger sum.
A thin or empty credit file isn't the same as bad credit, but many lenders treat it with similar caution because there's little to score. Steady income, a checking account with regular deposits and a small first loan repaid on time are the usual ways to build a record lenders can read.
Secured loans for bad credit put an asset, such as a savings account or a vehicle, behind the debt, and some lenders let a cosigner with stronger credit share the loan. Both can improve the terms you see, but the asset or the cosigner's credit is on the line if payments stop. Most options don't require either, so a loan for bad credit with no cosigner is still the usual route.
Bad credit options also depend on your state, which sets the rules for small loans and for the lenders that make them. Choose your state to see what's available at a lower score there.
FICO Score ranges: Poor below 580, Fair 580-669, Good 670-739, Very Good 740-799, Exceptional 800-850. VantageScore tiers on the 300-850 scale: subprime 300-600, near prime 601-660, prime 661-780, superprime 781-850. FICO and VantageScore are separate companies. They build their models from different data samples and weigh factors differently, so each draws its own line for where a lower score begins. Neither range is a legal standard. Each one just reflects how that company's model reads a credit file. The bad credit loans guide goes deeper on each range.
It may be possible, but the lender makes the credit decision and applies its own eligibility criteria. Alaska permits several forms of consumer credit, including licensed small loans and deferred deposit advances. On Bromoney, the options shown in your account depend on lender availability, your information and applicable state rules. No specific product, term or approval is guaranteed.
Checking available options with Bromoney does not require a credit-bureau inquiry and does not affect your credit score. If you select a partner and continue, that partner may perform a hard credit inquiry that can affect your score.
Private label cards averaged about 31% APR and barely varied by score. That card figure comes from revolving accounts, not installment loans. It's also an average across a group of borrowers, not a price for any one person. What you'd pay on a personal loan comes down to the terms in your own offer. Prices vary by lender, so offers partners send on Bromoney can differ.
No. A promise of approval before a lender has even seen your information is a warning sign, no matter who makes it. Availability depends on the lender, the applicant's information, and where the applicant lives.
For most people, one additional hard inquiry takes fewer than five points off their FICO Score. Being turned down doesn't lower your score on its own; only the inquiry carries that small cost. Those few points are minor next to the difference in what you'd repay between two offers. To see how balances weigh on your score, try the credit utilization calculator.
Under FICO Score 9 and FICO Score 10, third-party collections that are paid in full no longer count against the score. A credit reporting company can generally report most negative information for seven years; bankruptcies can stay on a report for up to ten years. So which scoring model a lender uses matters as much as the collection itself. Older models can still count a paid collection against you.
The three nationwide credit bureaus do not report paid medical collections or medical collections with an initial balance under $500, and wait one year before an unpaid medical collection can appear. In July 2025, a federal court vacated the CFPB rule that would have removed medical bills from credit reports. Medical debt outside those limits, unpaid and past the waiting period, can still show up and weigh on your score. That's why it's worth paying or disputing it promptly.
If a lender denies credit based on a credit report, it must give the numerical credit score it used and the key factors that affected it, name the credit reporting company that provided the report, explain the right to a free copy of that report within 60 days, and explain how to fix mistakes. People can get free credit reports from each of the three nationwide bureaus every week at AnnualCreditReport.com. Start by reading the notice and requesting the free report it points to. Check it for errors you can dispute. Then consider a smaller amount, a shorter term, or a credit union. Any of these can change what you're offered. See what to do if you're denied a loan.
In Alaska, a lender's license can be checked by company name in the national NMLS Consumer Access register. Complaints about a lender go to the Alaska Department of Commerce, Community, and Economic Development, Division of Banking and Securities. Search using the exact company name printed in your loan contract, not just a brand name. If that name doesn't show up, pause and verify before you sign anything.
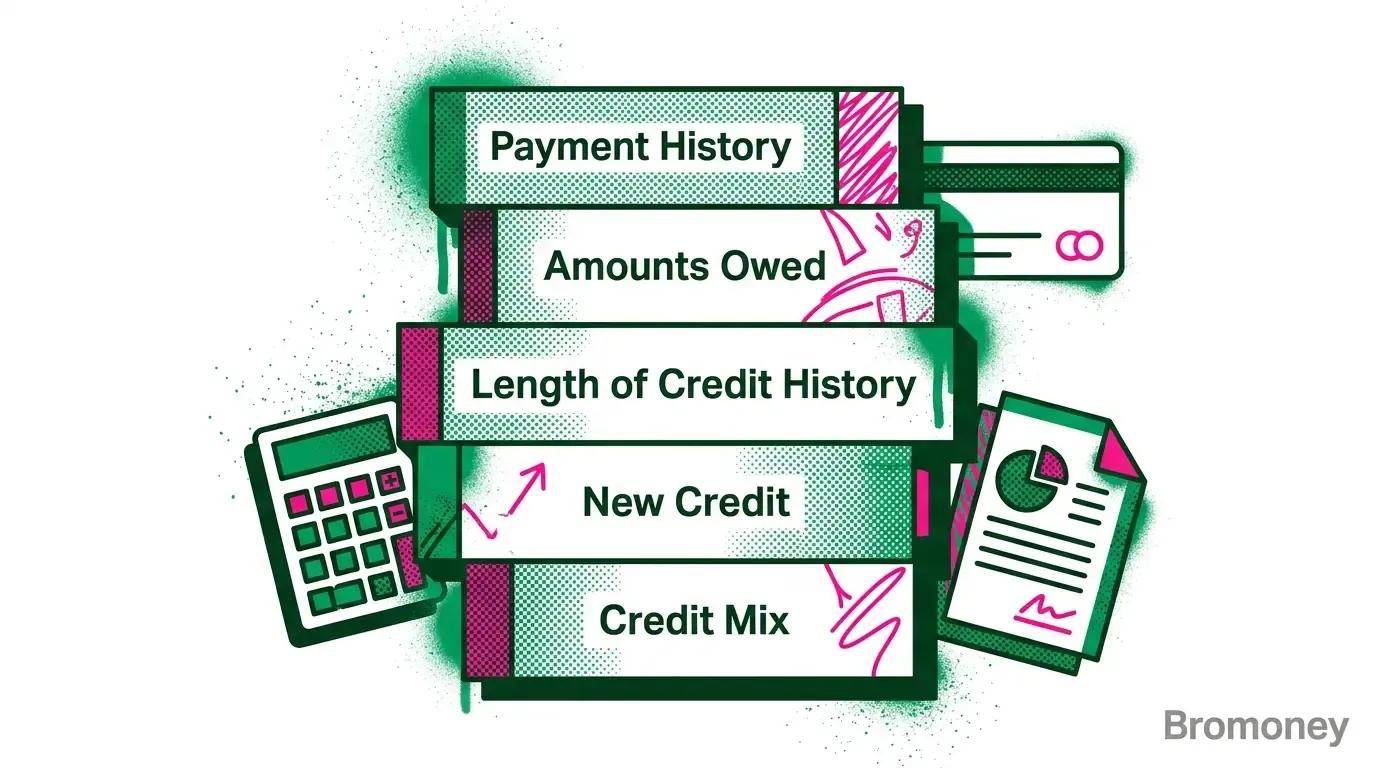
A practical breakdown of the five FICO Score factors, how each one works, and which actions improve your credit profile first.
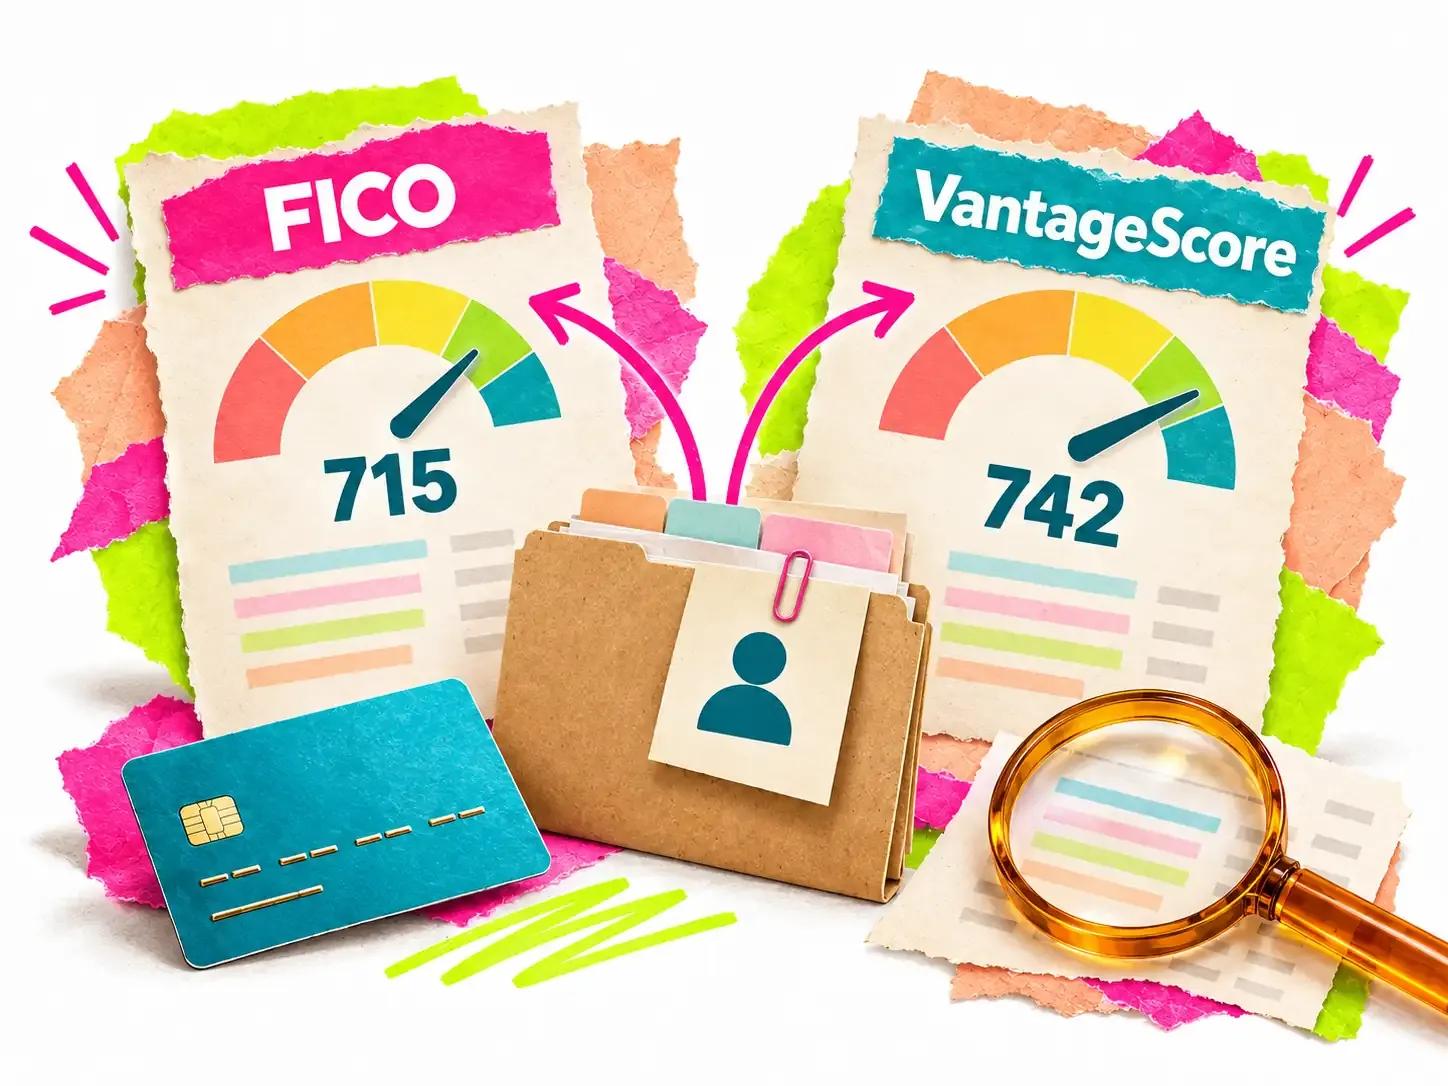
FICO and VantageScore can show different numbers for the same person because they use different models, bureau files, and update timing.
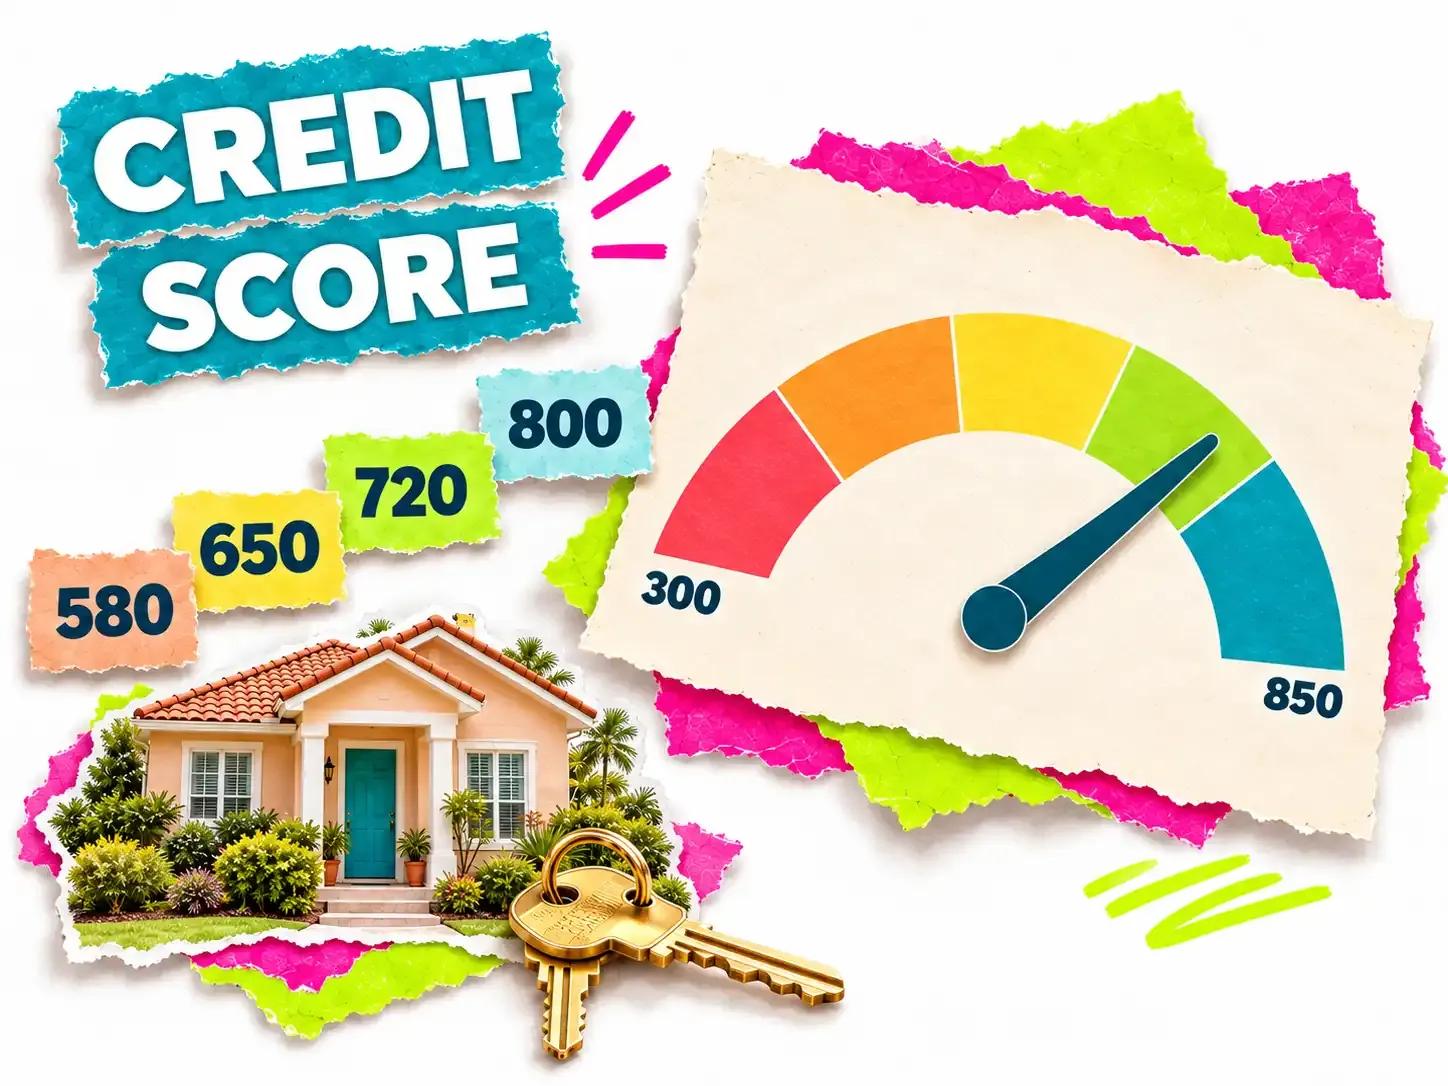
A practical guide to U.S. credit score ranges, including what 580, 650, 720, and 800 mean for mortgages, auto loans, credit cards, and rates.
We bridge the gap between your financial goals and premier lending services nationwide.
Bromoney is a financial marketplace, not a lender. Availability depends on the lender, the applicant's information, and where the applicant lives. When you submit a request form, your information is shared with lenders and partners in our marketplace so they can evaluate your request. Bromoney is operated by MONEY BROKER LLC (Delaware, DE File No. 10406065). The estimated view of your credit profile shown in your account is calculated by Bromoney from the information you provide; it is not a FICO Score, a VantageScore, a credit report or a lender's decision. This page is for general information and is not financial or legal advice.
You know the drill: one loan request, then waiting for the calls to start. Here you stay in control — we treat your information with care, you compare the options available to you, and you choose which lender or partner to move forward with. We can't speak for every partner, but we do our best to keep unwanted calls down.

Submitted over a secure connection


