Verifiable Income
A steady paycheck, benefits, or another verifiable income source can carry real weight when your credit file is less than perfect. Lenders use it to judge ability to repay, not just a FICO number.
South Dakota borrowers with imperfect credit history can connect with direct lenders through Bromoney's online platform - no branch visits, no paperwork delays. Submit one request and receive personalized bad credit loan offers matched to your financial situation.
Compare lenders and decide,
Get StartedSecure 256-bit Connection
A bad credit loan is a personal, installment, or short-term loan available to borrowers with low credit scores, generally below 580. Lenders may look at income, employment, and ability to repay along with credit history, so a low score doesn't automatically take you out of consideration. You may also see it called a loan for poor or less-than-perfect credit. Plenty of solid borrowers carry files like this.
Approved South Dakota applicants typically receive funds within one business day - often by the next morning after a same-day decision.
Direct lenders on Bromoney assess South Dakota borrowers on income and banking activity, not credit score alone - giving applicants with poor credit history a real path to approval.
Lenders in the Bromoney network serving South Dakota residents are screened for valid licensing issued by the South Dakota Division of Banking and are required to operate in compliance with Title 54 of South Dakota Codified Laws.
The request may take a few minutes. Here's what most South Dakota lenders require before they can review your information and decide whether to offer credit.
A steady paycheck, benefits, or another verifiable income source can carry real weight when your credit file is less than perfect. Lenders use it to judge ability to repay, not just a FICO number.
You'll generally need to be at least 18 and a U.S. resident. Basic, but lenders still have to check it.
An active bank account helps a lender send funds and collect repayment. It also gives them a clearer look at cash flow.
South Dakota's absence of an APR cap makes it a more lender-competitive market than neighboring Minnesota (APR capped at 33% for small loans) or Iowa (36% cap). Borrowers in SD have access to a broader lender pool, but rate variation between offers is wider - making comparison shopping essential before committing.
Consumer lending in South Dakota is regulated by the South Dakota Division of Banking, a division of the Department of Labor and Regulation. Borrowers who encounter unlicensed lenders, undisclosed fees, or deceptive practices can file a formal complaint at the Division's official portal. Licensed lenders are required to provide a written loan agreement disclosing all fees and repayment terms before funds are disbursed.
South Dakota's lending environment under SDCL Title 54 gives borrowers access to a wide range of loan products, but comparing offers independently takes time. Bromoney connects SD residents with pre-screened direct lenders in one request, cutting out the legwork and helping borrowers identify the lowest available rate for their credit profile.
Estimate exactly how much you'll owe before you commit. Enter your loan amount and repayment term to see total costs, including fees and interest, laid out clearly.
Calculate my loanLegal lending restrictions for SD residents.
Max Loan Amount
No statutory cap
Based on South Dakota statutes - lender-set limits apply
Max Term
Varies by product
South Dakota sets no universal maximum repayment term for consumer loans
APR/Fees
No rate cap
South Dakota imposes no statutory APR ceiling on consumer loans - lender-disclosed rates govern
Rollovers
Permitted with conditions
South Dakota law limits rollovers on short-term payday loans to a maximum of 4 per loan agreement (SDCL § 54-4-36). For other consumer loan products, refinancing conditions and any associated fees must be fully disclosed in the loan agreement per lender terms.
Information provided is for educational purposes only. Borrowers are encouraged to review all loan terms carefully before signing. Interest rates and fees vary by lender and loan type.
Need a payment plan you can actually map out? Installment loans spread repayment across scheduled dates, which can make the path easier to follow than one lump-sum payoff.
If the gap is small and your next check is close, a payday option may cover the bill. The window's tight, and the cost can add up, so read the repayment amount before you choose.
Some borrowers also look at secured loans, credit-union alternatives, or credit-builder products. These can work differently from online loan options, especially if membership or collateral is involved.
Bad credit loans online can look different by state. Loan amounts, terms, APR caps, rollover rules, and repayment options may change based on local law. If you carry less-than-perfect credit, compare the options available to you with your income and budget in mind, then review your state page before you choose.


The average US consumer unit spent $78,535 in 2024 - about $6,545 a month. This page sets that spending record against the price indexes for the same two years, category by category, using our own CE-CPI crosswalk, and states plainly what the figures cannot show.
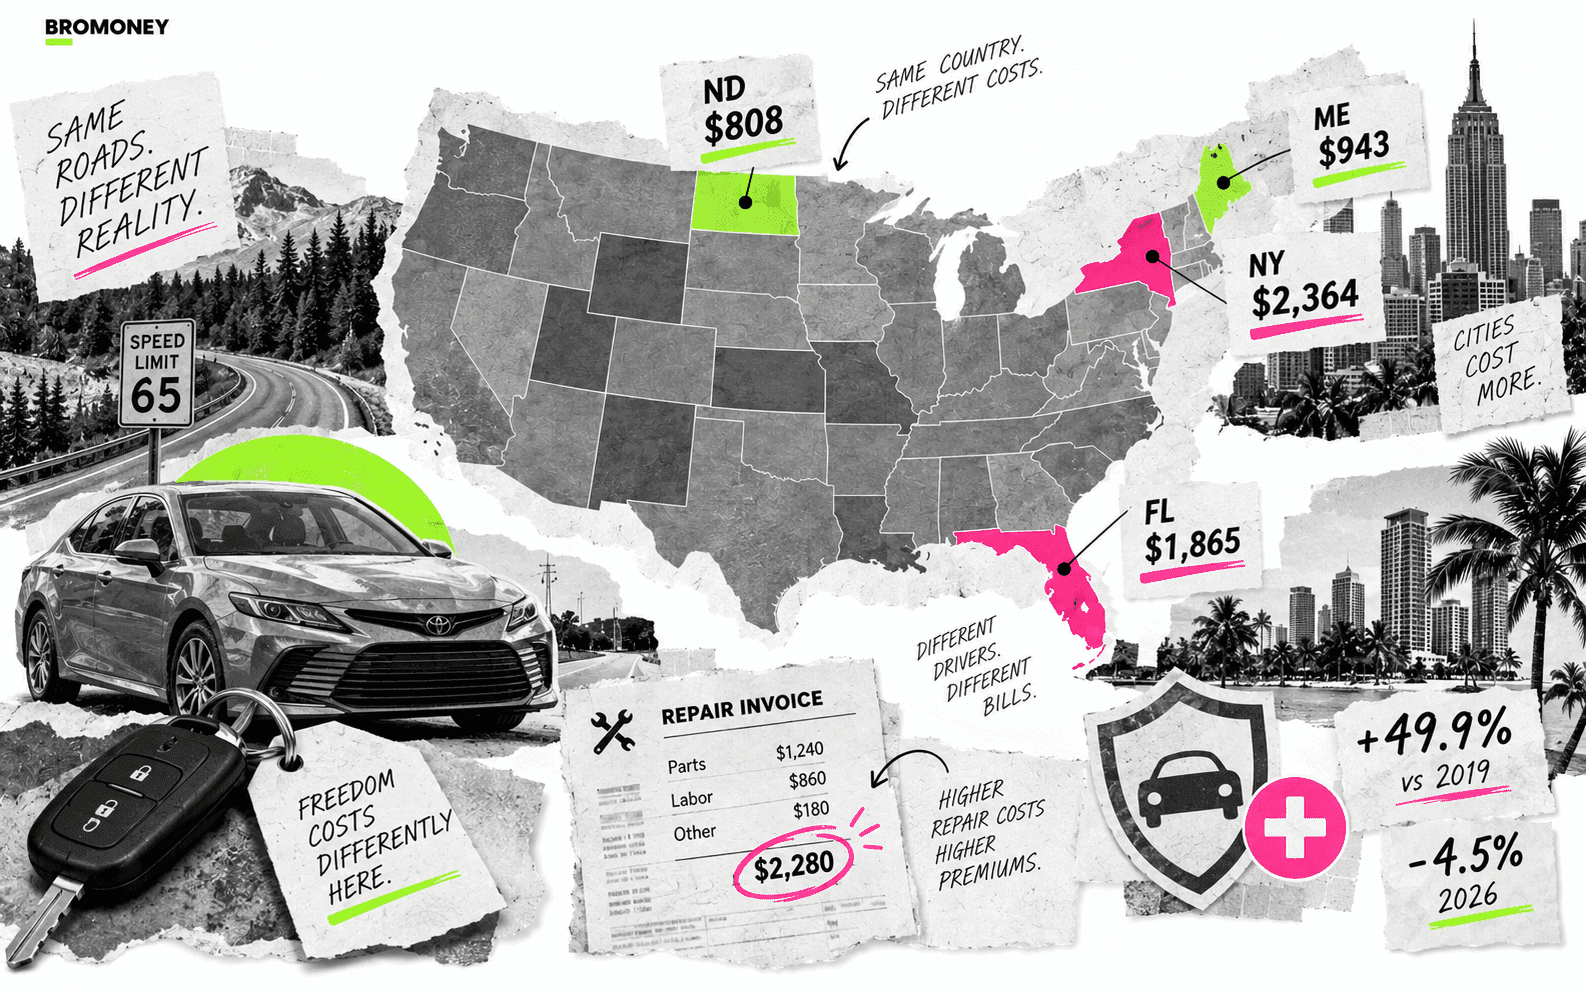
Car insurance spending rose 12.3 percent in 2024, one of only two costs BLS called statistically significant. NAIC's 2023 state averages, why rates are falling even as the level sits 49.9 percent above 2019, what actually drives claims costs, and which levers on your policy are worth checking.
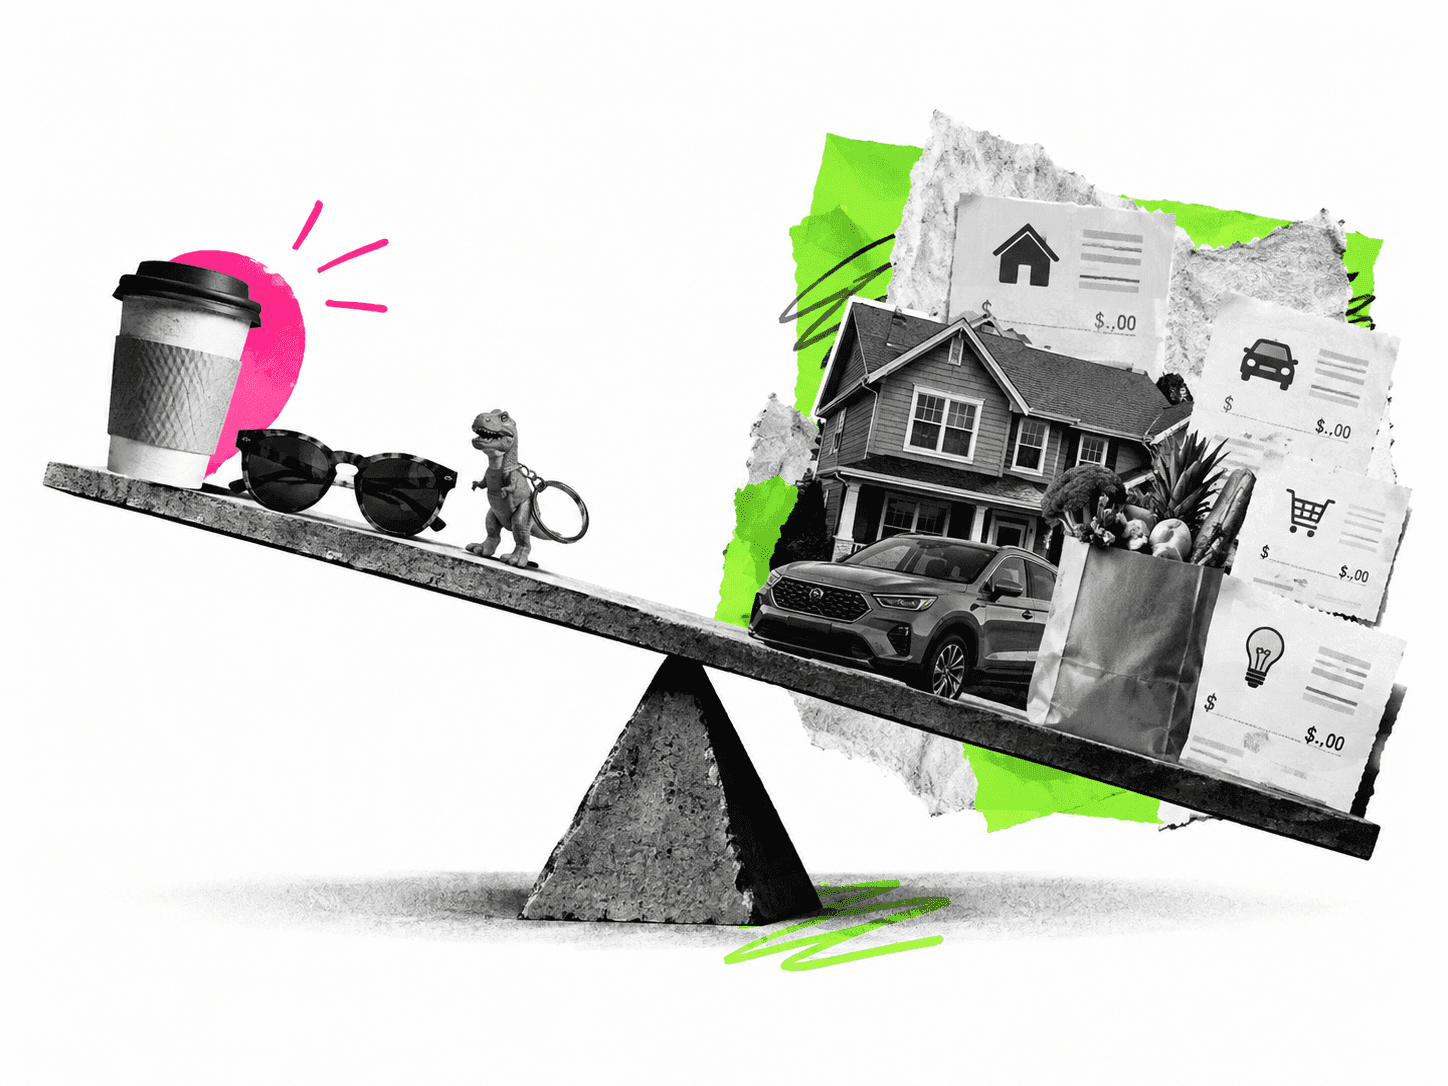
BLS data shows apparel and entertainment spending barely moved in 2024, while car insurance, housing and groceries rose - some by double digits. Why the numbers behind the top impulse-buying articles don't hold up, and a review method that starts with the bills, not the coffee.
We bridge the gap between your financial goals and premier lending services nationwide.
This page is informational and does not guarantee approval. Actual rates depend on your lender and South Dakota regulations.
You know the drill: one loan request, then waiting for the calls to start. Here you stay in control — we treat your information with care, you compare the options available to you, and you choose which lender or partner to move forward with. We can't speak for every partner, but we do our best to keep unwanted calls down.
Submitted over a secure connection