Verifiable Income
A steady paycheck, benefits, or another verifiable income source can carry real weight when your credit file is less than perfect. Lenders use it to judge ability to repay, not just a FICO number.
Access personal installment loans in Kentucky, even with a poor credit history. Bromoney connects you with direct lenders online, offering clear terms and compliant rates to meet your financial needs.
Compare lenders and decide,
Get StartedSecure 256-bit Connection
A bad credit loan is a personal, installment, or short-term loan available to borrowers with low credit scores, generally below 580. Lenders may look at income, employment, and ability to repay along with credit history, so a low score doesn't automatically take you out of consideration. You may also see it called a loan for poor or less-than-perfect credit. Plenty of solid borrowers carry files like this.
Lenders in Kentucky often process applications within one business day. Once your documents are verified and the loan is approved, funds are deposited directly via ACH transfer.
Lenders in Kentucky review more than just your FICO score. Applicants with scores from 520 may qualify, as income stability and debt-to-income (DTI) ratio are key factors.
All lenders are licensed under Kentucky Revised Statutes (KRS) Chapter 286. They adhere to state-mandated disclosure rules and rate caps enforced by the KDFI.
The request may take a few minutes. Here's what most Kentucky lenders require before they can review your information and decide whether to offer credit.
A steady paycheck, benefits, or another verifiable income source can carry real weight when your credit file is less than perfect. Lenders use it to judge ability to repay, not just a FICO number.
You'll generally need to be at least 18 and a U.S. resident. Basic, but lenders still have to check it.
An active bank account helps a lender send funds and collect repayment. It also gives them a clearer look at cash flow.
For subprime borrowers, Kentucky's average personal loan APR is 24–32%. This is more competitive than in West Virginia but often higher than in Ohio. In rural counties like Harlan or Leslie, online marketplaces are a key resource for accessing loans.
The Kentucky Consumer Protection Act and the Department of Financial Institutions (KDFI) protect borrowers. The KDFI investigates complaints and enforces disclosure laws. Before signing, verify a lender's state license and report unlicensed operators to the KDFI.
Kentucky residents benefit from the Consumer Loan Act (KRS 286.4), which limits certain fees and mandates full APR disclosure. Bromoney ensures you only see offers from lenders who follow these rules, letting you compare compliant options transparently.
Estimate exactly how much you'll owe before you commit. Enter your loan amount and repayment term to see total costs, including fees and interest, laid out clearly.
Calculate my loanLegal lending restrictions for KY residents.
Max Loan Amount
$15,000
Based on Kentucky statutes for unsecured personal installment loans
Max Term
60 months
Maximum allowed repayment window for personal installment loans in Kentucky
APR/Fees
Up to 36% APR
Effective rate cap for licensed consumer lenders under Kentucky law
Rollovers
Allowed
Kentucky law permits refinancing, but the new loan must adhere to all state lending regulations.
Information provided is for educational purposes only. Borrowers are encouraged to review all loan terms carefully before signing. Interest rates and fees vary by lender and loan type.
Need a payment plan you can actually map out? Installment loans spread repayment across scheduled dates, which can make the path easier to follow than one lump-sum payoff.
If the gap is small and your next check is close, a payday option may cover the bill. The window's tight, and the cost can add up, so read the repayment amount before you choose.
Some borrowers also look at secured loans, credit-union alternatives, or credit-builder products. These can work differently from online loan options, especially if membership or collateral is involved.
Bad credit loans online can look different by state. Loan amounts, terms, APR caps, rollover rules, and repayment options may change based on local law. If you carry less-than-perfect credit, compare the options available to you with your income and budget in mind, then review your state page before you choose.
First, check your debt-to-income (DTI) ratio; most Kentucky lenders prefer a DTI below 45%. Then, use a marketplace to compare offers from licensed lenders who review your entire financial profile, not just your FICO score. A verifiable income source is crucial. Avoid submitting multiple applications at once, as each hard inquiry can lower your score.
No single state-mandated minimum exists. Lenders often work with borrowers whose FICO scores start at 520. For scores below that, a co-signer may be needed. Applicants with scores from 560–620 typically qualify for unsecured installment loans, though the APR will reflect the risk, usually falling in the 28–36% range.
Online lender marketplaces are the most accessible solution for residents in rural Kentucky counties like Pike or Harlan. Licensed online lenders fund loans statewide via ACH transfer. Platforms that connect you only with lenders licensed by the KDFI ensure the same legal protections apply everywhere in the state.
Yes, many Kentucky-licensed lenders offer installment loans starting at $500–$1,000 for borrowers with subprime credit. These smaller loans usually have shorter terms (6–18 months) and may carry higher APRs. They are ideal for covering specific expenses without overborrowing. Use a comparison tool to identify lenders offering sub-$2,000 products in Kentucky.
You can complete the form and review any options available in your Bromoney account. A lender or partner makes its own credit decision and may consider information such as credit history, income, existing obligations, and state availability. Terms and availability vary, and no outcome is guaranteed.
There is no single APR for bad-credit loans. The APR shown in an option is determined by the lender or partner and can vary based on the loan terms, the information provided, and state availability. Review the APR, fees, payment schedule, and total cost before deciding whether to continue.
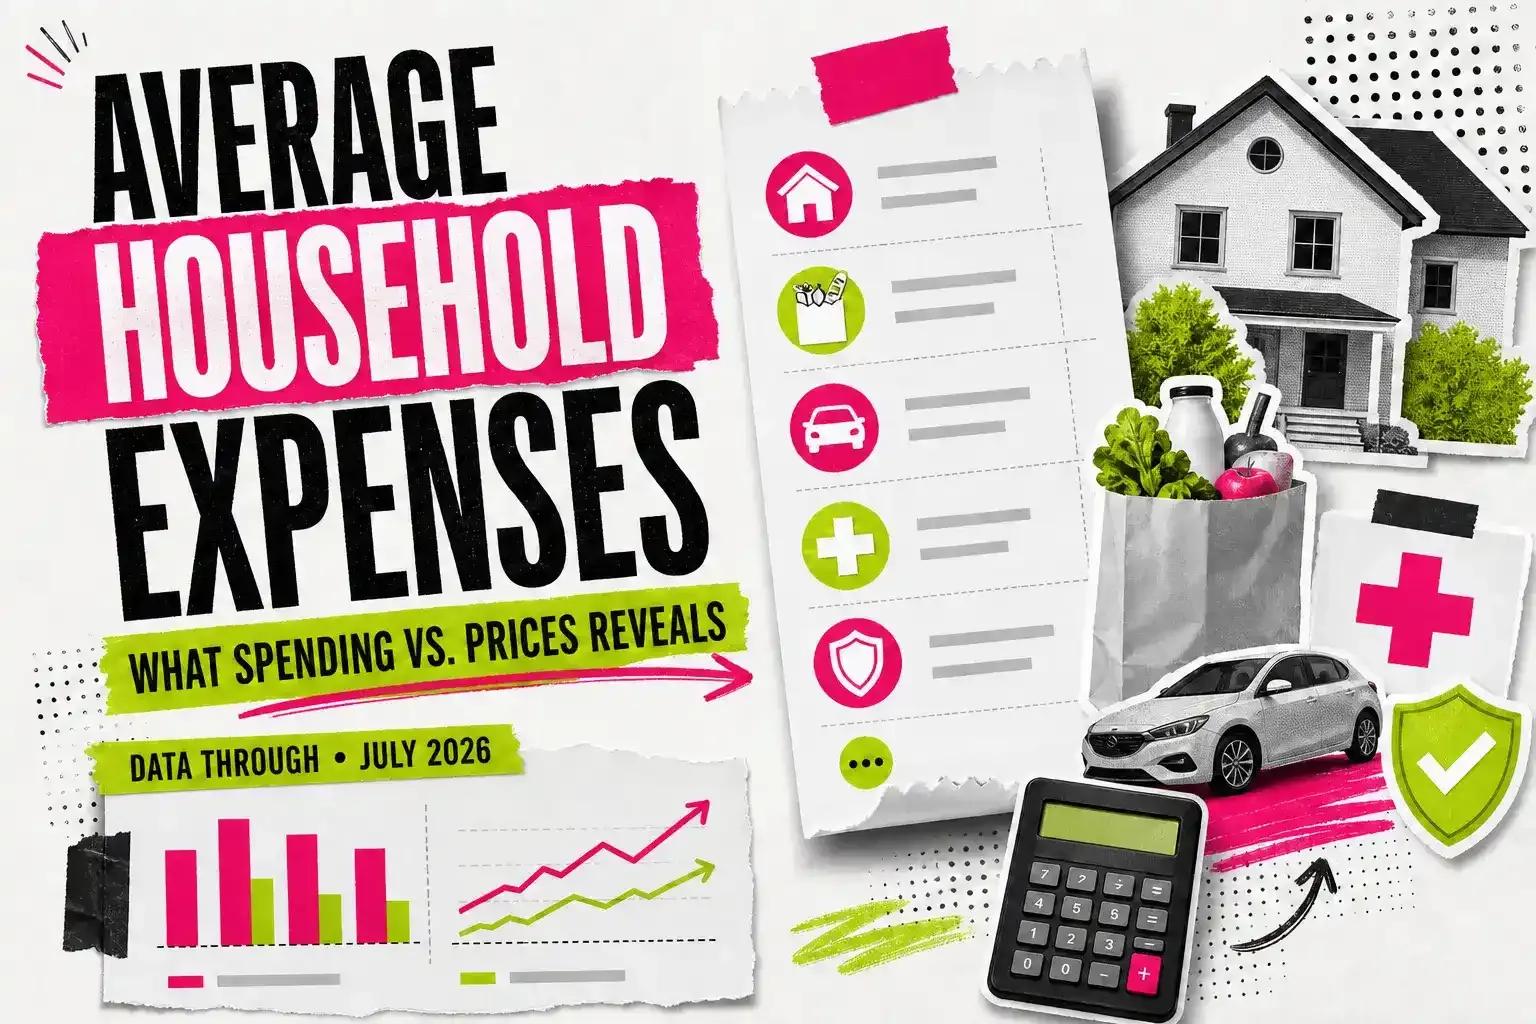
The average US consumer unit spent $78,535 in 2024 - about $6,545 a month. This page sets that spending record against the price indexes for the same two years, category by category, using our own CE-CPI crosswalk, and states plainly what the figures cannot show.
We bridge the gap between your financial goals and premier lending services nationwide.
This page is informational and does not guarantee approval. Actual rates depend on your lender and Kentucky regulations.
You know the drill: one loan request, then waiting for the calls to start. Here you stay in control — we treat your information with care, you compare the options available to you, and you choose which lender or partner to move forward with. We can't speak for every partner, but we do our best to keep unwanted calls down.
Submitted over a secure connection


