

Steady Income
Pay stubs, benefit letters or regular deposits show you can carry a payment. With a low score, a long and steady income record can carry real weight in a lender's decision.

Credit score lower than you'd like, with winter heating bills piling up? Compare bad credit loans in Virginia and choose the option that fits your budget.
In Virginia, as elsewhere, the credit tiers from CFPB research describe groups of borrowers studied together. They don't mark a line any single lender draws. Each lender sets its own cutoff. Within the same tier, two lenders can look at the same borrower and reach different views, based on their own standards. Lenders read more than your score: payment history, income and the debt you carry. For most people, payment history makes up about 35% of a FICO Score, and amounts owed about 30%. The weight can shift from person to person. That's why two people with the same score can see different offers.
In Virginia, an offer's rate and its dollar cost don't always point the same way. A high APR on a small, short loan may cost you fewer dollars. A lower rate over a longer term can cost more. At a lower score, compare both the rate and the total dollar cost before you choose.
Virginia applies different pricing rules depending on the type of lender and loan. A consumer finance company licensed under Chapter 15 may make installment loans from $300 to $35,000 and charge up to 36% simple annual interest, along with certain fees permitted by law. Short-term loans follow a separate set of limits.
The request may take a few minutes. Here's what most Virginia lenders require before they can review your information and decide whether to offer credit.
Pay stubs, benefit letters or regular deposits show you can carry a payment. With a low score, a long and steady income record can carry real weight in a lender's decision.
Some lenders review your checking account: regular deposits, a positive balance and few overdrafts tell them how you handle money from month to month, which your score alone doesn't show.
Lenders add up your monthly debt payments and compare them with your income. A lower debt-to-income ratio leaves room for a new payment, even when your score is low.
In Virginia, an installment loan gives you the full amount up front. You repay it in even monthly payments with a known end date. That makes it easier to plan your budget, even at a lower score. Compare installment loans in Virginia before you choose.
In Virginia, a personal loan can suit you when you need a larger sum or more time to repay. It can also roll several debts into a single monthly payment. In August 2026, the average rate on 24-month personal loans at commercial banks was 11.90%, according to Federal Reserve data. This is a broad market average, not a rate for any particular credit-score tier. You can also compare personal loans for a bigger amount.
Virginia regulates short-term loans separately from traditional two-week payday lending. A licensed short-term lender may make a loan of up to $2,500, generally for four to 24 months. The lender may charge up to 36% simple annual interest plus a monthly maintenance fee equal to the lesser of 8% of the originally contracted loan amount or $25. A shorter term may be permitted when the monthly payment stays within the income-based limit set by state law. Total fees and charges are also capped at 50% of the original loan amount for loans of $1,500 or less and 60% for loans above $1,500.
Virginia generally limits contractual interest to 12% per year unless another law authorizes a higher rate. Different licensed lending regimes provide exceptions. Consumer finance companies operating under Chapter 15 may charge up to 36% simple annual interest on qualifying installment loans, while short-term loans under Chapter 18 follow their own rate, fee and term limits.
Bromoney is a financial marketplace, not a lender. If partners send offers to your account, you can line up the monthly payment, term and total cost side by side. You decide whether to continue, and with which partner. Using Bromoney costs you nothing.
Estimate exactly how much you'll owe before you commit. Enter your loan amount and repayment term to see total costs, including fees and interest, laid out clearly.
Calculate my loanScore tiers from CFPB research come first, followed by the rules that apply to lenders in Virginia.
Deep subprime
Credit scores below 580
Subprime
580-619
Near-prime
620-659
Prime
660-719
Super-prime
720 and above
Consumer finance interest rate
Up to 36% per year
Virginia-licensed consumer finance companies may charge up to 36% simple annual interest on installment loans from $300 to $35,000. Certain processing and other permitted fees may apply separately.
Consumer finance loan range
$300 to $35,000
Chapter 15 installment loans generally run from six to 120 months and are repaid in substantially equal installments.
Regulator
Virginia SCC (Financial Institutions)
Consumer finance license
Required to operate under Chapter 15
A lender charging more than Virginia's general 12% contractual interest limit on covered consumer loans generally must operate under an applicable Virginia licensing framework, subject to statutory exemptions.
State rules reviewed November 2026.
Below 580, the range the CFPB calls deep subprime, many traditional banks won't lend, and the options that remain tend to be small loans for bad credit with higher costs and shorter terms. If an urgent bill is the reason you're looking, emergency and online loans for bad credit from lenders who weigh income and banking, not just FICO, are where most borrowers in this range start.
Between 580 and 619, more lenders will review your request, and unsecured installment options with longer terms start to appear. Rates are still well above what better scores get, so the amount and the total cost deserve a close look before you agree.
From 620 to 659, you're close to the line many lenders draw for their better pricing. A debt consolidation loan for bad credit becomes more realistic here, and even a modest improvement in your score can noticeably change the APR you're shown.
At 660 and above, the CFPB's prime and super-prime ranges, mainstream lenders compete for your business, which usually means lower APRs, larger amounts and longer terms. If you're just under this line, it can pay to work on your score for a few months before you borrow a larger sum.
A thin or empty credit file isn't the same as bad credit, but many lenders treat it with similar caution because there's little to score. Steady income, a checking account with regular deposits and a small first loan repaid on time are the usual ways to build a record lenders can read.
Secured loans for bad credit put an asset, such as a savings account or a vehicle, behind the debt, and some lenders let a cosigner with stronger credit share the loan. Both can improve the terms you see, but the asset or the cosigner's credit is on the line if payments stop. Most options don't require either, so a loan for bad credit with no cosigner is still the usual route.
Bad credit options also depend on your state, which sets the rules for small loans and for the lenders that make them. Choose your state to see what's available at a lower score there.
FICO Score ranges: Poor below 580, Fair 580-669, Good 670-739, Very Good 740-799, Exceptional 800-850. VantageScore 4.0 tiers on the 300-850 scale: subprime 300-600, near prime 601-660, prime 661-780, superprime 781-850. FICO and VantageScore are separate models built by different companies. Each uses its own data and formula, so the same credit history can fall into different ranges depending on the scoring model. The bad credit loans guide goes deeper on each range.
A low credit score on its own doesn't stop you from comparing loan options in Virginia.
Checking available options with Bromoney does not require a credit-bureau inquiry and does not affect your credit score. If you select a partner and continue, that partner may perform a hard credit inquiry that can affect your score.
No. Bromoney doesn't guarantee approval. Treat any promise of approval made before a lender has reviewed your information as a warning sign, no matter who makes it. Availability depends on the lender, the applicant's information, and where the applicant lives.
For most people, one additional hard inquiry takes fewer than five points off their FICO Score, although the impact varies by credit history. A denial itself does not lower your FICO Score; a hard inquiry associated with the application may affect it. To see how balances weigh on your score, try the credit utilization calculator.
Collections reported as paid in full are disregarded by FICO Score 9 and the FICO Score 10 suite. A credit reporting company can generally report most negative information for seven years; bankruptcies can stay on a report for up to ten years. Older FICO models may still consider some paid nonmedical collections. Paying a nonmedical collection generally does not by itself require the collection account to be removed from your credit report.
The three nationwide credit bureaus do not report paid medical collections or medical collections with an initial balance under $500. Unpaid medical debt generally must be more than 365 days delinquent and over $500 before it can appear on a credit report. In July 2025, a federal court vacated the CFPB rule that would have removed medical bills from credit reports. An eligible unpaid medical collection may therefore still appear and may affect some credit-scoring models.
If a lender denies credit based in whole or in part on a consumer report, the adverse-action notice must identify the consumer reporting company and explain your right to obtain a free copy of the report if you request it within 60 days, as well as your right to dispute inaccurate or incomplete information. If a credit score was used in the adverse action, the notice must also provide the score and the key factors that adversely affected it. People can get free credit reports from each of the three nationwide bureaus every week at AnnualCreditReport.com. Read the notice closely and review the report for errors you can dispute. You can also consider whether a different loan amount, term or type of lender may better fit your situation. See what to do if you're denied a loan.
The Virginia State Corporation Commission's Bureau of Financial Institutions provides license-verification resources for regulated financial institutions, including consumer finance companies and short-term lenders. Search the exact legal company name shown in the loan agreement. If you cannot find an institution in the expected license listing, contact the Bureau before proceeding, because banks, credit unions and other financial institutions may be regulated or listed differently.
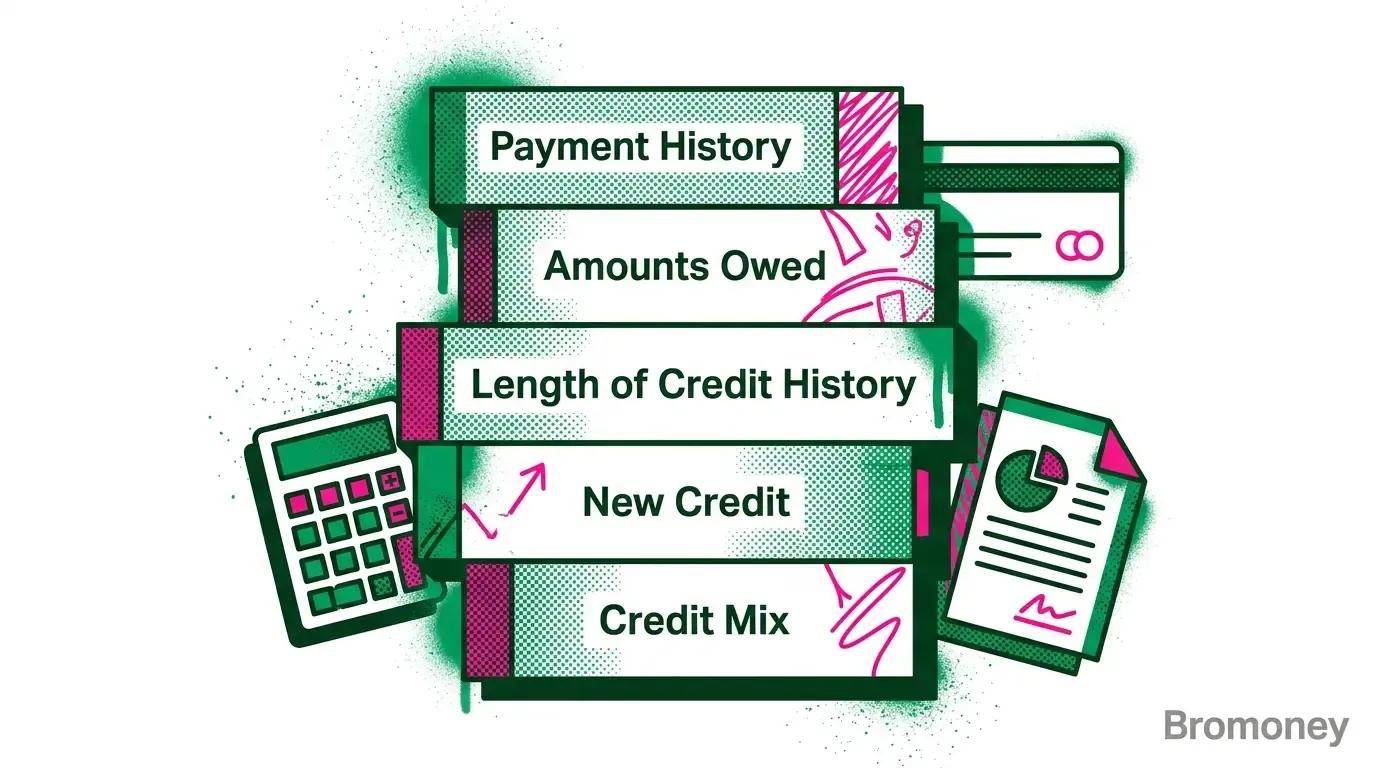
A practical breakdown of the five FICO Score factors, how each one works, and which actions improve your credit profile first.
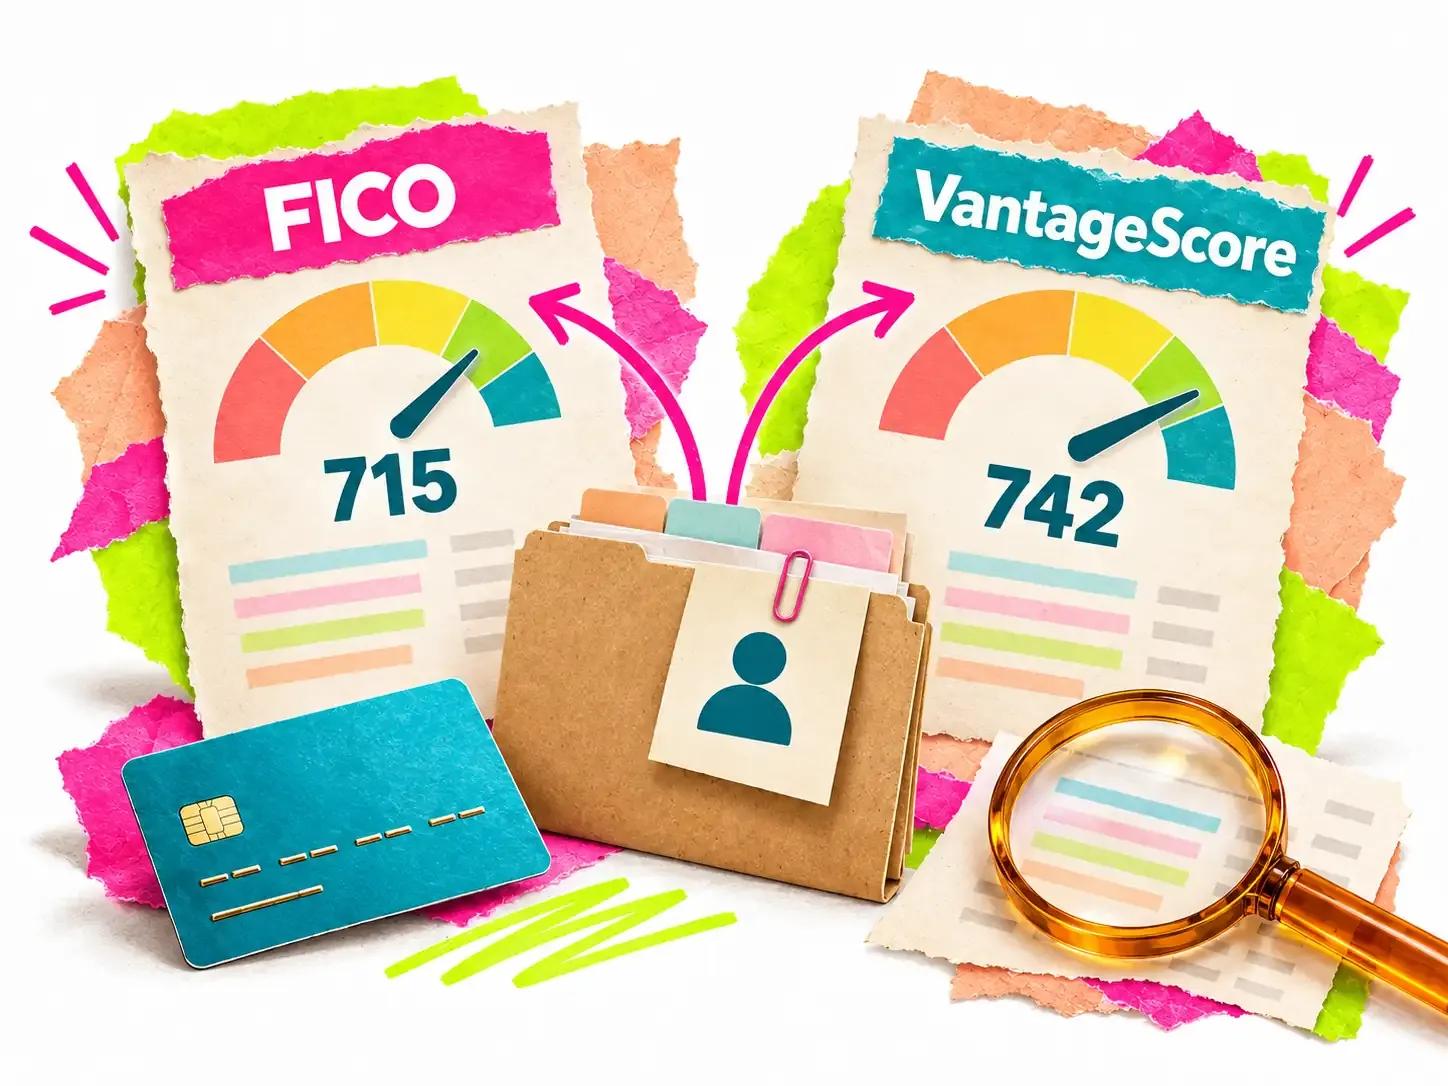
FICO and VantageScore can show different numbers for the same person because they use different models, bureau files, and update timing.
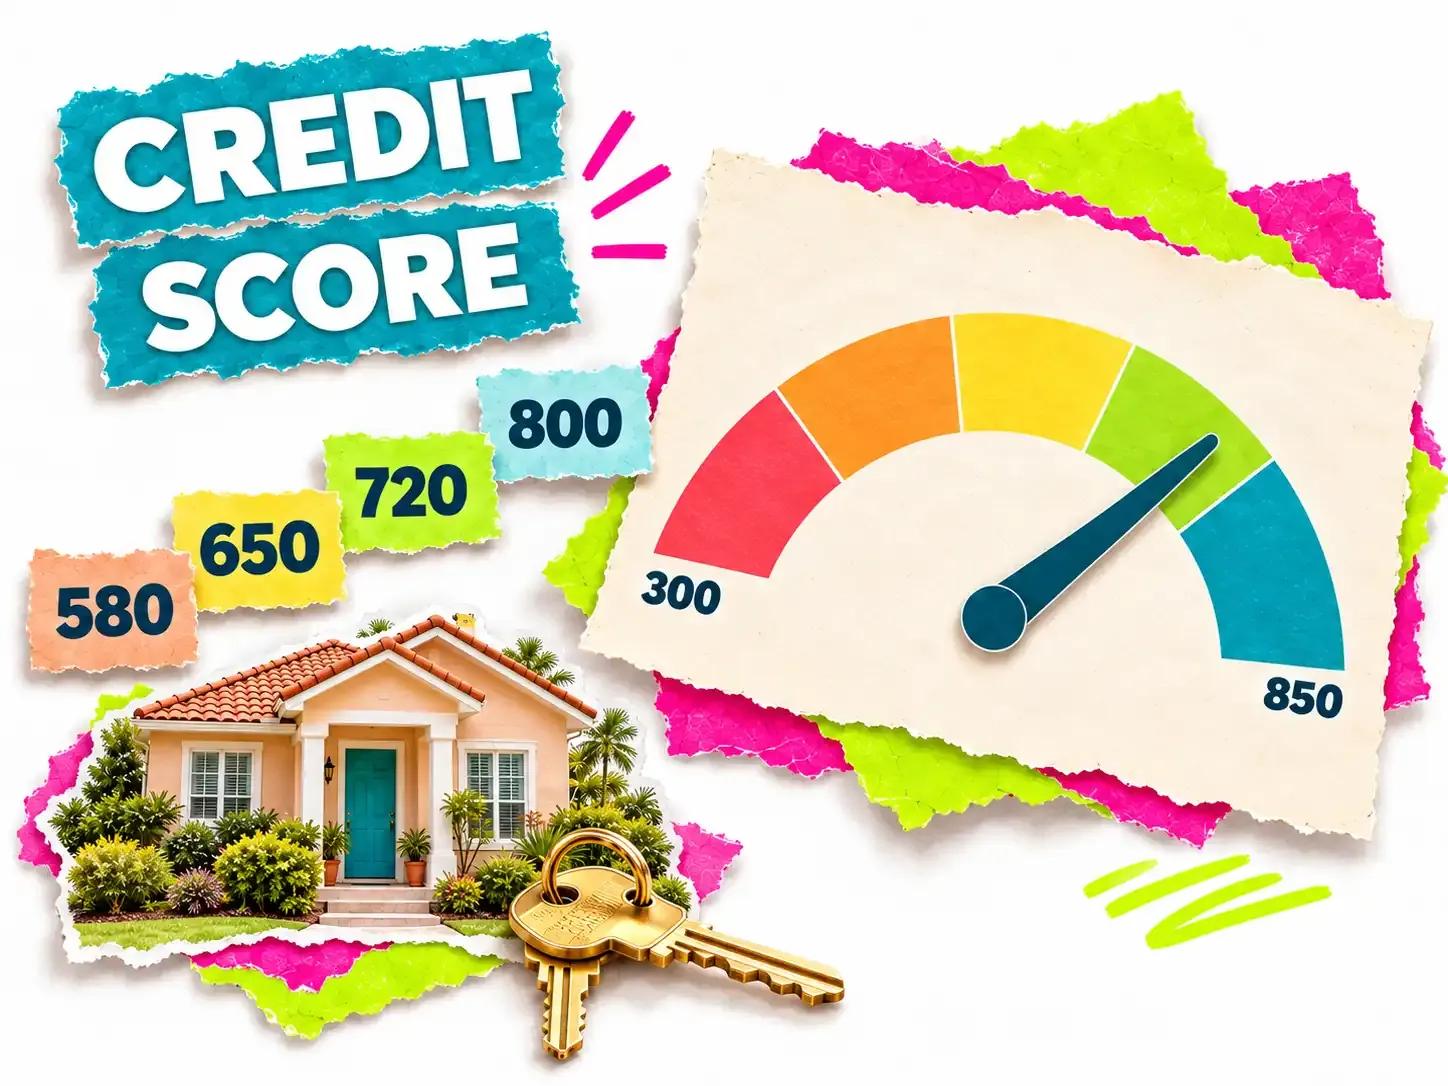
A practical guide to U.S. credit score ranges, including what 580, 650, 720, and 800 mean for mortgages, auto loans, credit cards, and rates.
We bridge the gap between your financial goals and premier lending services nationwide.
Bromoney is a financial marketplace, not a lender. Availability depends on the lender, the applicant's information, and where the applicant lives. When you submit a request form, your information is shared with lenders and partners in our marketplace so they can evaluate your request. Bromoney is operated by MONEY BROKER LLC (Delaware, DE File No. 10406065). The estimated view of your credit profile shown in your account is calculated by Bromoney from the information you provide; it is not a FICO Score, a VantageScore, a credit report or a lender's decision. This page is for general information and is not financial or legal advice.
You know the drill: one loan request, then waiting for the calls to start. Here you stay in control — we treat your information with care, you compare the options available to you, and you choose which lender or partner to move forward with. We can't speak for every partner, but we do our best to keep unwanted calls down.

Submitted over a secure connection


