How to Stop Living Paycheck to Paycheck on Uneven Income
How to Stop Living Paycheck to Paycheck on Uneven Income
Money arrives, bills clear, and by the time the next payday lands there is nothing left to carry forward. That is living paycheck to paycheck, and when income is uneven the cycle repeats no matter how carefully you track spending. To stop living paycheck to paycheck you need one stored month, not a larger deposit. Below: what the actual problem is, how to size the amount that ends it, and how to build that amount when there is apparently nothing to build it with.
What does living paycheck to paycheck actually mean?
It means your spending is funded by money that has not arrived yet. Every obligation is covered by the next paycheck rather than by money already in your checking account. Nothing is wrong with the arithmetic - your monthly income may exceed outgoings over a year - but there is no gap between money coming in and money going out. Making ends meet every month is not the same as being out of the cycle.
That is why the paycheck-to-paycheck cycle survives raises, side income, and good months. More money through the same pipe still leaves the pipe empty at the end of each cycle. You do not have to earn more to break the paycheck-to-paycheck cycle. What breaks it is a stored amount sitting between the two.
Why is timing the real problem, not income size?
Because a shortfall is almost always a date problem. Rent is due on the 1st, payday is the 6th, and the five-day gap has to be filled. Over a year the money is there; on the 1st it is not.
Uneven income makes this worse in a specific way: the gap changes length. One month it is three days, the next it is three weeks. You cannot plan around a distance that keeps moving, so every cycle gets handled as an improvisation. Percentage-based budgets struggle here for reasons worth understanding on their own - why percentage rules break down on irregular income covers that. This page assumes they do, and moves to the repair.
What is a base month?
A base month is what you need to get through one full calendar month without looking at the next deposit. It covers housing, utilities, transportation, food, insurance, minimum debt payments, and nothing else - no savings goals, no discretionary categories, no annual costs.
It is a single number, not a plan. Its only job is to say how much has to be sitting in your account on the 1st for the month to run without a deposit arriving. Everything else here is measured against it.
How do you calculate your base month?
Pull the last three to six months of bank statements. Add up what you could not have skipped: rent or mortgage, utilities, phone and internet, transportation, groceries, insurance, required minimum debt payments. Take the highest month, not the average - an average smooths over the exact month that stretched you thin.
Do not add a percentage on top and do not round up to feel safe. An inflated base month makes the target feel unreachable and stalls the process. If you have never separated required from optional spending, building a household budget from scratch walks through the split, and a budget template gives you somewhere to enter the numbers.
Example. Housing $1,400, utilities $180, transportation $260, groceries $520, insurance $140, minimum debt payments $200. Base month = $2,700. That is the number this method is aimed at.
What is a buffer and how is it different from an emergency fund?
A buffer is money that covers ordinary timing gaps. An emergency fund covers events - a job loss, a medical bill, a car that will not start. They are different amounts with different jobs, and the buffer comes first.
The distinction matters because an emergency fund is supposed to sit untouched, which leads people to treat all savings that way and cover the timing gap some other way instead. A buffer is working capital: used, drawn down, and refilled, in that order, every month. Confusing the two is the most common reason people with savings end up living paycheck to paycheck anyway.
How do you build a first buffer when there is nothing left to save?
You do not save it out of the surplus, because there is no surplus. You build it out of the extra money a good month produces over a normal one, and you keep the whole thing small enough to be reachable.
Your first savings target is a partial buffer - one week of your base month, not the full month. Using the $2,700 example, one week is roughly $625. Small enough that a single better-than-usual month produces most of it, large enough to absorb the two- or three-day gap that currently forces a shortfall.
The mechanics: on any deposit above your normal amount, move a fixed share into a separate savings account on the day it lands, before anything clears. A share of the extra cash, not a leftover. Leftovers do not exist in this cycle by definition.
Should the buffer be spent or kept untouched?
Spent, then refilled. A buffer that is never used is just savings sitting next to the problem it was supposed to solve. The rule: it covers the gap when the gap opens, and it gets topped back up from the next deposit before any other savings transfer.
This is the part people get wrong most often. They build $800, feel the relief of having it, then refuse to touch it when rent lands early. Two months later the same shortfall repeats with the buffer still full. The measure of a working buffer is not its balance on a given day; it is whether the balance returns to target after each cycle.
How much buffer is enough to break the cycle?
One full base month. When you hold it in cash on the 1st, the calendar stops mattering - the month is already funded before any deposit arrives. That is the point at which the cycle is structurally over rather than temporarily quiet.
Getting there is staged, and each stage buys something concrete:
- One week. Absorbs the ordinary early-bill, late-deposit gap.
- Two weeks. Absorbs a single deposit arriving late, in full.
- One month. Removes the dependency and ends the paycheck-to-paycheck cycle. You spend this month's money next month.
Most people feel the change at two weeks and stop there. The stretch from two weeks to a full month is the one that actually lets you stop living paycheck to paycheck.
What happens when the buffer runs out?
You rebuild the savings from the smallest tier, not from the target. If it drains to zero, the goal is not one month again - it is one week again. Restarting at the full target is what makes the rebuild feel too big to start.
At the same time, treat a drained buffer as information. A buffer that empties once a year absorbed exactly what it was built for. One that empties every second month is telling you the base month is understated, or that required spending has crept upward. Recalculate the base month before refilling - building toward a number that is already wrong wastes the next three months.
How does this work when income is seasonal?
Seasonal income is the same problem on a longer cycle. Instead of a five-day gap you cover a three-month one, so the target scales: multiply the base month by the number of consistently low months and build toward that during the high season.
The mechanics do not change. The extra cash a high-season deposit brings moves into the savings account on the day it lands, at a fixed share. During the low season, a fixed amount transfers back each month on the same date, so the low season behaves like a steady one. Only the target size and the refill window change.
Example. Base month $2,700, four reliably low months per year. Target = $10,800. Across eight earning months that is $1,350 set aside per month. If the high season is shorter, the share per deposit goes up, not the target down.
How do you handle expenses that do not arrive every month?
Keep them out of the buffer. Annual insurance, registration, tuition, holidays, and quarterly tax payments are known amounts you know in advance you will have to pay - not timing gaps. Funding them from the buffer is what drains it three weeks before you need it.
Total them for the year, divide by twelve, and hold that amount separately. Separating one-time from recurring expenses covers how to identify them. The buffer stays reserved for the gap between when money is due and when it arrives - nothing else.
What should you do with the next deposit?
Move a fixed share out on payday, before any bill clears. Not at the end of the month, not after you pay the essentials. The share can be small - five percent is fine - but it has to leave the account first, because the timing is the whole mechanism.
Put it somewhere with a little friction: a second checking account or a savings account at the same bank, transferable in a day but not attached to a card. Far enough not to be spent by accident, close enough that you will use it when the gap opens.
How long does it take?
Longer than the arithmetic suggests, because early months get interrupted. A reasonable expectation on uneven income is one to three months to reach the one-week tier and six to twelve months to reach a full base month, assuming a few above-average deposits along the way. Progress is not linear. You will still be living paycheck to paycheck for part of that stretch; the marker of progress is the direction of your savings. The measure is not whether the balance grew every month, but whether it ended each quarter higher than it started.
Where does debt fit while you build the buffer?
Keep making minimum payments and get the first tier of the buffer in place before you pay anything extra toward debt. Without a buffer, the next timing gap goes onto a card, and a week of that undoes a month of paying off debt.
Once the one-week tier holds, split the share: part to the buffer, part to pay off your debt, starting with the highest rate. That is usually credit card debt - and credit cards are also what the cycle reaches for when the buffer is empty, so the two feed each other. Clearing credit card debt without a buffer only frees room on the same credit cards you will use at the next shortfall.
Retirement contributions sit outside this trade-off. If your employer contributes to your retirement plan, keep that running while you work on the cycle.
When a buffer is not the answer
If your required monthly spending is consistently higher than what you earn, a buffer will not form. There is nothing to divert, and each month subtracts from whatever the previous one held. Building toward a target under those conditions produces months of effort and no balance.
That is a different problem, worth naming honestly rather than treating as a discipline failure. The levers are structural: reducing a fixed cost you pay every month - housing, transportation, insurance - will help you save money without depending on spending habits changing at all, and so will changing the terms on existing obligations or finding a way to increase your income. A buffer is a timing tool. It cannot close a gap that exists over the full year rather than within the month.
If the two are close but not inverted - a shortfall of $50 or $100 a month - the method still works, but the base month has to come down first. Cut the number, then build toward it.
Who is this approach not for?
Three situations where a different tool fits better. First, stable income on a fixed schedule: the timing gap is small and predictable, and a simple percentage split does the job - the 50/30/20 rule is the usual starting point.
Second, people who want per-dollar control rather than a single floor number. If tracking every category is something you will actually maintain, assigning every dollar a job gives finer control than a base month does.
Third, anyone whose income arrives daily or weekly in small amounts rather than in lumps. The logic still holds, but split the base month into weekly targets - a monthly one will not correspond to anything you experience.
How do you keep from sliding back?
Recalculate the base month twice a year. Required spending drifts upward quietly - a rent increase, a higher insurance premium - and a buffer sized against last year's number quietly stops covering a full month.
The second habit is checking the refill, not the balance. Once a month, confirm the savings returned to target after whatever the buffer absorbed. A balance lower than last month is fine if it was used. A balance flat for a quarter usually means it is being protected rather than used, and the underlying gap is still being covered some other way.
Denis Goncharenko
Head of Content
Editorial Policy: no secondary statistics. Every claim is linked to an official source and dated — datasets and methods are open for review.
Was this article helpful?
Same blogs
Saving Money on Groceries Is Not a Test of Willpower
Federal data shows six grocery categories moving at different rates, not one bill rising evenly. Why the national CPI, the CES spending survey, and USDA's own forecast are each the wrong number to budget against - and how to build your own monthly figure from 8 to 12 weeks of receipts instead.
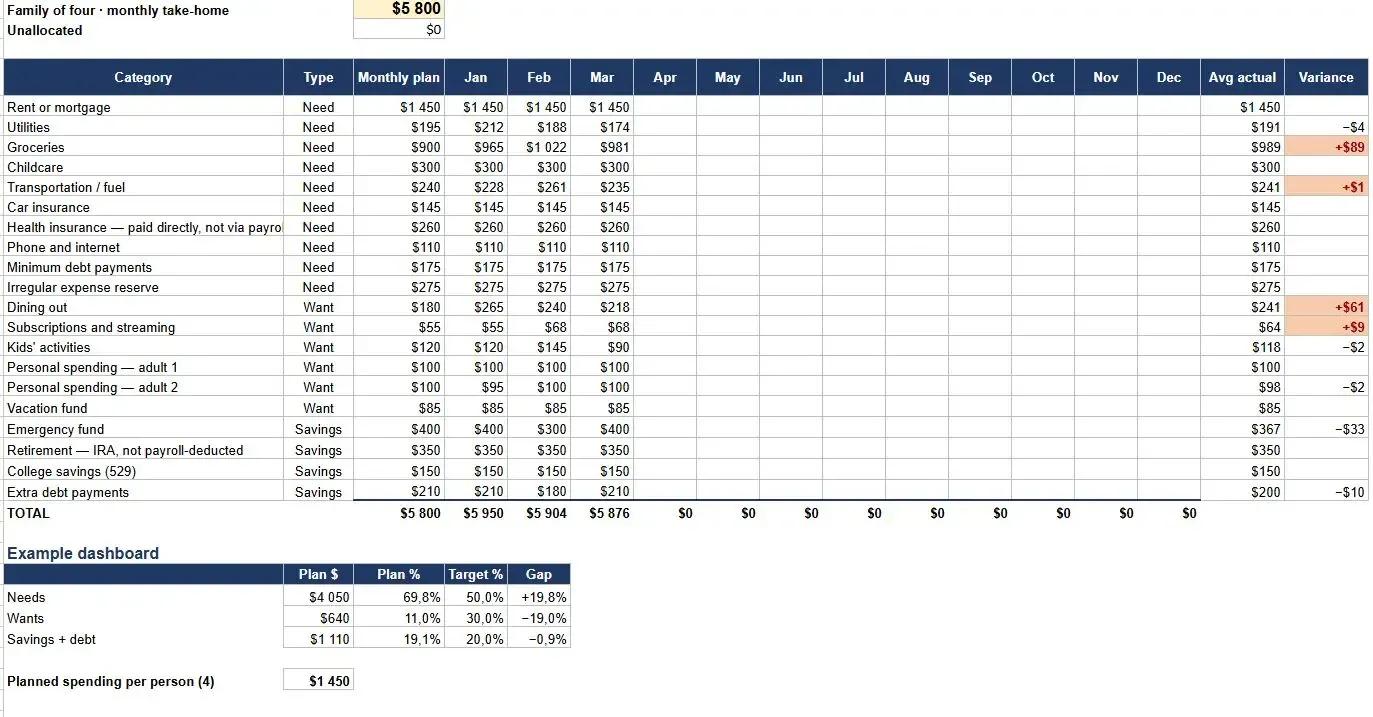
Free Family Budget Template for Excel and Google Sheets
A free household budget spreadsheet for families of three to five, with categories pre-filled and a separate tab that spreads yearly bills like insurance and registration across all twelve months. No email, no sign-up, works in Excel and Google Sheets.
Why Parent PLUS Loans Have Become a Hidden Retirement Crisis for American Parents
Parent PLUS loans can follow parents into retirement, reduce savings, and expose Social Security benefits to offset after default. Here is what near-retirement borrowers should know.